

Good Sunday evening MacroEdge Readers & Community,
This evening we’re going to explore the latest market dynamics - and look at how NVDA is really the only thing worth monitoring at this point for the broader equity market - along with oil and yields… The latter two will continue to get direct attention and intervention from both the US government and foreign governments - like we’re seeing with the situation in France - and countries around the world have started clamping down on exports of their own petroleum products (the latest to be Niger)...
Equity markets in the US are in a very fragile place - and some of my brightest friends in our industry have such varying opinions as to what will happen next. While there remains the possibility of all-time highs on the Nasdaq - it will garner much of my attention on the US equity side here for the remainder of the year - and likely in the first half of 2027. With early signs of headwinds mounting for things like data center construction and neocloud IPOs - there’s going to be a race to get Anthropic and OpenAI offloaded onto the retail bagholders before the end of the year - though there is still real possibility that one or both are delayed. My consensus story is that we will see many companies in the space get blanked here over the next 24 months - but the government will have a say in picking the winners - per se - with tax dollar support.
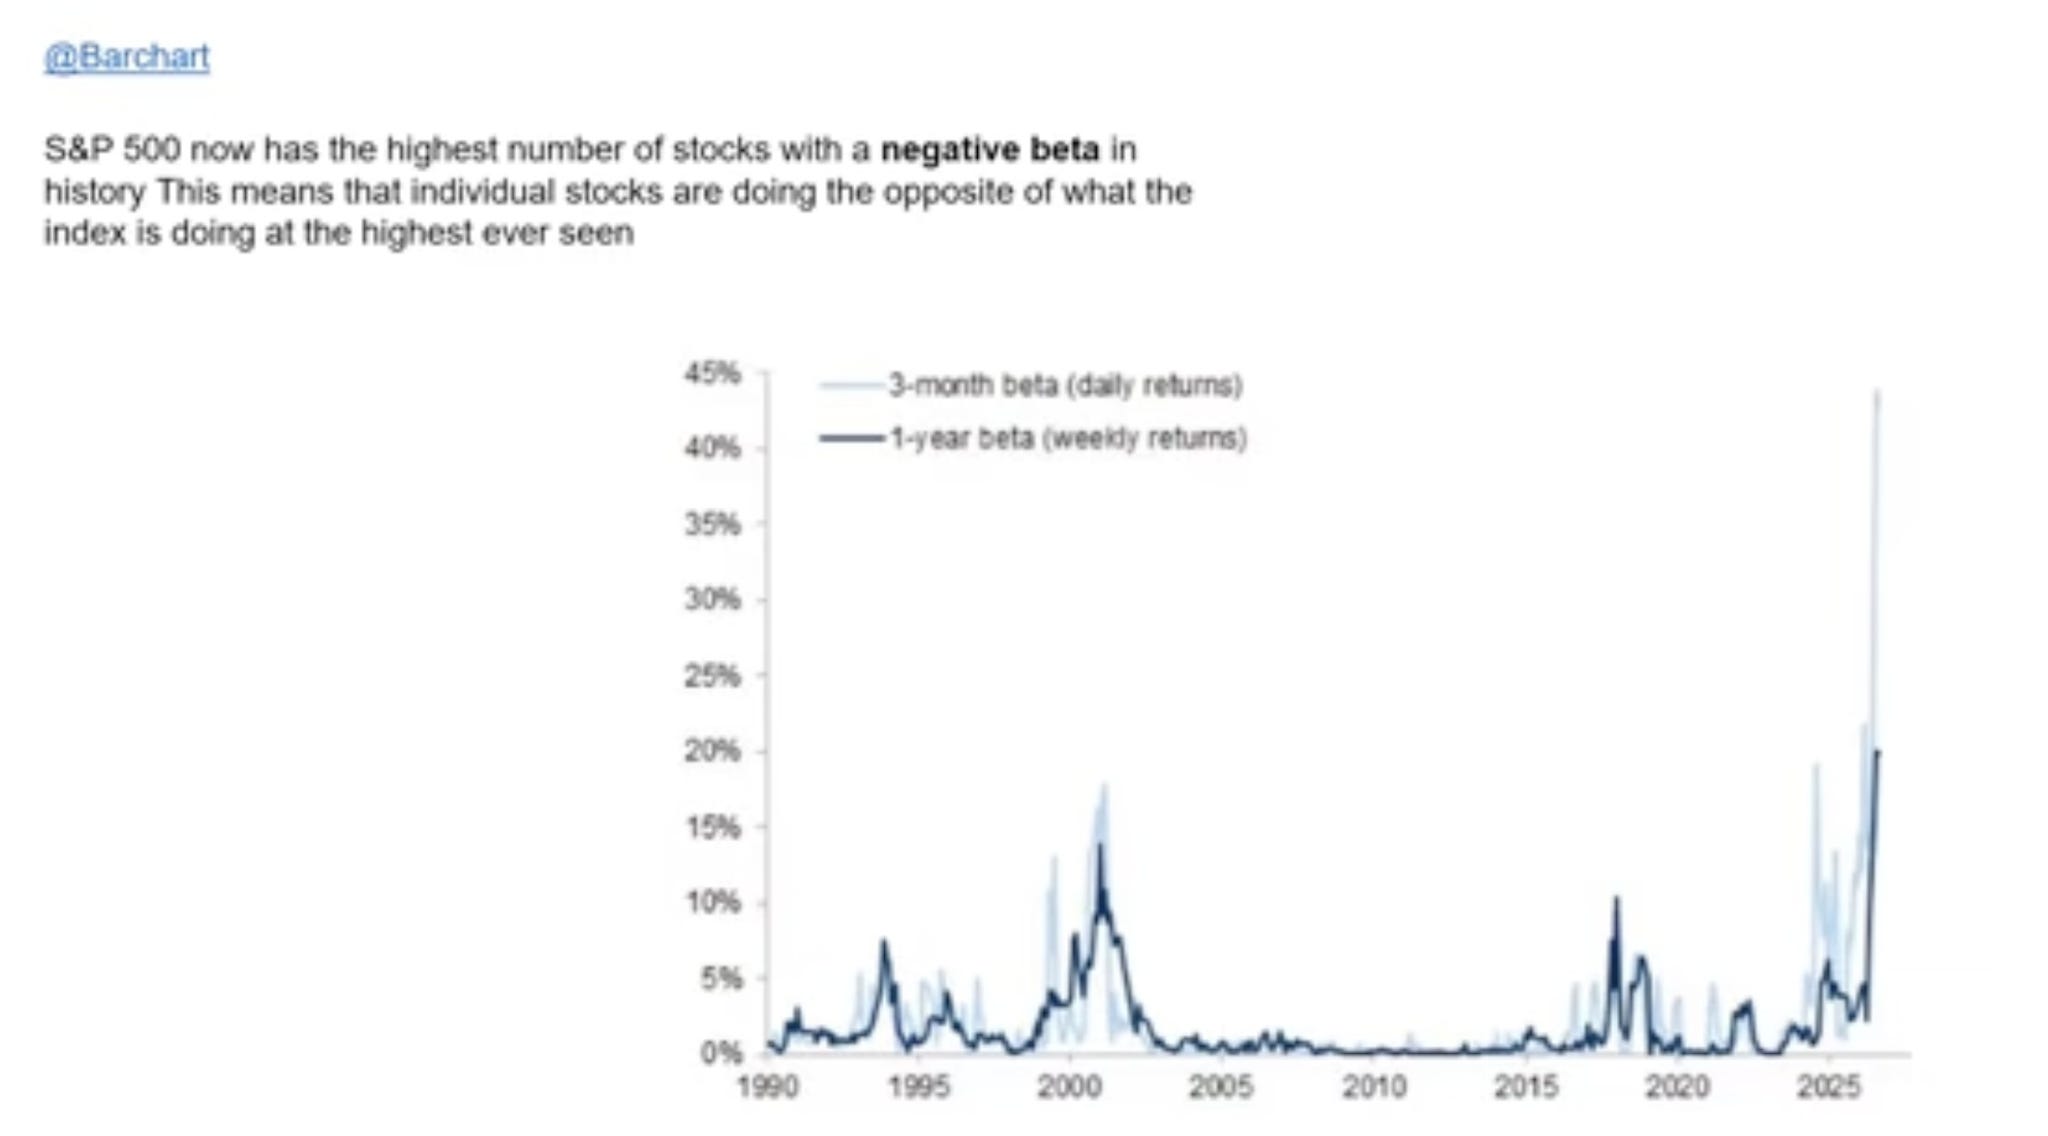
Negative beta in the markets is at its highest level ever as just a few heavy weighted equities now drive market performance:
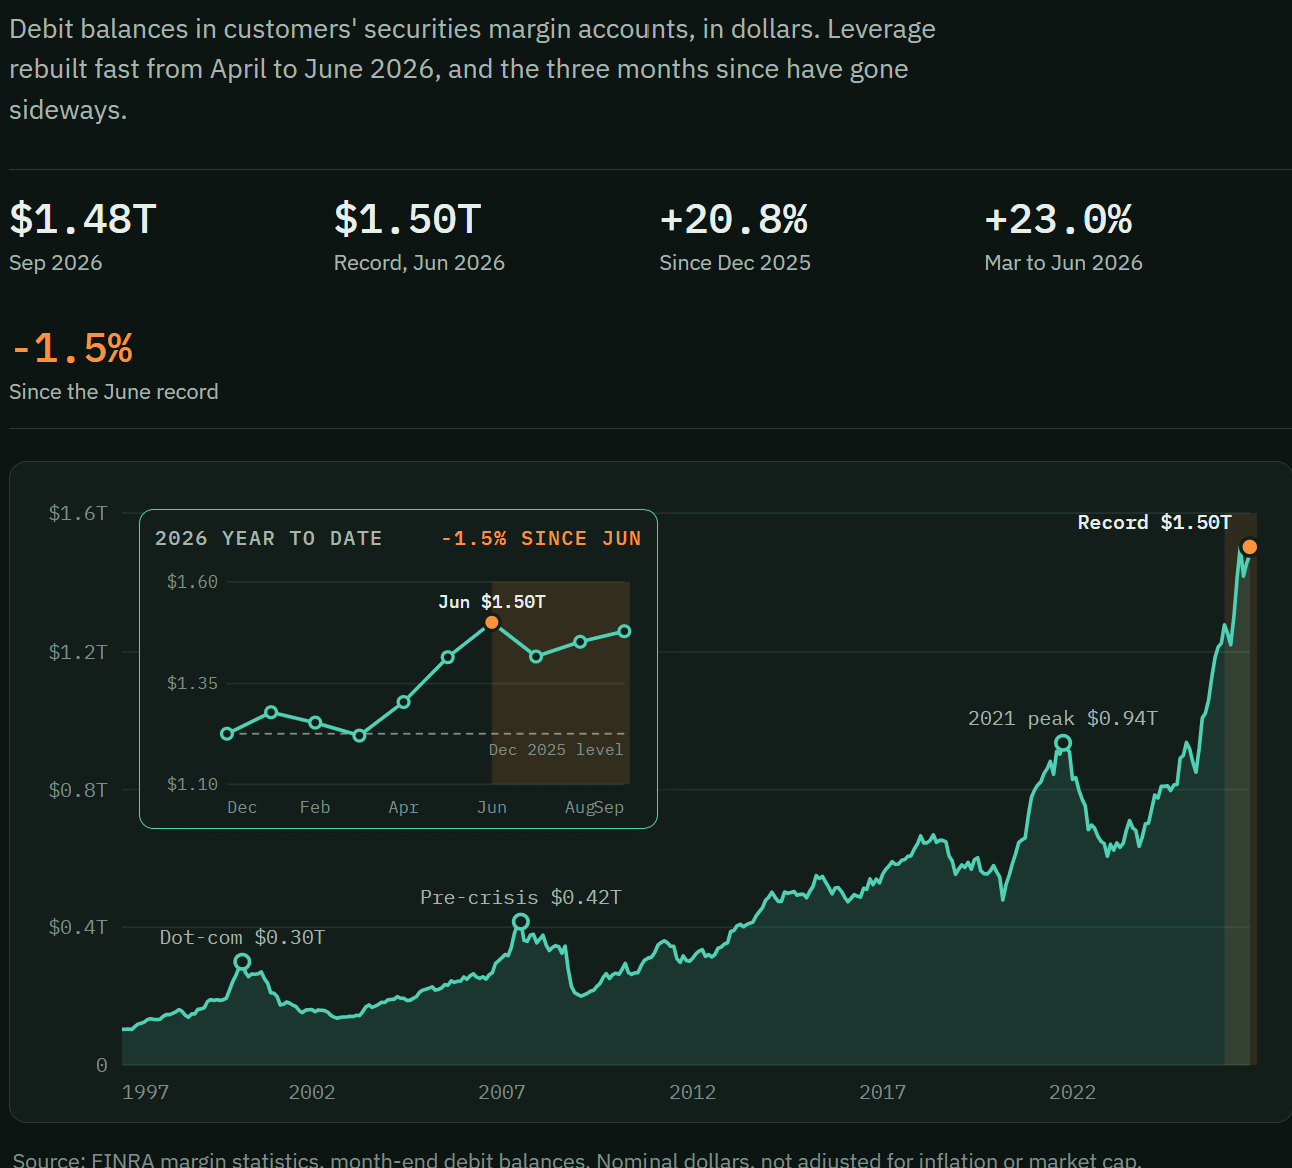
In overnight markets - futures are advancing in the US and Japan is off to a strong start to the week. With Nvidia and broader tech being at such an important spot - this is really what’s going to drive things. Sentiment got very bearish on Friday - and it will reverse and everyone will be ‘I told you so!’ tomorrow - we’re at a very idiotic time in markets with the levels of leverage and retail involvement we now have today. There’s one video I posted back in May of a ‘trading group’ that I continue to think will be useful for us to look back in the future about this point in time in markets.
On the oil price front - prices are off slightly overnight (about 1.5%) and I expected at least one more major effort to try and drop oil prices before midterms… that may come with some joint announcement made with Russia - and I noted more extensively in the Weekly Oil & Gas Macro Note that the Russian Foreign Ministry ‘congregation’ will be traveling to both GCC nations and Iran early this week for discussions. I find it highly unlikely at this point that we don’t see some kind of meaningful escalation pre-midterm to exert maximum pressure on the Trump Administration - which may come from the Iranian side through a combination of pressures in the Strait of Hormuz and through their proxy - Ansarallah in Yemen. We’ve labelled the trade there thus far with ‘patience through October’ in which we start to see a market better price in the risks facing the global oil market - especially as countries shift towards protectionism - and don’t just blindly blow their own emergency reserves to save other countries.
This evening we’re going to keep it sharp with the following covered:
> Report Schedule for the Week and Macro Week Ahead
> Weekly Oil and Gas Macro Note and Intro
> Nvidia Roulette - the Fate of the Broader Market
> Mentally Preparing for the Final Super TACO
> A Look at Asia - the TSE/Nikkei/Nasdaq and AI/Japan Correlation
Not yet a MacroEdge Ozone subscriber? Upgrade below and don’t miss a beat with our 4x a week macro notes, portfolio strategy, commentary, and more.
Report Schedule for the Week and Macro Week Ahead
In the week ahead - we’re going to cover a lot of ground as always… This week isn’t particularly exciting on the macro data front - and we’re in a Fed blackout window now. It is, however, busy for the AI thematic and earnings reports… outlined below.
Tuesday: War Note and Macro Data Exploration - Inflation and Employment
Wednesday: Ozone - Portfolio Strategy Note, Oil and Gas Research - Strategy Note
Friday: Redeye Macro Note
Saturday: Oil and Gas Research - Strategy Note
Macro Week Ahead —->
Monday: n/a
Tuesday: n/a
Wednesday: n/a
Thursday: US Housing Data (Claims I ignore these days)
Friday: S&P Global Flash PMIs
Earnings This Week >$300bn Market Cap
GE, PM - Tuesday
Meta, Tesla - Wednesday
P&G - Thursday
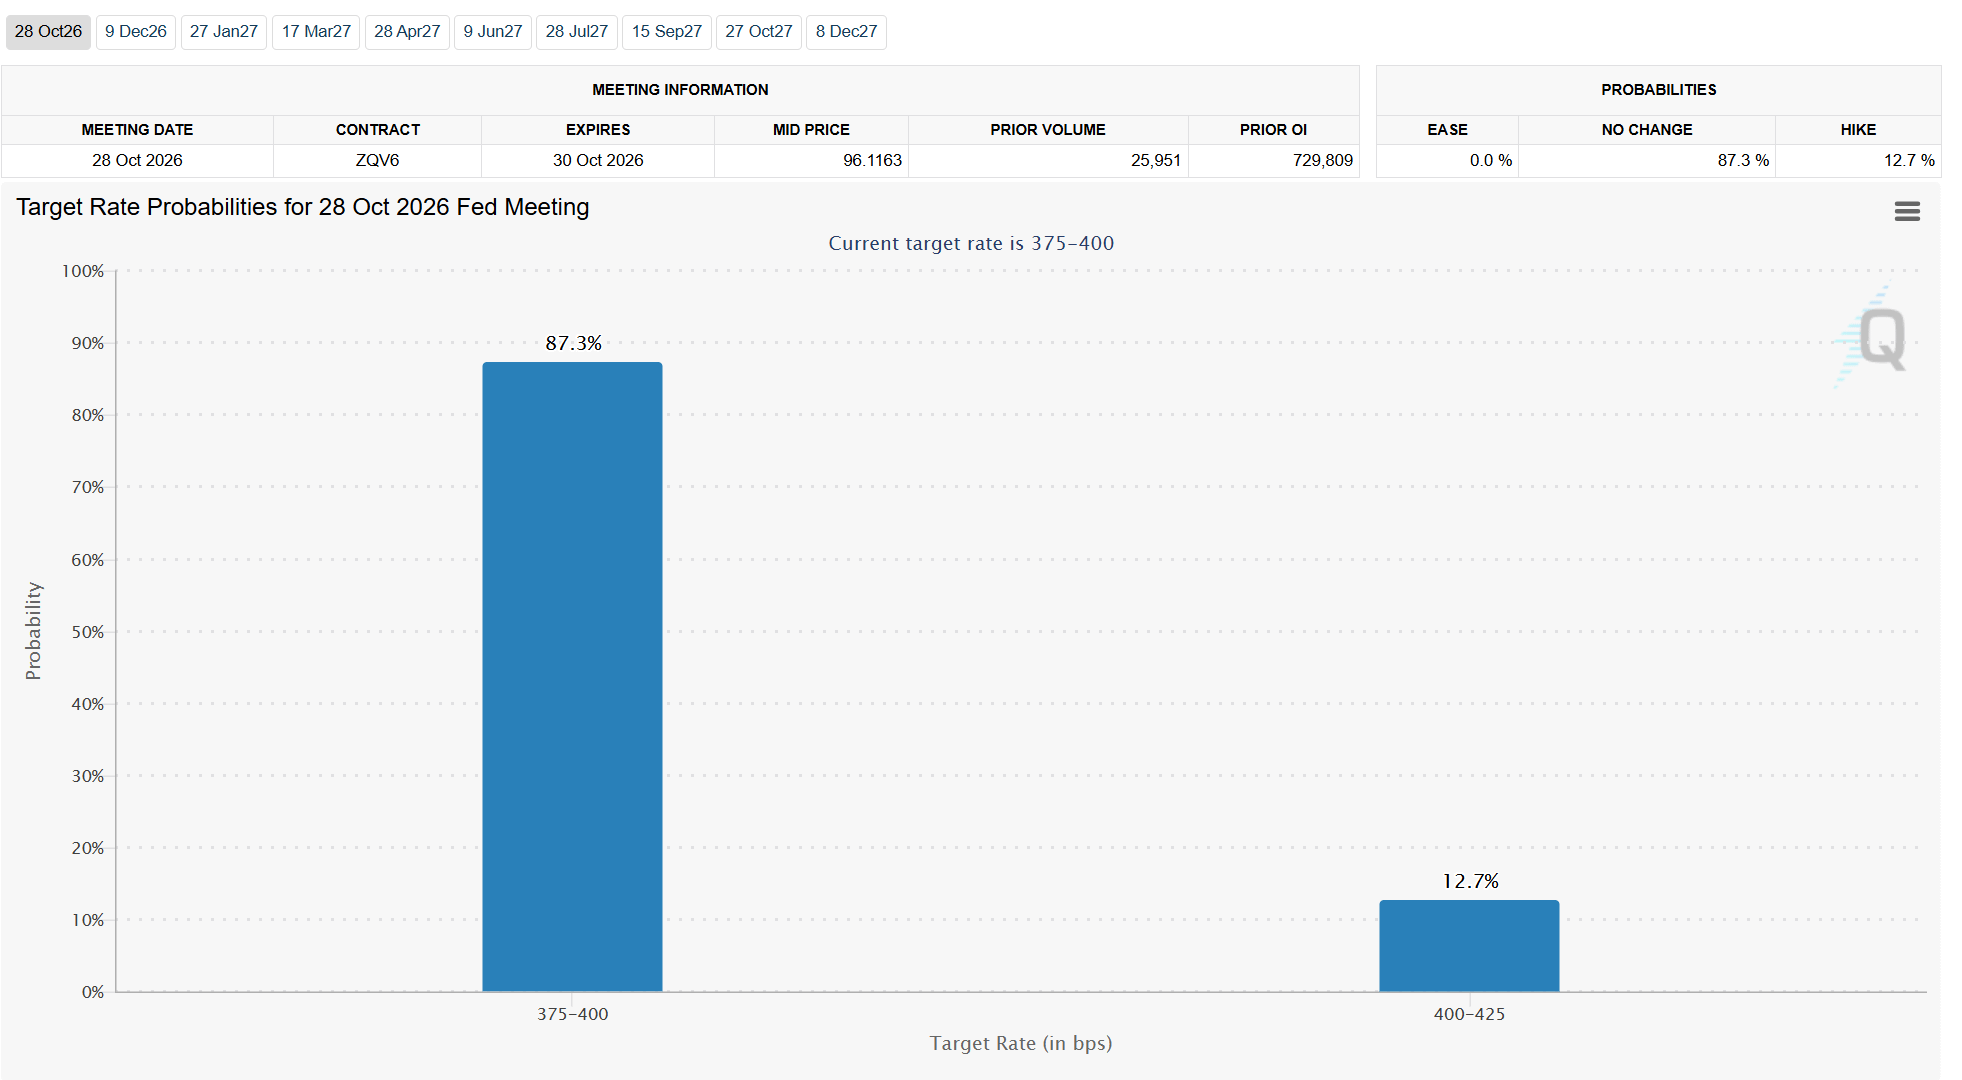
Right now - it’s about a 10% chance the Fed moves rate the week before midterms. I would say it’s closer to zero. The Fed isn’t that serious about the inflation fight - even with CPI being ~4% or so right now - which means 7-10% for the things consumers and businesses actually have to buy. China is also seeing pretty elevated producer inflation - and as long as we’re living in the ‘illusion of abundance’ with emergency fuel supply releases - they are keeping a lid on things in the short term, in terms of a 4.5+% CPI read, which remains possible in 2027 with current dynamics.
Weekly Oil and Gas Macro Note and Intro
If you missed the latest Weekly Oil & Gas Macro Note - we covered a lot, lot, lot of ground in there - beyond what we’ll discuss below in ‘Mentally Preparing for the Final ‘Super’ TACO’. With Nvidia being the flywheel now for the entire broader equity market - and at a very critical spot - we’re likely to see all levers pulled over the next 2 weeks in this pre mid-term window to keep sentiment on the rails. There’s apathy like we’ve never seen in markets - and people think these ‘heaven-like’ conditions are here to stay, and AI will simply take care of us and hand us money when we wake up in the morning. As nominal price level debasement continues at a speedy clip given its endorsement by the Administration in charge - we remain focused on the opportunities that are going to make us money through both of our portfolio strategies.
Find the latest below:

Nvidia Roulette - The Fate of the Broader Market
Let’s face the reality: Nvidia is the driving force behind the entire AI buildout and financial performance of said companies/equities. Jensen has turned himself into a celebrity-like figure - now doing tours and speeches daily - and any & every time we have a minor correction or dip he says things like ‘brush it off’, ‘don’t worry, be happy’, and ‘keep buying, because we’ve got you’. The entire thing continues to blow up so large - beyond anyone’s largest imagination (including mine, dating back to my late 2024 and even 2025 skepticism) that we’re going to be forced as taxpayers to save some of these firms from creating systemic risk that they will be creating.
Continue reading below with Ozone access…
