

Good Sunday evening MacroEdge Readers & Community,
It was a warm day in the Phoenix-area today and tomorrow & Tuesday I will be finishing our office setup this way that will serve as the new brain of our businesses. There are going to be a ton of positives to come out of this new hub, and I am excited to transition into planning mode over the next few weeks to prepare for a fruitful 2027. More on that mid-month, so stay tuned for the update.
This weekend was relatively quiet on all fronts - I expect that to remain the case while we head closer & closer to midterms that are now in just over a month. Current numbers show the in-party heading for a lot of trouble which will be a large driver of policy interventions and short term bandaids over the next month to paper over the problems that live under the surface. Bond yields have not spooked policymakers or Bessent enough to push for even larger buybacks or quasi-YCC policy, though I do think that is something that is likely in the next 12 months now. His admission this weekend that sometimes the ‘house’ as he referred to himself as about a month ago - sometimes loses - was notable. On the equity market front - given how reliant the consumer economy is now on stocks going up and to the right - that will continue to be the focus over the next few weeks. While a select few equities are doing the bulk of the lifting now, as has been the case for much of the year, it still looks like the data center engine is going to be losing steam through the 4th quarter and into 2027 from a raw driver standpoint. The buildout is essentially acting as the ‘growth engine’ - yet ironically - the long-term gains are unlikely to be anything significant in the current shape & form of ‘AI’... it will not be called ‘SI’ here for obvious reasons.
On energy prices and bond yields - these two things will continue to be the driving force now of both equity market performance and Fed action through the end of the year. While we can use complex and convoluted justifications to find reasons to call inflation ‘low and under control’ - private sector readings from things like the ISM Prices Paid are giving us a decent idea of where things stand from an inflation standpoint - especially on input costs:
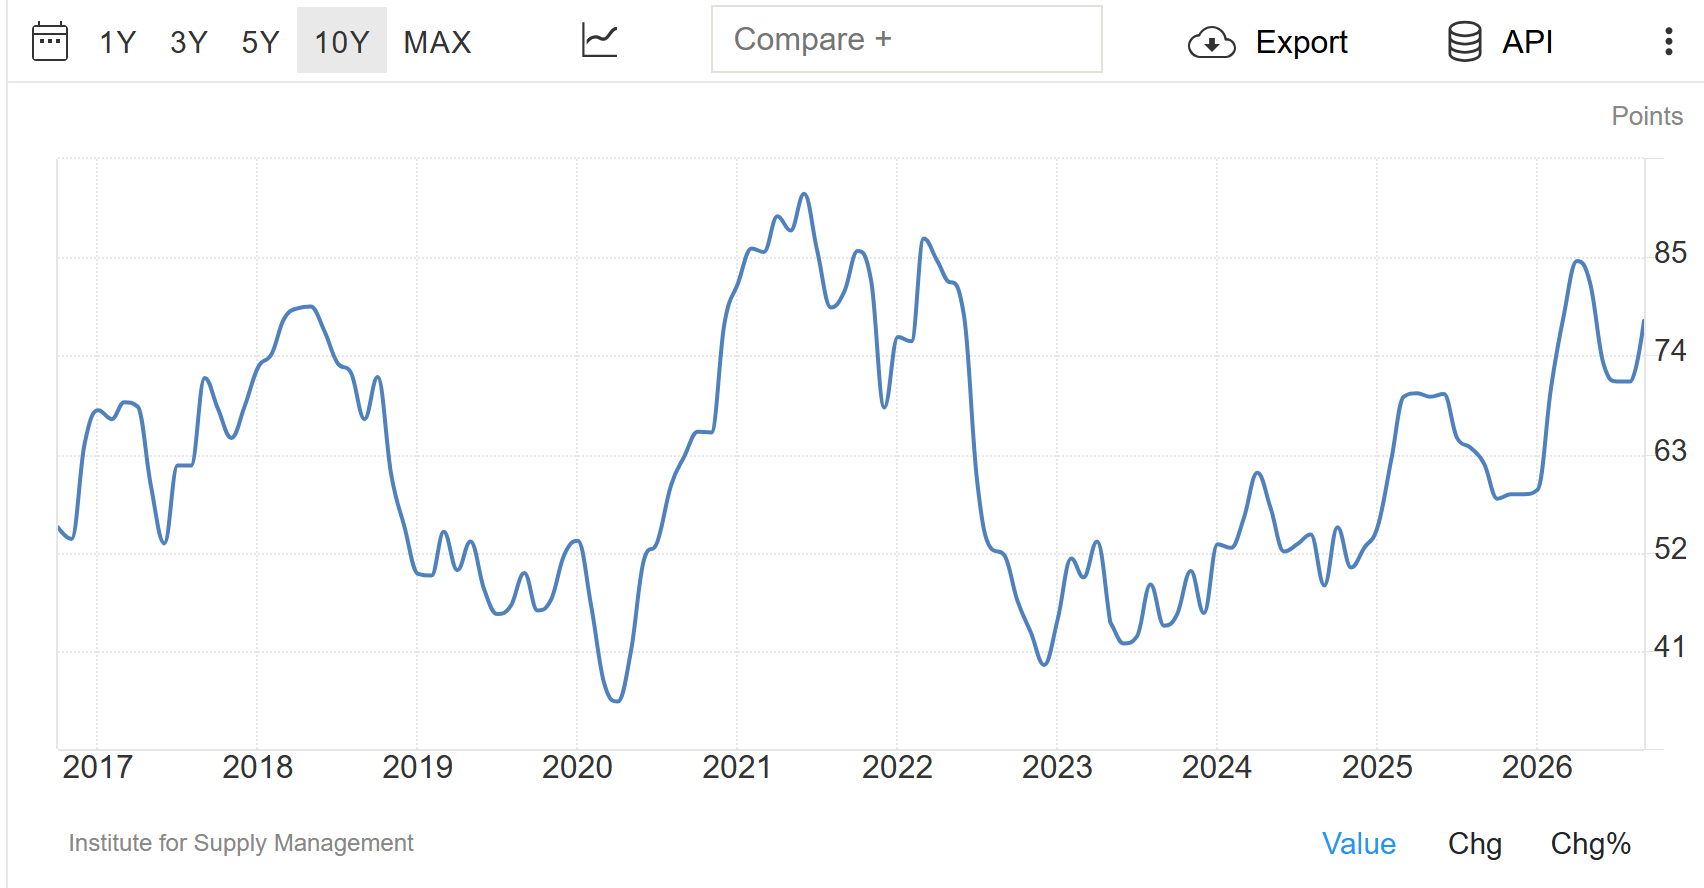
Again, I read economist after economist - especially in the PhD category - try and find every way to justify things like the Truflation numbers - and it’s straight up nonsense. This war (with an oil power) and war in general is extremely inflationary, and until the war dynamics change - WTI will continue to solidify a higher base in the $80-$82/bbl range.
Finding the signal through the noise this month is going to be especially difficult, which is why I’ve titled this Weekly Macro Note the ‘Do Not Disturb’ period, since I will be turning off my notifications on the headlines and subsequent noise on platforms like X. Based on how the last 2 weeks have gone - especially with claims that Hormuz flows are normalizing at pre-war levels, and with the fact that the US has withdrawn B-1 bombers from forward-UK deployments - it looks like there’s going to be a combination of escalation led by non-US countries in the region & particularly an escalation in the conflict between Saudi Arabia and Ansarallah in Yemen (Houthi forces).
This evening - we’ll cover the following:
Report Schedule for the Week
Macro Week Ahead
Midterm Noise and Signal - The Do Not Disturb Period
Yields & Oil - Living in the Driver’s Seat
Red Flags Ab’EU’ound
Have a great start to your week, and let’s make it a great one.
Don
Report Schedule for the Week
Tuesday: War Note / Update on Portfolio Strategy
Wednesday: (Ozone - Strategy Note and Portfolio Update - Six) (Oil and Gas Research - Strategy Note and Update, Part 3 of 3 - On the Ground from the Permian - Don)
Friday: Redeye Macro Note
Saturday: Oil and Gas Research - Weekly Macro Note
Not yet subscribed to MacroEdge Ozone? Upgrade below:
Macro Week Ahead
Relatively quiet earnings week this week - with Delta and Pepsi being the most notable - also a very light macro data week… That means that oil prices, yields, and war headlines will continue to serve an outsized role in market performance. The long bond crowd remains very loud, especially after that noisy employment report, and if we’re to have an 87-style event, that final ‘snap’ noise still needs to be heard under the surface - and hasn’t yet.
> Monday: ISM Services - watch the inflation print here
> Tuesday: US Trade Balance
> Wednesday: FOMC Minutes
> Thursday: n/a
> Friday: n/a
From a technical standpoint, as highlighted below, the next two weeks are very important for oil - especially front-month, as the back-end of the curve tightens up. Keep an eye on gasoil, ULSD, spreads, and gasoline prices as well - as large movements will likely be met with interventions in the next 4 weeks. On top of that, it’s likely that we start to see SPR releases re-accelerate under the final allocation under the March program, to the tune of 3-5mmb, with tomorrow landing about 3.5mmb.
Odds of a rate hold this month are now up to 80%, though we may see a second hike later in the year once we’re through the AI IPOs. The can is going to be kicked as long as possible on the AI IPOs, and they’ll need to secure their taxpayer bailouts before going public in US equity markets… (hence the many meetings with the White House in recent weeks). If you think I’ve got a third eye in saying this - please outline the long-term profit moat for any of these businesses which simply does not exist. Do we need to dive into data centers again, too?
Midterm Noise and Signal - The Do Not Disturb Period
We are in a completely bizarre world post-2020 in terms of the levels of propaganda that are so openly propagated across media channels (social media, traditional legacy media, non-traditional media like Substack, etc) - and this trend only seems to be accelerating. While I think a limited percentage of the population is actually able to see through this - I am not certain that it’s a majority, and I am reminded of that by events that have occurred over the last decade, many of which have raised my skepticism levels to higher levels.
With odds looking like this, the mandate for the GOP has simply shifted to damage control:
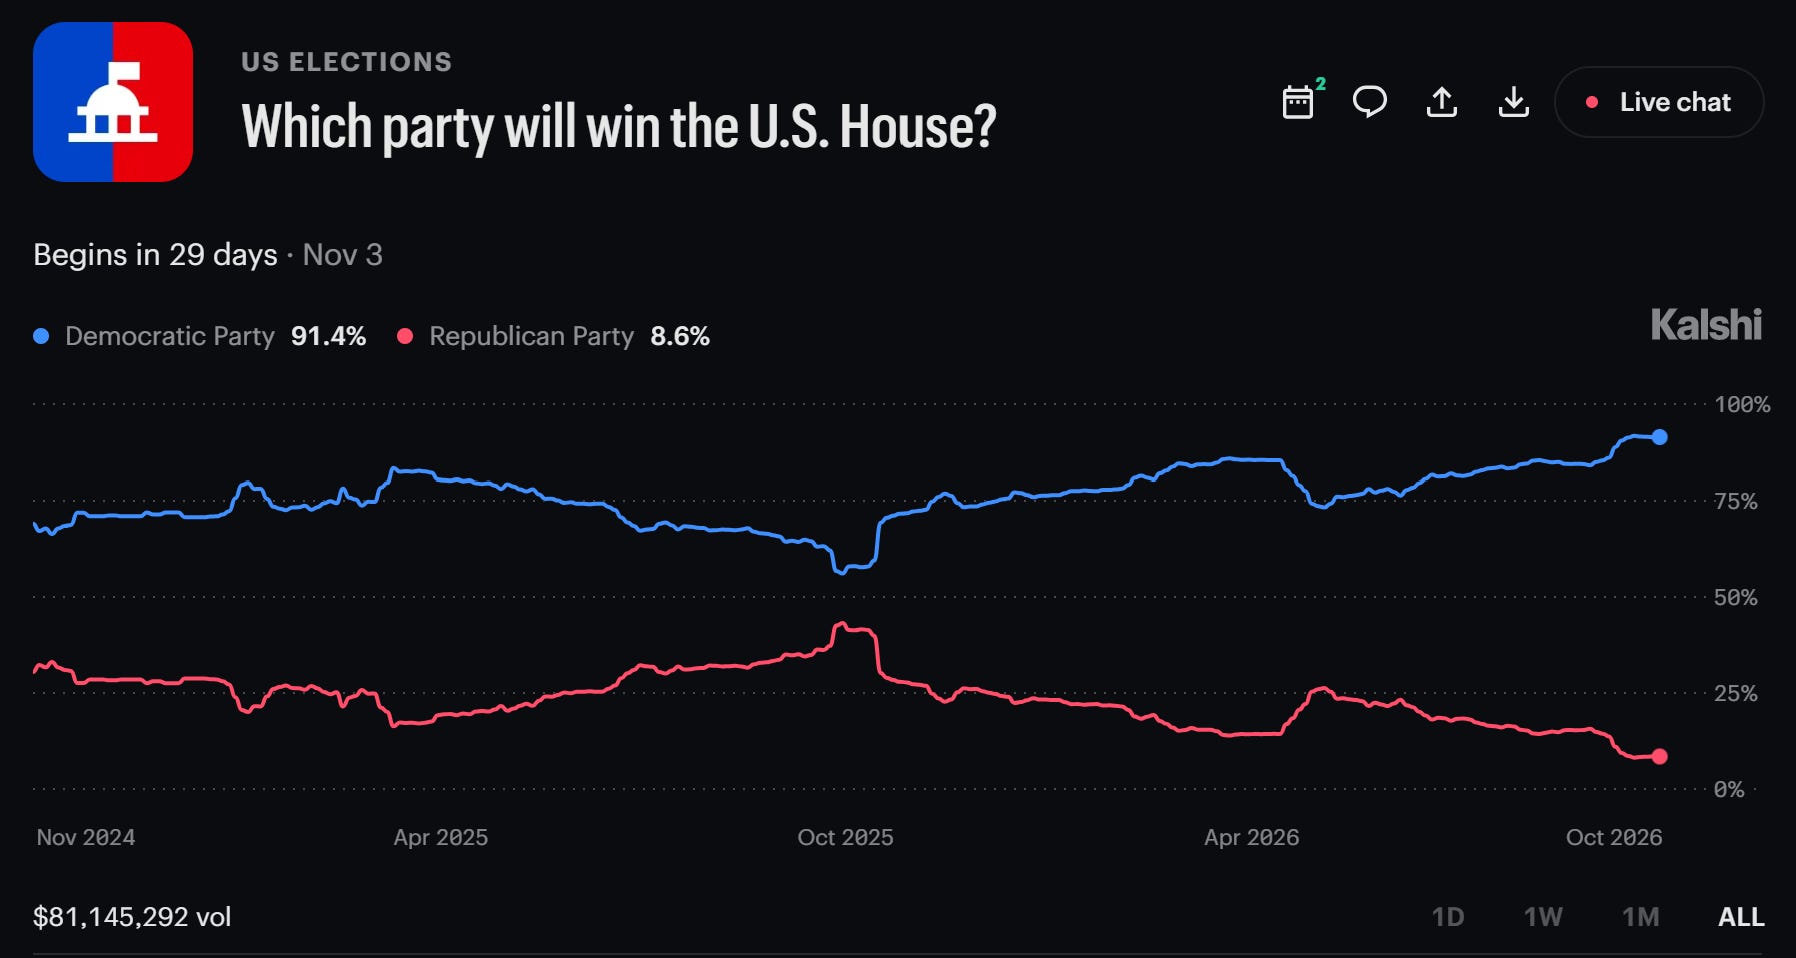
(Kalshi - House Odds)
This means over the course of the month - the obsession with front-month crude, fuel prices, inflation, etc. will only get louder - even though the narrative cannon will be on full blast about things like this being a ‘small price to pay’ etc. I am still quite confident that the Middle East situation - whether it be Saudi/Yemen, Israel/Iran, etc. escalates pretty significantly within the next 30-60 days. I also do not think Iran can afford to weather the blockade without more major political upheaval come December/January - though they are utilizing their proxies as a creative deflection and distraction right now to shift power balances in the region. The only way they will see the blockade lifted right now is through a major escalation, but we’ll have to see how that materializes in the next 60 days.
With that being said, this period is going to be very, very noisy, and I don’t want to spend too much time overanalyzing noise.
Yields & Oil - Living in the Driver’s Seat