

Good Sunday evening, MacroEdge Readers & Community,
It’s fantastic to be back with you from New York City for another Weekly Macro Note this Sunday evening. We’ve made it to November, and it’s hard to believe I’m saying that… It’s also hard to believe we’ve turned the clocks back and the sun is now setting in the 5pm hour as we head into another winter season (which I’m always grateful for). We’re in one of the most dynamic macro periods we’ve seen in years, particularly since the 2021-2022 inflation era, and that means there are about 100 different things to keep an eye on right now. As we sit at the most important energy price levels of the cycle, the Trump Administration will have to decide whether it’s comfortable with much higher prices than current levels. Meanwhile, we continue to draw down inventories on a global basis, and the situation will only tighten into winter, something that’s already been priced in on the TTF front.
Given all of these crosscurrents, de-risking into year-end is something I’m strongly considering, especially on the energy front, as we wait to see what happens next with the war. All signs point toward a resumption of the conflict, though it may take another 2-3 months or so for the next leg of reality and tightening to price itself in.
It’s going to be another very interesting week ahead. Overnight, technology is leading the gains, Asia is rallying back, Chinese officials are meeting for yet another emergency stock market intervention, and oil is down about 3% as governments make their final intervention moves before a potential conflict resumption in the next few days. On the midterms front, which we discuss in more depth below, Texas is really the state to watch for what I suspect is the beginning of a long-term GOP decline this cycle. This structural shift likely kicks off a more Canadian-style evolution in American politics, where the right shifts more and more left over time, though a lot of that will land on the shoulders of Gen Z and Gen Alpha… The funny thing about spending time in places like New York City is how clearly you realize just how severe our affordability problem is becoming in the United States. From hotels to food to rent, I suspect this only reinforces the above, and it also enables the Silicon Valley class to pursue its UBI/control goals over broad swaths of the population, goals that really kicked into overdrive from the pandemic period to the present. That segues into updating our ‘Powell’s Valhalla’ framework, which will get its own dedicated report on Thursday evening, with the intro this evening.
What was Powell’s Valhalla? It’s a term and framework I’ve used since 2023 to describe a new period of relentless financialization and ‘casinoification’ of everything in US markets. After the 2022 ‘baby bear,’ Powell in early 2023 only reinforced what had been in motion since the post-GFC intervention programs: a permanent reinforcement of ‘i-shaped’ economic dynamics, backed by Fed firepower. 2020 made that worse, and the 2023 SVB bailouts sealed the deal. From 2023 to the present, every single sign of market trouble has been saved or intervened in, and fiscal and monetary forces now work together in near unison as a greater and greater percentage of US economic activity becomes tethered to financial markets. The AI and data center bubble is just another example of this, and one of many examples of our pursuit of nominal growth above all else, something this Administration has highlighted and celebrated over the last 2 years. Where is Powell’s Valhalla headed? Over a long enough timeframe, likely on the same course. But in the short to medium term, I think we’re seeing signs that things are changing before our eyes, and we’ll discuss that below.
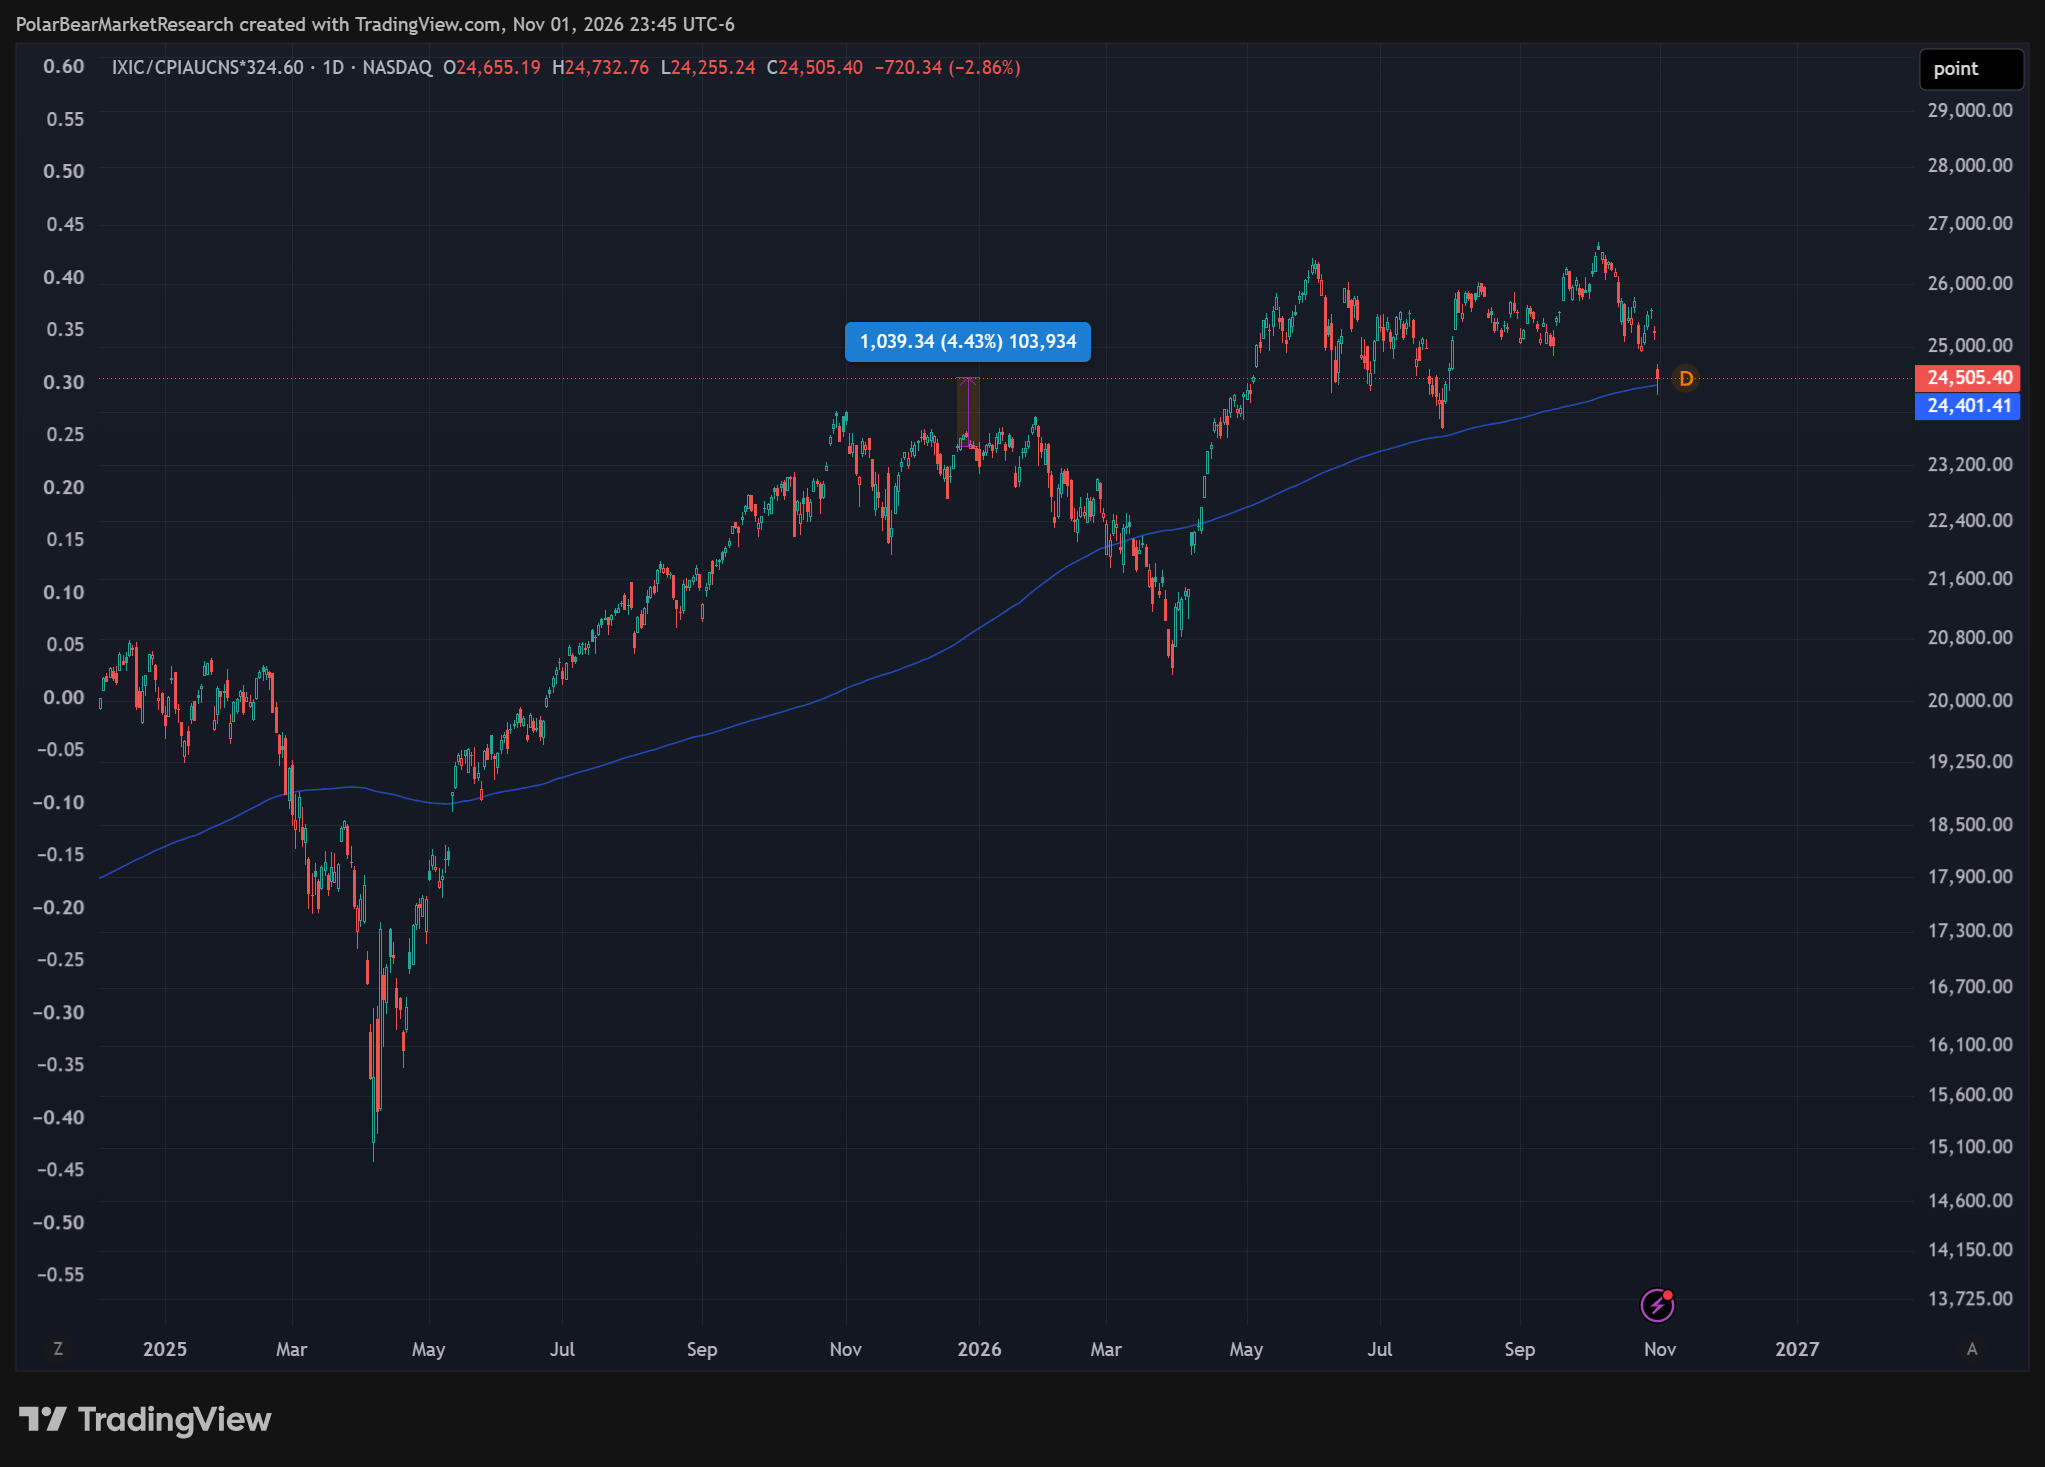
One final key takeaway from every Trump Administration-related dip we’ve seen in the last few years is this: you are in fact in a casino, and the House sets the rules. So don’t get married to a narrative. I suspect we’re going to ‘plateau surf’ on the equity index front for several months now. Keep in mind that on an inflation-adjusted basis, we’re up just 4.5% or so on the year, excluding whatever move happens tomorrow:
Not yet a MacroEdge Ozone subscriber? Upgrade below and don’t miss a beat with our portfolio strategy, commentary, reports, and much more below:
Macro Week Ahead & Report Schedule
The primary focus this week will be on Tuesday’s midterm results in the United States and on analyzing any subsequent military response or attack between the US and Iran. Right now we’re teetering once again. Iran’s economy has until mid-to-late December before I suspect it’s forced to blink, though I strongly suspect the Trump Administration will blink first if Tuesday goes as projected. The gridlocked environment in DC means nothing gets done for the next 2 years, and endless investigations and impeachments are about to ramp up. But the war is what matters next, alongside the technology and AI sector, which is enjoying its plateau period. So, outside of energy and the bond market, we’ve got tech and AI, which I suspect will stick to the current range for at least several more weeks, and the war (which is tied to the first two items). The US proved earlier in the year that it can’t wage an effective war with debt at an uncomfortable interest payment level, and there will likely be very few changes to the fiscal structure in the next couple of years, until any chance of a corporate tax increase comes around in 2028.
Here’s the report schedule for the week:
Tuesday: War Note and Election Digest
Wednesday: Strategy Note (Ozone) and Strategy Note (Oil and Gas Research)
Thursday: Updating Powell’s Valhalla and Broad Macro Discussion
Friday: Redeye Macro Note - the MacroEdge Global Macro Market Toolkit
Saturday: Oil and Gas Macro Note
The important macro events this week (in the US):
ISM data: Monday and Wednesday
Midterm elections: Tuesday. Most results should be available by Tuesday evening, especially for the races that matter in the so-called ‘swing states.’
October employment situation report: Friday
UMich sentiment: Friday
Earnings over $300bn market cap:
Monday: AAPL, PLTR
Wednesday: NVO, QCOM
Apple has remained the untouched giant over the last few months, continuing to make new highs as a flight to safety from the AI capex drag, so it will be very interesting to see whether it keeps tracking that trend after this report. If Apple’s trend stops, it could introduce much greater vulnerabilities to the broader technology structure going into 2027, especially with Nvidia now living below its support trendline (dual lines)...
Updating our ‘Powell’s Valhalla’ Framework - What Dead Money Looks Like
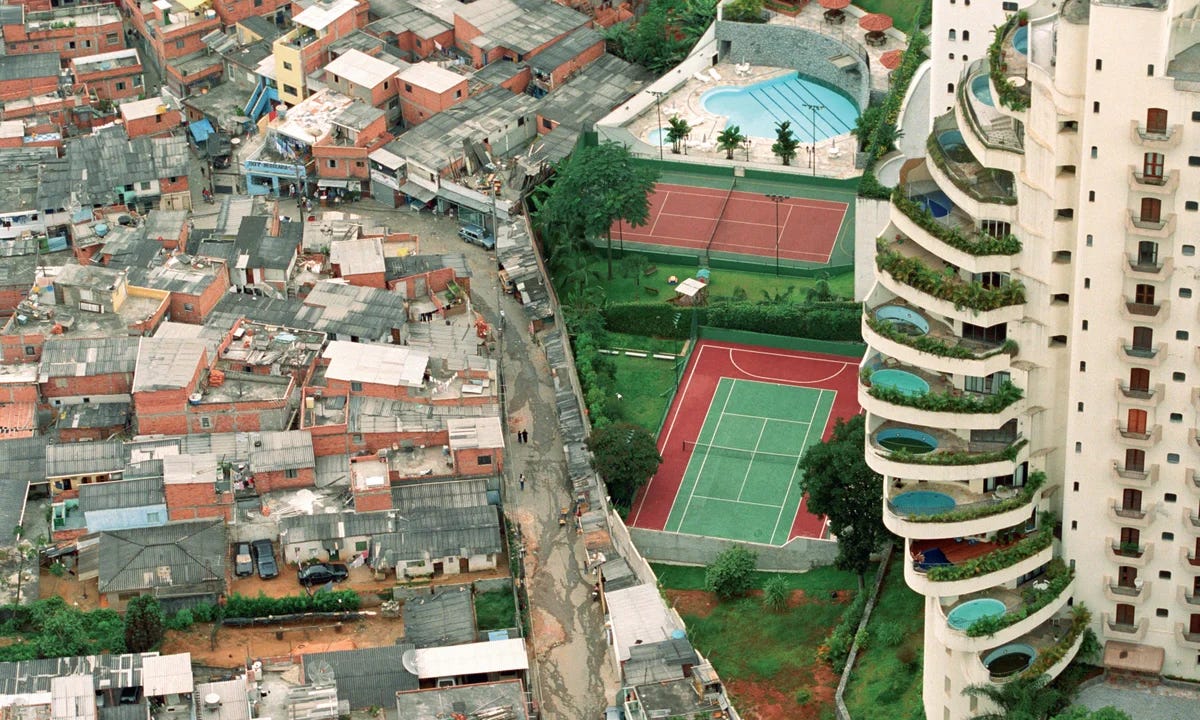
On Thursday evening, I’ll have a more in-depth and comprehensive update to our ‘Powell’s Valhalla’ framework, covering the various components of the terminology I used back in 2023 to describe the entire economic and financial landscape on a broad basis.
Continue reading by subscribing to Ozone below:
