

Good Sunday evening MacroEdge Readers & Community,
I’ve had a day of travel - with two flight cancellations en route to my destination and plenty of excitement in between with dust storms in Phoenix… It’s great to be back at the desk and set up for a great week ahead. Tomorrow is a ‘technical’ holiday for banks and the federal government - but equity and commodity markets will be open. Tuesday evening in the ‘War Note’ we’ll start to go over things that will be changing in the 4th quarter - and particularly in 2027 as we complete some changes here as an organization.
Tomorrow is going to be a very light volume day with the holiday and futures haven’t done a whole lot in the overnight session. In Korea - the KOSPI continues to look like a dumpster fire, and I am not sure that there is much to be excited about across the entire semiconductor space as investors will be forced to ‘re-discover’ that it’s much more commodity-like than anyone would like to admit right now.
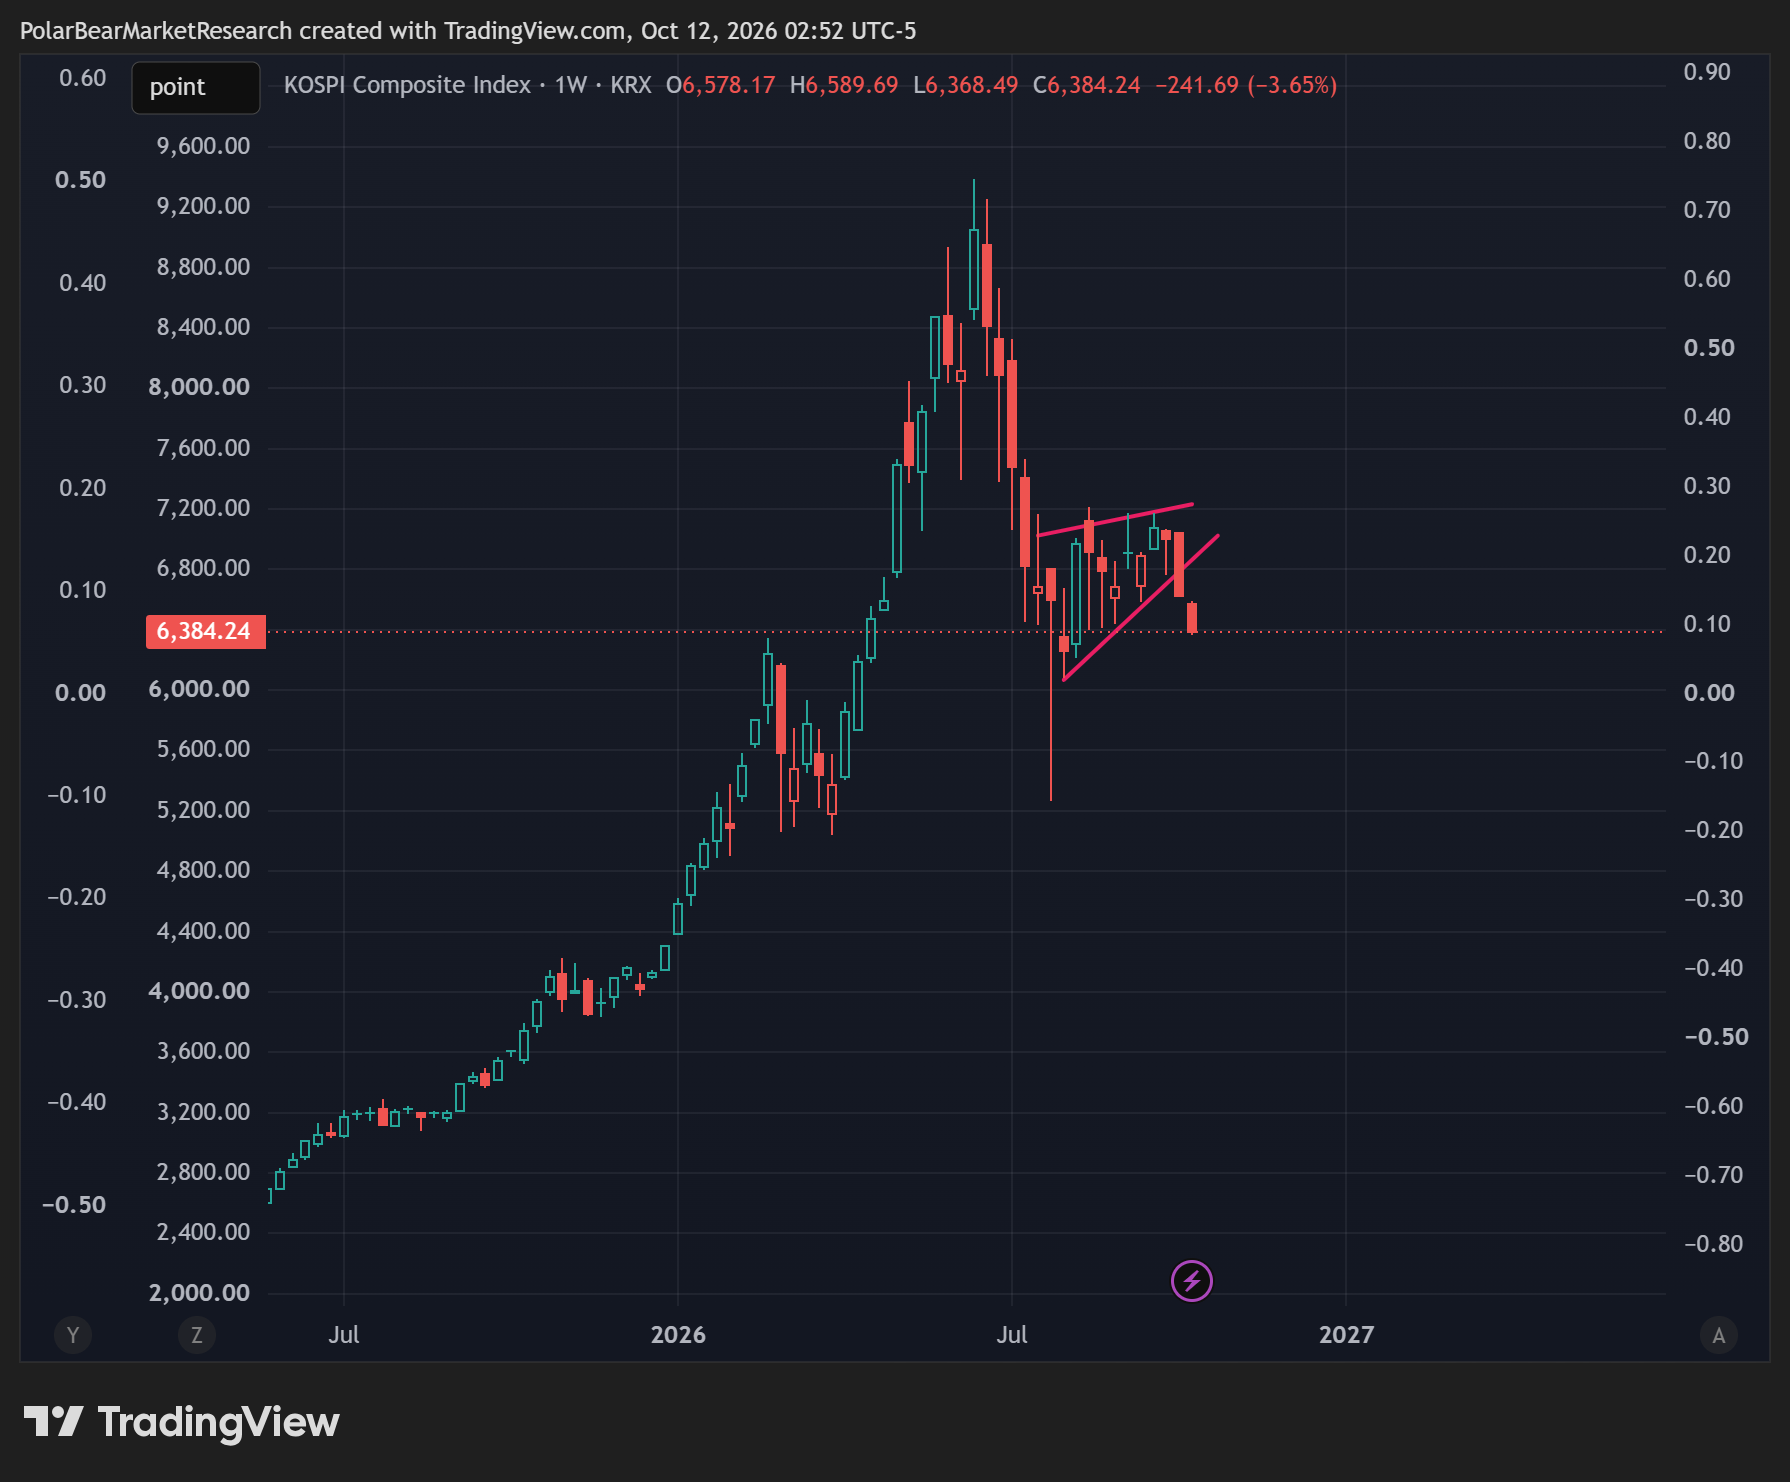
While domestically, we have a much broader backing and support for backstopping the entire AI-ecosystem right now - especially as it pertains to data center construction - I think the charade will start to see an unwind either this quarter or next as construction signals start to flash warning signs. While political opposition alone hasn’t been enough to move the needle on data centers, I do expect that we see an uptick in the environmental opposition and more difficulties in financing the additional buildout as we start to see demand wobble.
Let me be clear that there is no profit moat for just about every single business in the space right now - and mislabelling LLMs as some sort of Manhattan Project is simply bizarre. There are some fundamental questions we need to ask ourselves before committing to a backstop of any of these organizations - many of whom are run by deeply questionable actors… This discussion is one for a different day and time, but even though the cycle itself has been dragged on by relentless backstopping and just off the charts levels of delusion, all of the points still stand.
From a market standpoint - oil and bonds are likely to continue to drive market action and direction for the remainder of the year. With ‘patience through October’ fully in motion - I am increasingly confident in our patience narrative - and the bulk of our research focus will come from MacroEdge Oil and Gas Research between now and the end of November. With emergency reserves draining and quite literally zero plan to stem the bleeding - other than by way of begging other global leaders to sacrifice their own supplies - this energy cycle is likely to fundamentally and permanently change things, including from a price standpoint. The general consensus on X and elsewhere is that it’s time to short bonds - and the labor market is fantastic according to macro pundits… While the signals are undoubtedly noisy, I do not think that they’re overly noisy - and from an oil and gas perspective, strongly encourage our patience through October narrative right now. On Friday - we’ll discuss two new opportunities in the pipeline from a private market standpoint, and there’s a lot coming this week, as highlighted below.
Let’s make it a great week - and whether or not you will be enjoying a day off tomorrow - I hope you’re staying sharp as we head further into Fall.
Report Schedule for the Week
Tuesday: War Note & Updates
Wednesday: Strategy Note - Oil and Gas Research, Strategy Note - Ozone
Thursday: Enhancing our Vision with 2030 in Mind: Improvements, Changes, and a Place to Connect in December
Friday - Redeye Macro Note: Unlocking Oil and Gas Opportunities with LX & TREX
Saturday - Oil and Gas Research
Macro Week Ahead
Another relatively quiet week, with the exception of CPI. Prices paid from an input standpoint rose again in September - so we’ll see if this reflects in CPI - it should be in the non ex-energy basket, though it will likely not be enough for the Fed to move on another hike, yet.
Just continue to watch oil prices, the curve, refined products, and bond yields - the rest is sort of going to follow at this point as everything is marching in a relatively close correlation.
Monday: Bond Market Closed - Columbus Day
Tuesday: Existing Home Sales
Wednesday: Consumer Price Index (September)
Thursday: Producer Price Index
Friday: Industrial Production & Regional Manufacturing Surveys
Peak Apathy is Here
We’re reaching cycle high levels of apathy across the board. From tech to everything else - there is very little care or belief that there is any material downside case to this federalized market we’re witnessing.
