

Good Sunday evening MacroEdge Readers & Community,
This evening I am writing to you from Midland, TX. This has been a fantastic start to the nearly 3.5 month journey ahead of me - and there are plenty of takeaways to share thus far that I will begin writing about tomorrow in a rolling ‘On the Ground Notes’ series over the course of the next week. With how busy the last few days have become - the Oil and Gas Strategy Notes will be resuming next week on Saturday evening - but our ‘On the Ground’ notes will be published through Oil and Gas Research directly. You can subscribe to that below:
In terms of updates to our entire ecosystem - changes are well underway that were highlighted a few weeks ago, and these will be announced over the next several weeks as developments are finalized. Stay tuned for one or two full announcements/updates on the matter during this period of time.
As for the overnight market action - equities are up a blip and oil is off about a point as of the time of this writing (2:08am). I expect that with how bleak the midterms look, and with potential pending global G7 SPR action (+EU diesel action) this could be yet another can kick for oil inventories very briefly, but I do not think that it is sustained for any period of time. The theme that I am calling this as it pertains to the oil and gas trade(s) is the ‘patience through October’ theme, which remains in force as global inventories continue to run down with little sign of improvement in the months ahead. I expect that we will likely start to see a louder and more noticeable resumption of TACO headlines in the next few weeks due to midterms, and that is going to impact oil and gas equities, and coupled with an SPR release, be enough to briefly keep a lid on things. While the war did not flare up over the weekend, that could happen at any moment, and Iran/the IRGC may be waiting for the most opportune time to strike energy infrastructure pre-midterms so that people notice what’s going on and the in-party gets harmed significantly as a result. We’re getting quite close to being at the point where growth concerns come back into play - especially as aggregate data center construction slows - and the likely outcome will be the same as the last several years - just inflate and cover our eyes until no tomorrow.
This evening is going to be a brief kickstart to the week - and we’ll review the report schedule for the week, talk about the macro week ahead, look to ‘mind the gap’ that is currently the upside target for a fill in tech/high-beta equities, discuss what the truckers and builders are telling us, and wrap up with the crude and natgas start to the week.
Let’s dive in.
Report Schedule for the Week
Monday - On the Ground Notes from the Permian Pt. 1
Tuesday - War Note
Wednesday - Oil and Gas Strategy Note + On the Ground Notes from the Permian Pt. 2
Thursday - Midweek Macro Note
Saturday - Oil and Gas Macro Note
Macro Week Ahead
This is a relatively light week as planned - Trump is scheduled to meet with Xi (which could actually be a catalyst for massive equity market action if it is coupled with loosening China/AI regs - but we will cross that bridge when we get there). Lots of Fedspeak as well which is noise in this era, and Costco is the notable company reporting this week.
Minding the Gap
In terms of equities - this action was completely to be expected as of about 14 days ago when the gap emerged at about the green bar level on the chart.
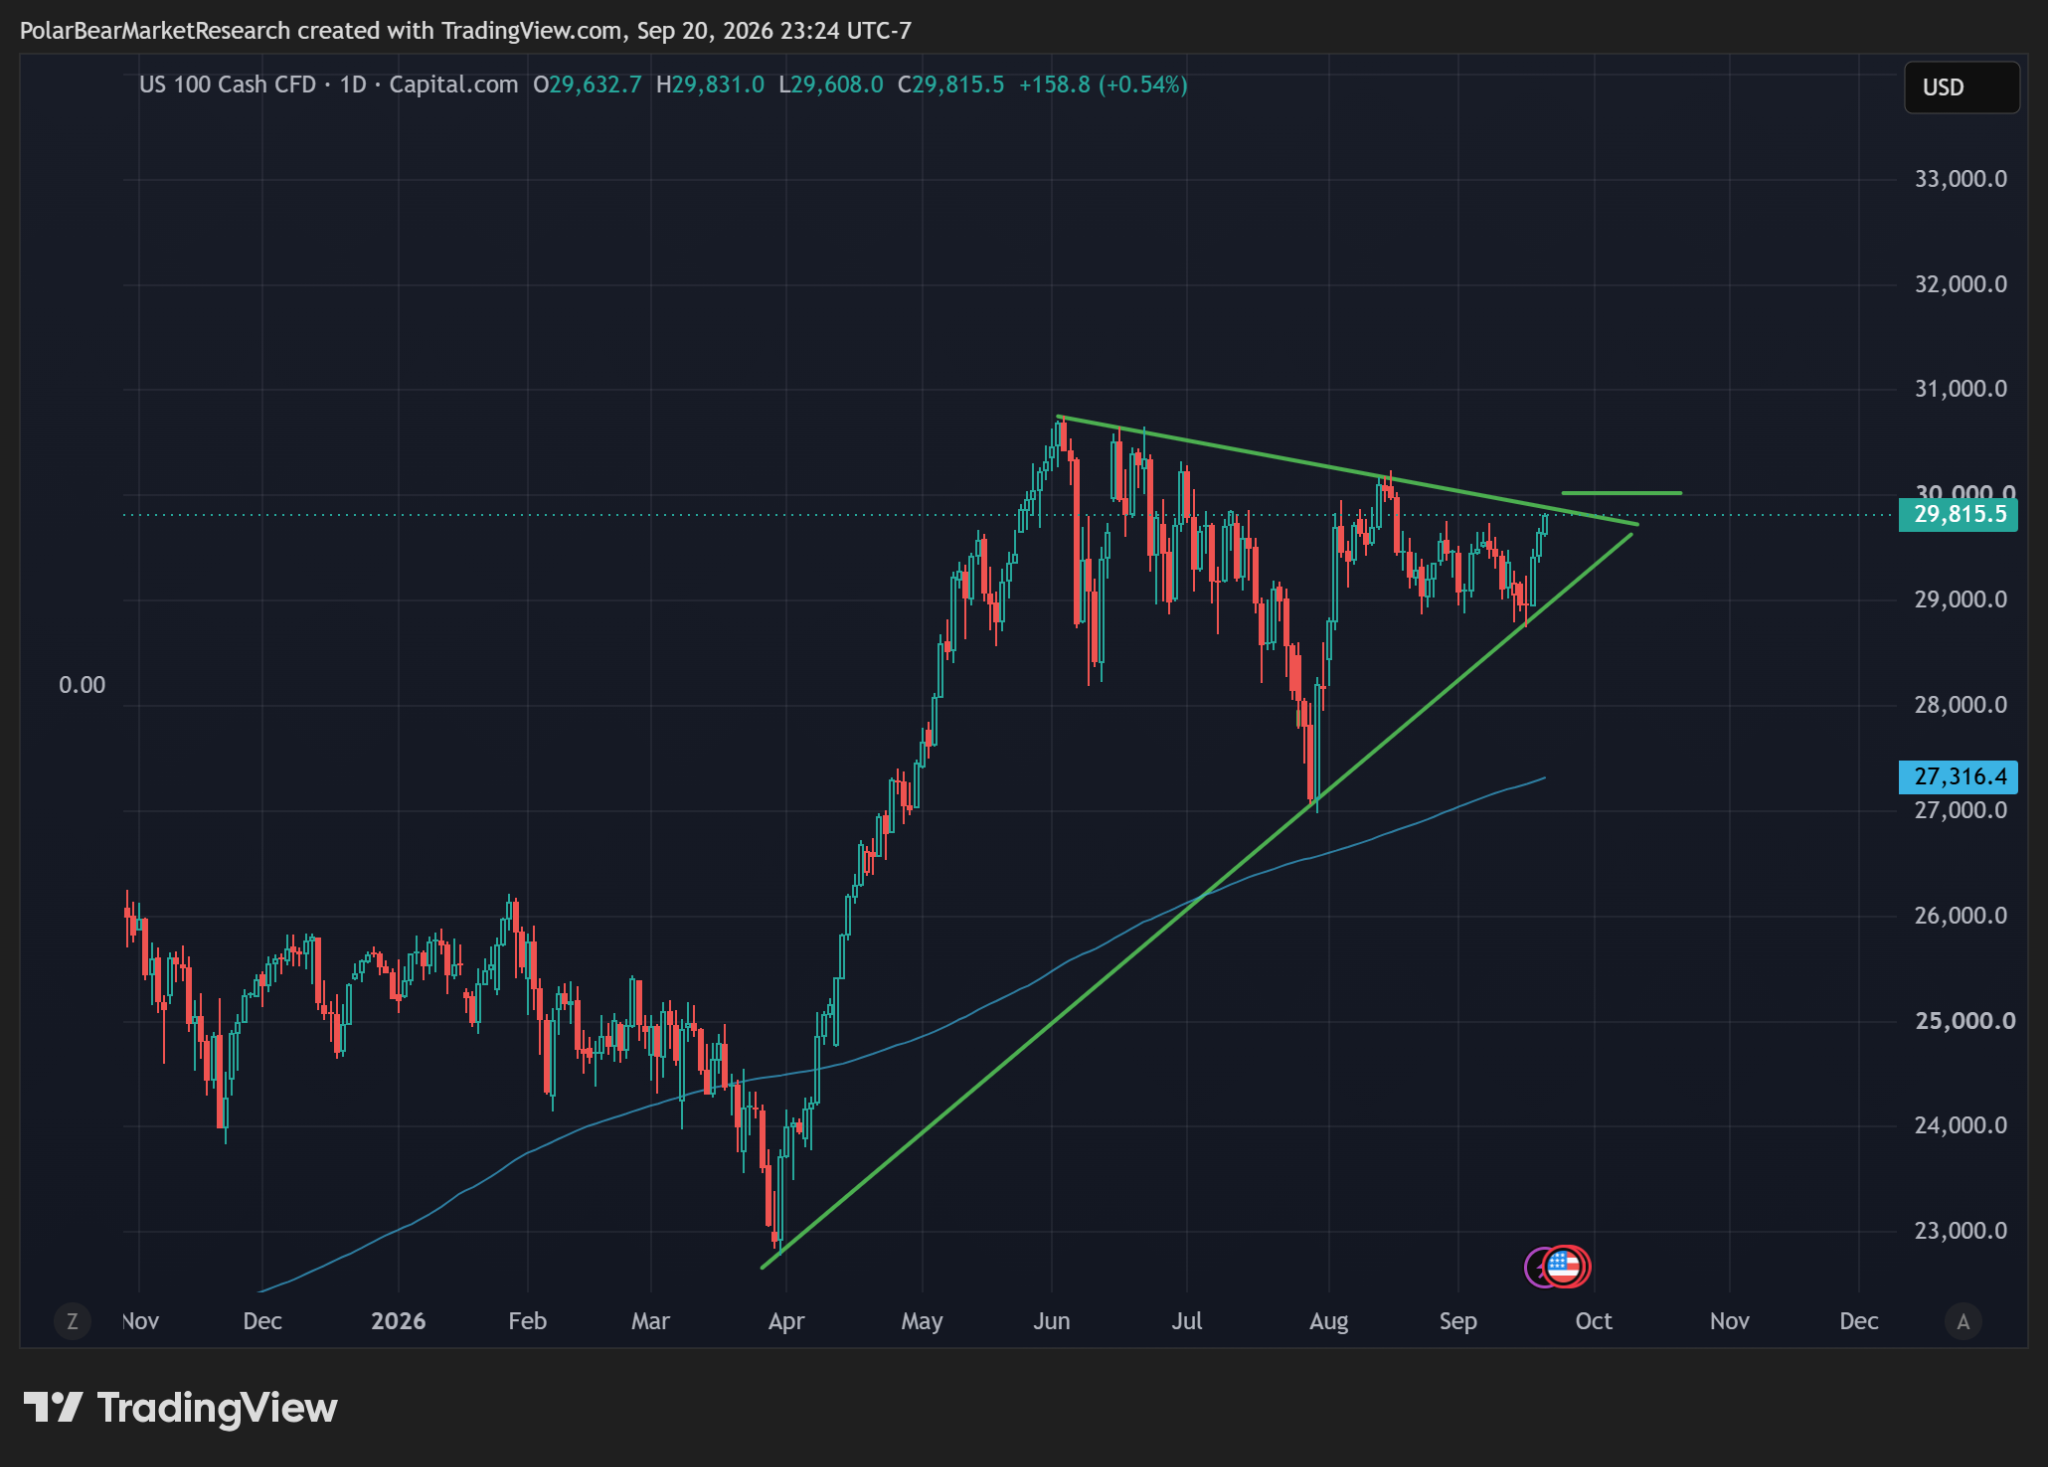
The structure of this setup is about to break hard one way or the other soon - but it does look like a resolution will come before the end of October.
