

Good Sunday evening, MacroEdge Readers & Community,
We’re halfway through November, and this time of year always seems to accelerate as we approach year-end and the holiday season. It really is a great time of year all around, and with each passing trading day, we get better clarity on what 2027 might look like. In last night’s Redeye Macro Note, we talked extensively about whether Powell’s Valhalla will actually be broken under the new Warsh Fed. That was the 2020-2026 dynamic (really more 2023-2026), in which a relentlessly activist Fed intervened at any and every sign of even minor pain on the horizon, particularly for equities, to keep the music playing under that macro regime. The major question as we analyze this new monetary regime is whether it actually has what it takes to break that pattern and take the inflation fight more seriously. The sample size is far too limited right now, but with 3 potential hikes between now and March of next year, the real tell will be the actual rate decisions, along with the more granular decisions made within the modernized Fed policy toolkit.
In the last few days, I’ve started to notice growing internal strife among Trump Administration officials, particularly over the Nvidia leadership issue, and the widening rift between Bessent and Lutnick hasn’t gone unnoticed. I suspect one of them may depart soon, more likely Lutnick, taking the cash he made under the Administration with him. Bessent has started taking larger aim at the Nvidia structure and has even alluded to looking into it further. That’s (obviously) something I think should happen, though I’m not sure the same people in bed with the AI executives are the right ones for the job. This week is going to be unlike most weeks of the 2023-2026 ‘Powell’s Valhalla’ regime, with the ANT IPO and major earnings from the companies that quite literally drove, funded, and enabled the AI bubble and boom. As I cautioned last night, it’s still very prudent to take things one day at a time, given how important the stock market is to both this Administration and the entire system we’ve re-crafted since 2008.
This week is arguably going to be the loudest of the cycle. We’ve got the ANT IPO on Thursday; Nvidia earnings, with the company expected to announce that speculative investments may be cut (Jenron, come back!); the banking sector’s desire to protect the ANT IPO; and some general anger in the up-and-to-the-right momentum crowd that bought the top in early summer. I remain relatively constrained on targeting our headline indices until we take out lower support, but flopping around below the 200dma will probably not look like an ideal development for bulls in hindsight. On top of that, I’m not certain either side has a political incentive to actually stop downside momentum from accelerating in equity markets, with the President now explicitly blaming Democrats. With Trump, we always know there’s a ‘put’ at some point, though I suspect we’re nowhere close to it right now. If we can finally break the 2023-present Powell-era pattern of bouncing and catapulting higher off the 200, with a President and cabinet that support those PPT actions, we can begin the broader transition into the ‘revenge of the old economy’ trade, which has the potential to last a lot longer than a few quarters.
In Japan this evening, we saw the first economic contraction in over a year. China painted a mixed picture, and its data remains highly questionable, particularly given the government’s need to bail out equity markets again (and its preparations to do so).
In the US, I suspect the bond market and oil prices will continue to play a major role in equity performance in the months to come, as we battle through this transition phase to test whether we can break away from the AI-beta bubble that propelled markets higher for the better part of 2 years. If that’s the case, a lot of consensus narratives are going to come under fire. This week, we’ll spend time diving into particular topics and signals that will help us keep monitoring and preparing for opportunities in what I perceive to be a late-cycle environment, even though these are often the most challenging environments to hold conviction and execute in.
Once again, thank you all for your patience as we finalize our new office and hub setup here in Arizona tomorrow and Tuesday. From there, we’ll continue without any meaningful disruption for the foreseeable future, and I’m excited to see our new operational plan kick into overdrive.
Not yet a MacroEdge Ozone subscriber? Upgrade below to get all of our research, portfolio strategy, commentary, and more - below:
Report Schedule for the Week
We’re ramping back up to full throttle on the report schedule this week, particularly once our new setup is finalized and ready to go on Tuesday. This new environment will provide a fresh foundation for everything: our reports, advisory work, new business units, our oil and gas business, and more.
Tuesday: War Note & Technicals
Wednesday: Oil and Gas Research Strategy Note; Portfolio Strategy Note (Ozone)
Thursday: Recapping a Busy Macro Day
Friday: Redeye Macro Note: Updating Our Asia Chart Deck
Saturday: What’s Ahead for 2027 (New Report Cadence and Schedule, New Contributors, Don’s Notebook, and Our Offerings); Oil and Gas Research Weekly Macro Note
Sunday: Weekly Macro Note
Macro Week Ahead
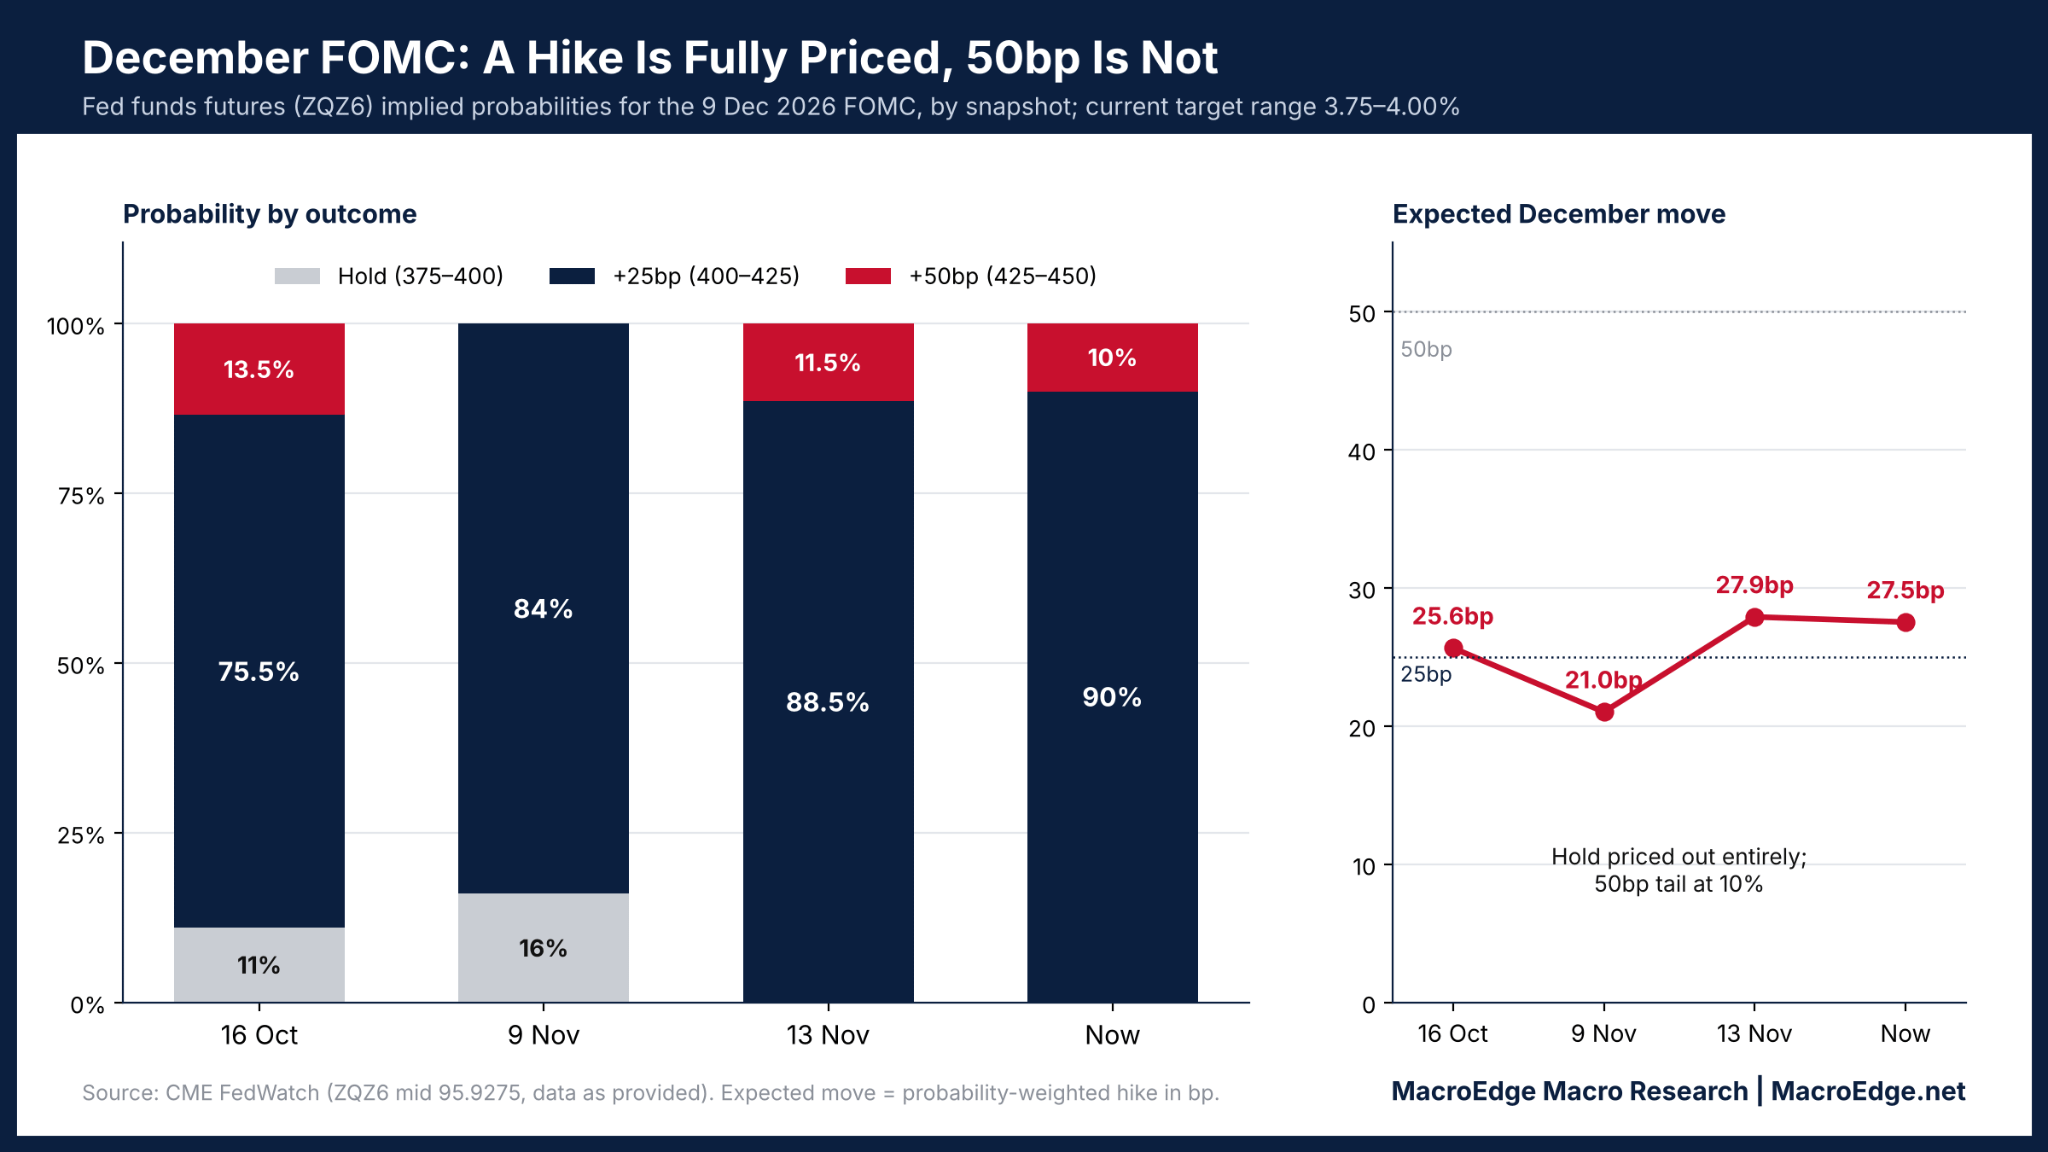
This week, there’s a lot going on across the macrosphere. We’ll have a deluge of Fed speakers, and I suspect they’ll keep giving the market ample warning that a rate hike is coming in December. I suspect the hawks will also leave plenty of optionality open for a 50bp hike. One thing I’ll be ignoring this week, particularly in our reports, is the ‘normie’ investor crowd’s obsession with Nvidia. The tabloid-like coverage has very little bearing on many of our core macro focus areas, and the company has major problems ahead, especially if a leadership battle is coming.
The bond market and commodity price action, particularly in oil and gas, will continue to drive much of our focus for the remainder of the year. Beyond that, we’ve got the December FOMC meeting, price action in the high-beta trade that remains critical for the entire data center construction cycle (which I suspect peaks in Q1), and much more on our plate this week.
Here’s what’s on deck this week:
Monday: NY Empire State data, Fed speakers
Tuesday: Retail sales, manufacturing data, import/export prices, NAHB data
Wednesday: Housing starts and permits, pending home sales, FOMC minutes
Thursday: Philly Fed data, Anthropic IPO (scheduled)
Friday: UMich consumer sentiment
Earnings this week over $300bn market cap:
Home Depot
Nvidia
Walmart
December FOMC - The Main Focus After the Busy Week
The December FOMC will be the main ‘macro’ event for the remainder of the year, and I suspect we will see little shift in the rate hike pricing for the meeting now. With all of the Fed speakers this week, we are likely to see Fed speakers begin shifting market pricing in the hike even further - particularly in that 50bp column.
Keep a close watch on any other signals from the BOJ, as well.
The Strait Truth
As covered last night in the Weekly Oil and Gas Research Macro Note - Hormuz flows have begun declining sharply over the past week. With the next SPR release figure coming tomorrow - this environment and backdrop continues to support our $80-82bbl base outlook for WTI right now.
