

Good Sunday evening, MacroEdge Readers & Community,
Distraction here, outrage item there, and ‘look over there’!
We’re just about off to the races for another week. What an exciting time it is right now for macro all around the world, and there are so many different components of our complex global puzzle moving around. This weekend, we saw some bizarre tweets and posts from Elon on ‘neoclouds,’ as well as his thoughts on the data center landscape. What we’re starting to see is a cycle shift before our eyes… When someone with a platform as large as Elon’s begins to bring lesser-known realities into the public eye, some of which we’ve been discussing for over a year now, it’s very meaningful.
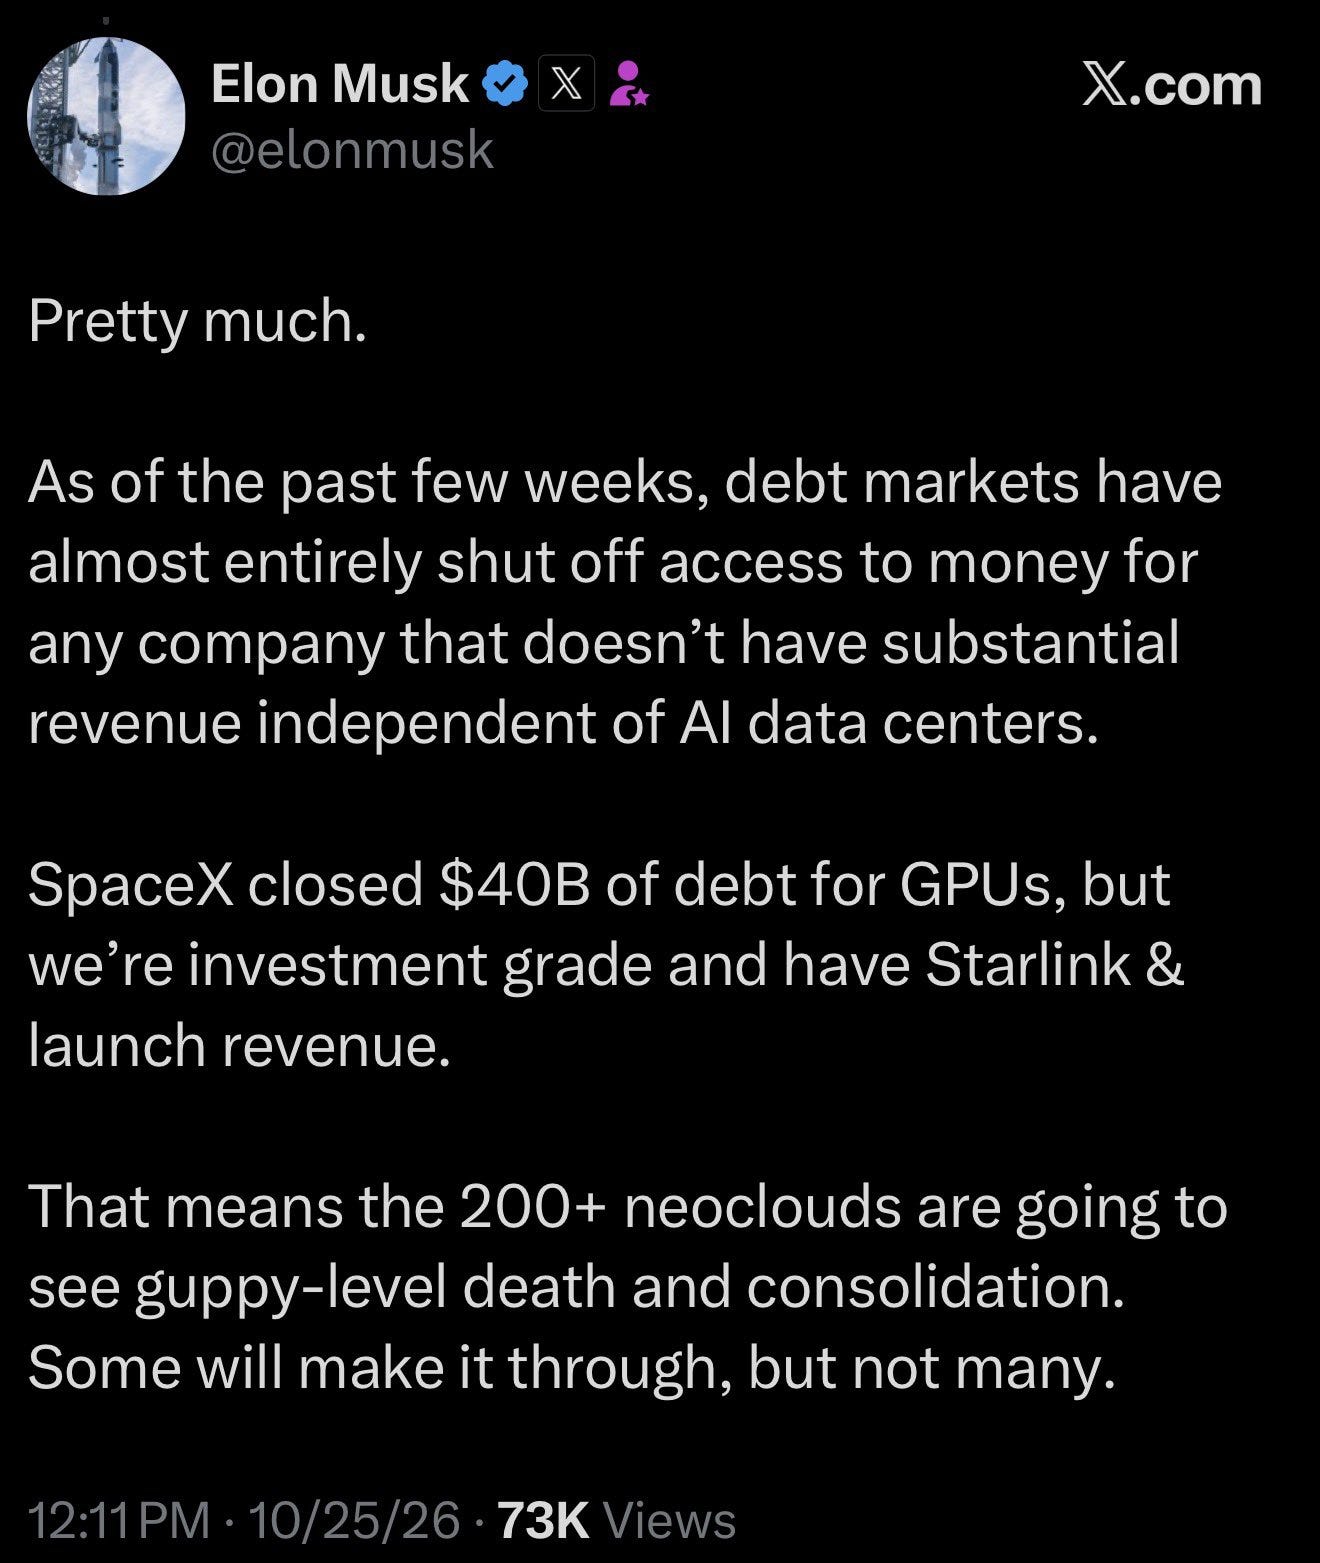
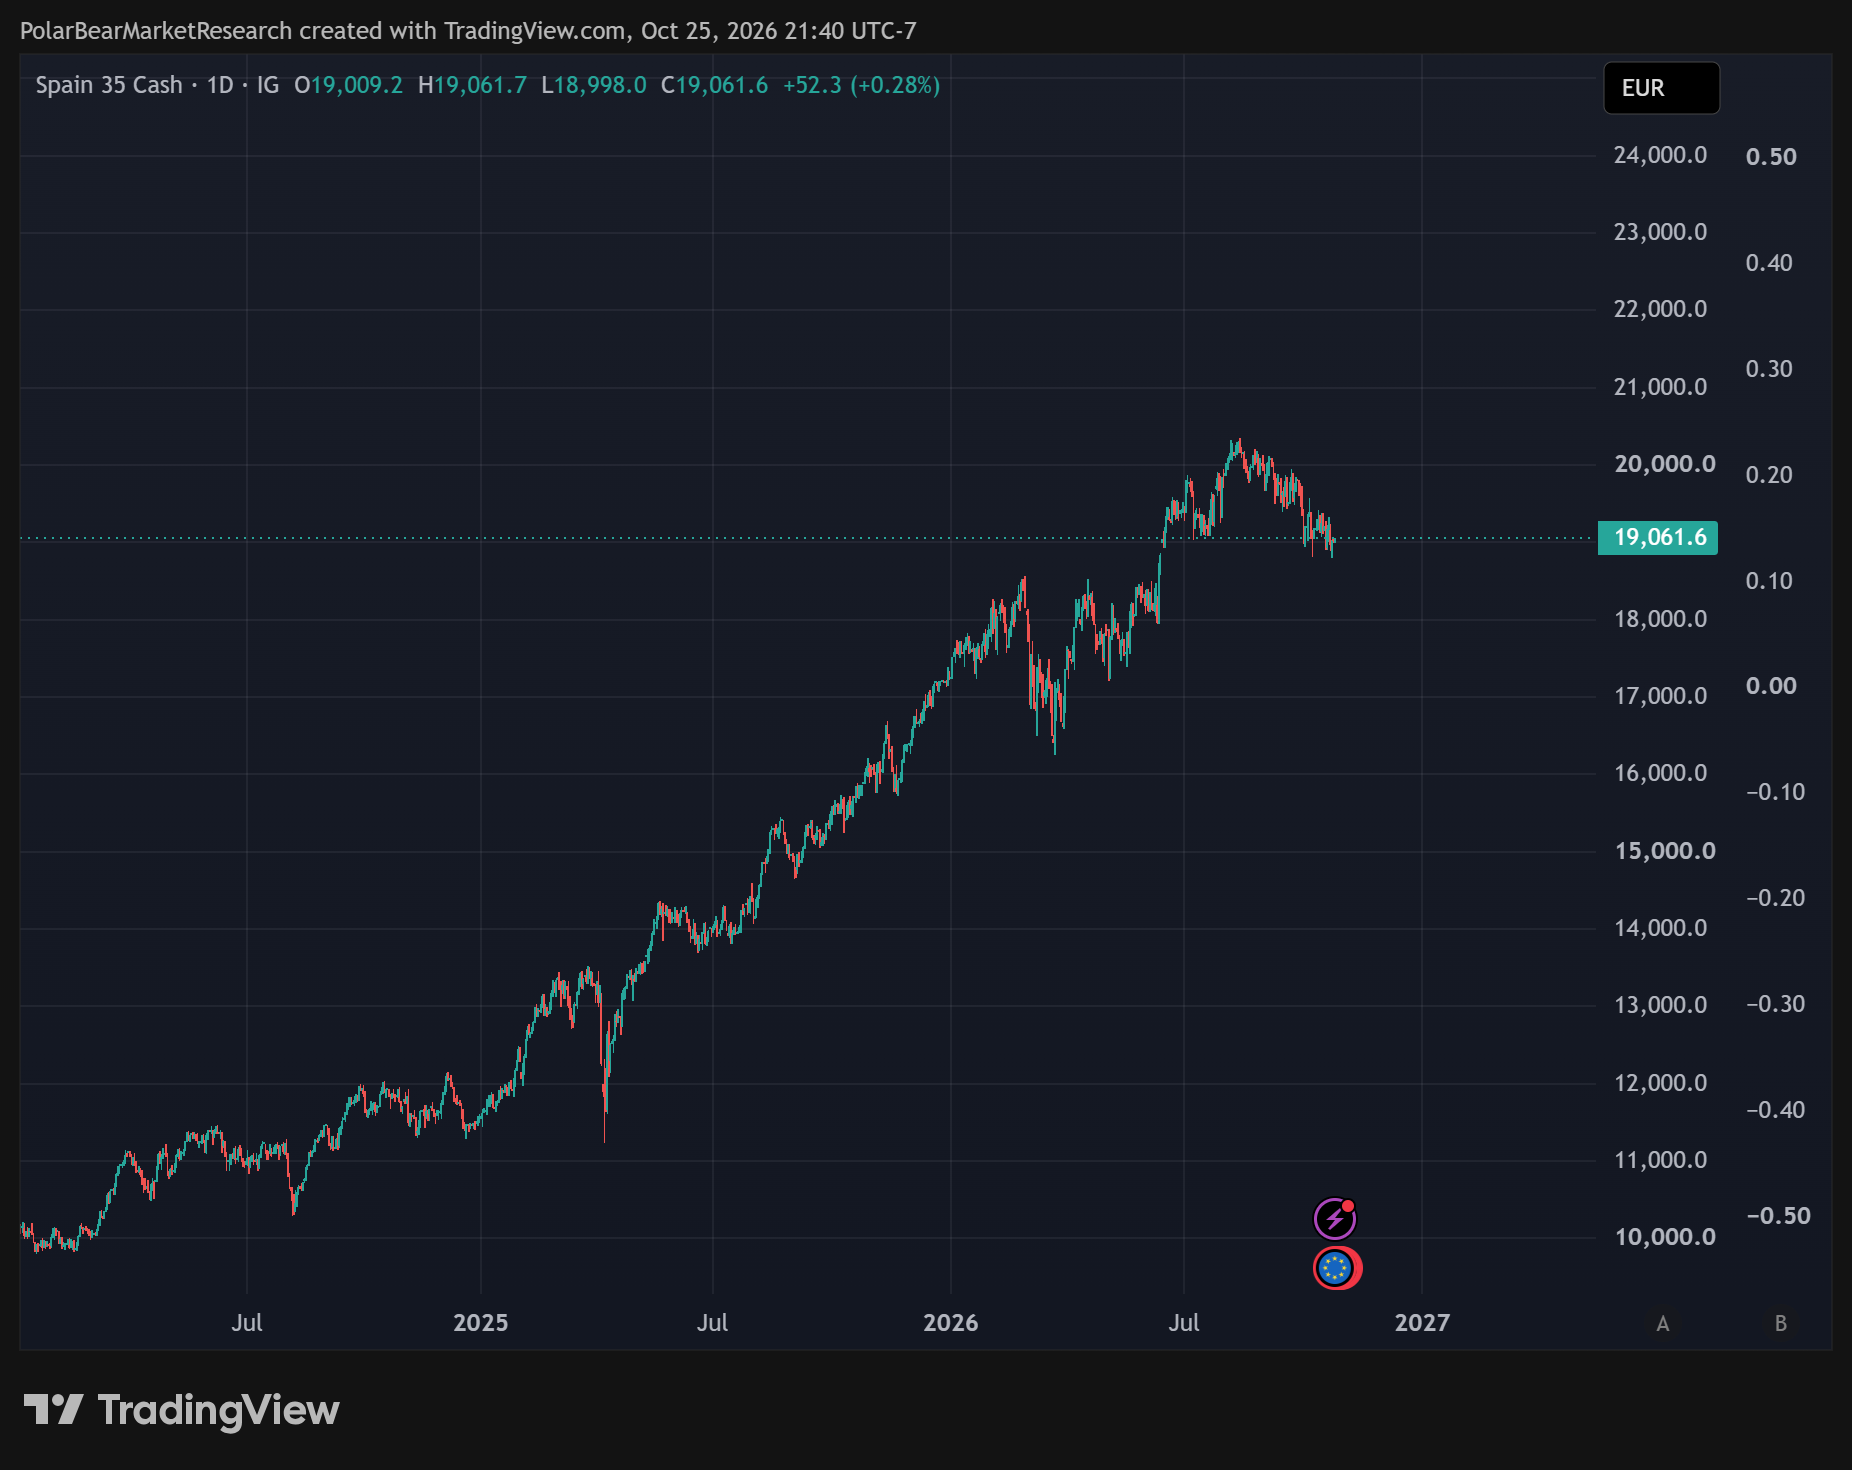
As I’ll go into in greater detail below, I think we’re fairly close to a downward impulse moment before a 3-6 month consolidation period, particularly in technology equities. The foreign indices, which are key components of our GBI, will continue to provide a useful signal:
If we simply see another ‘puck save,’ as Fintwit often calls these local-low moments, then the downward momentum will halt and new all-time highs will follow. On the 4-hour chart for tech (NQ), a positive springboard has formed, so if it validates, we likely get a rally into the midterms.
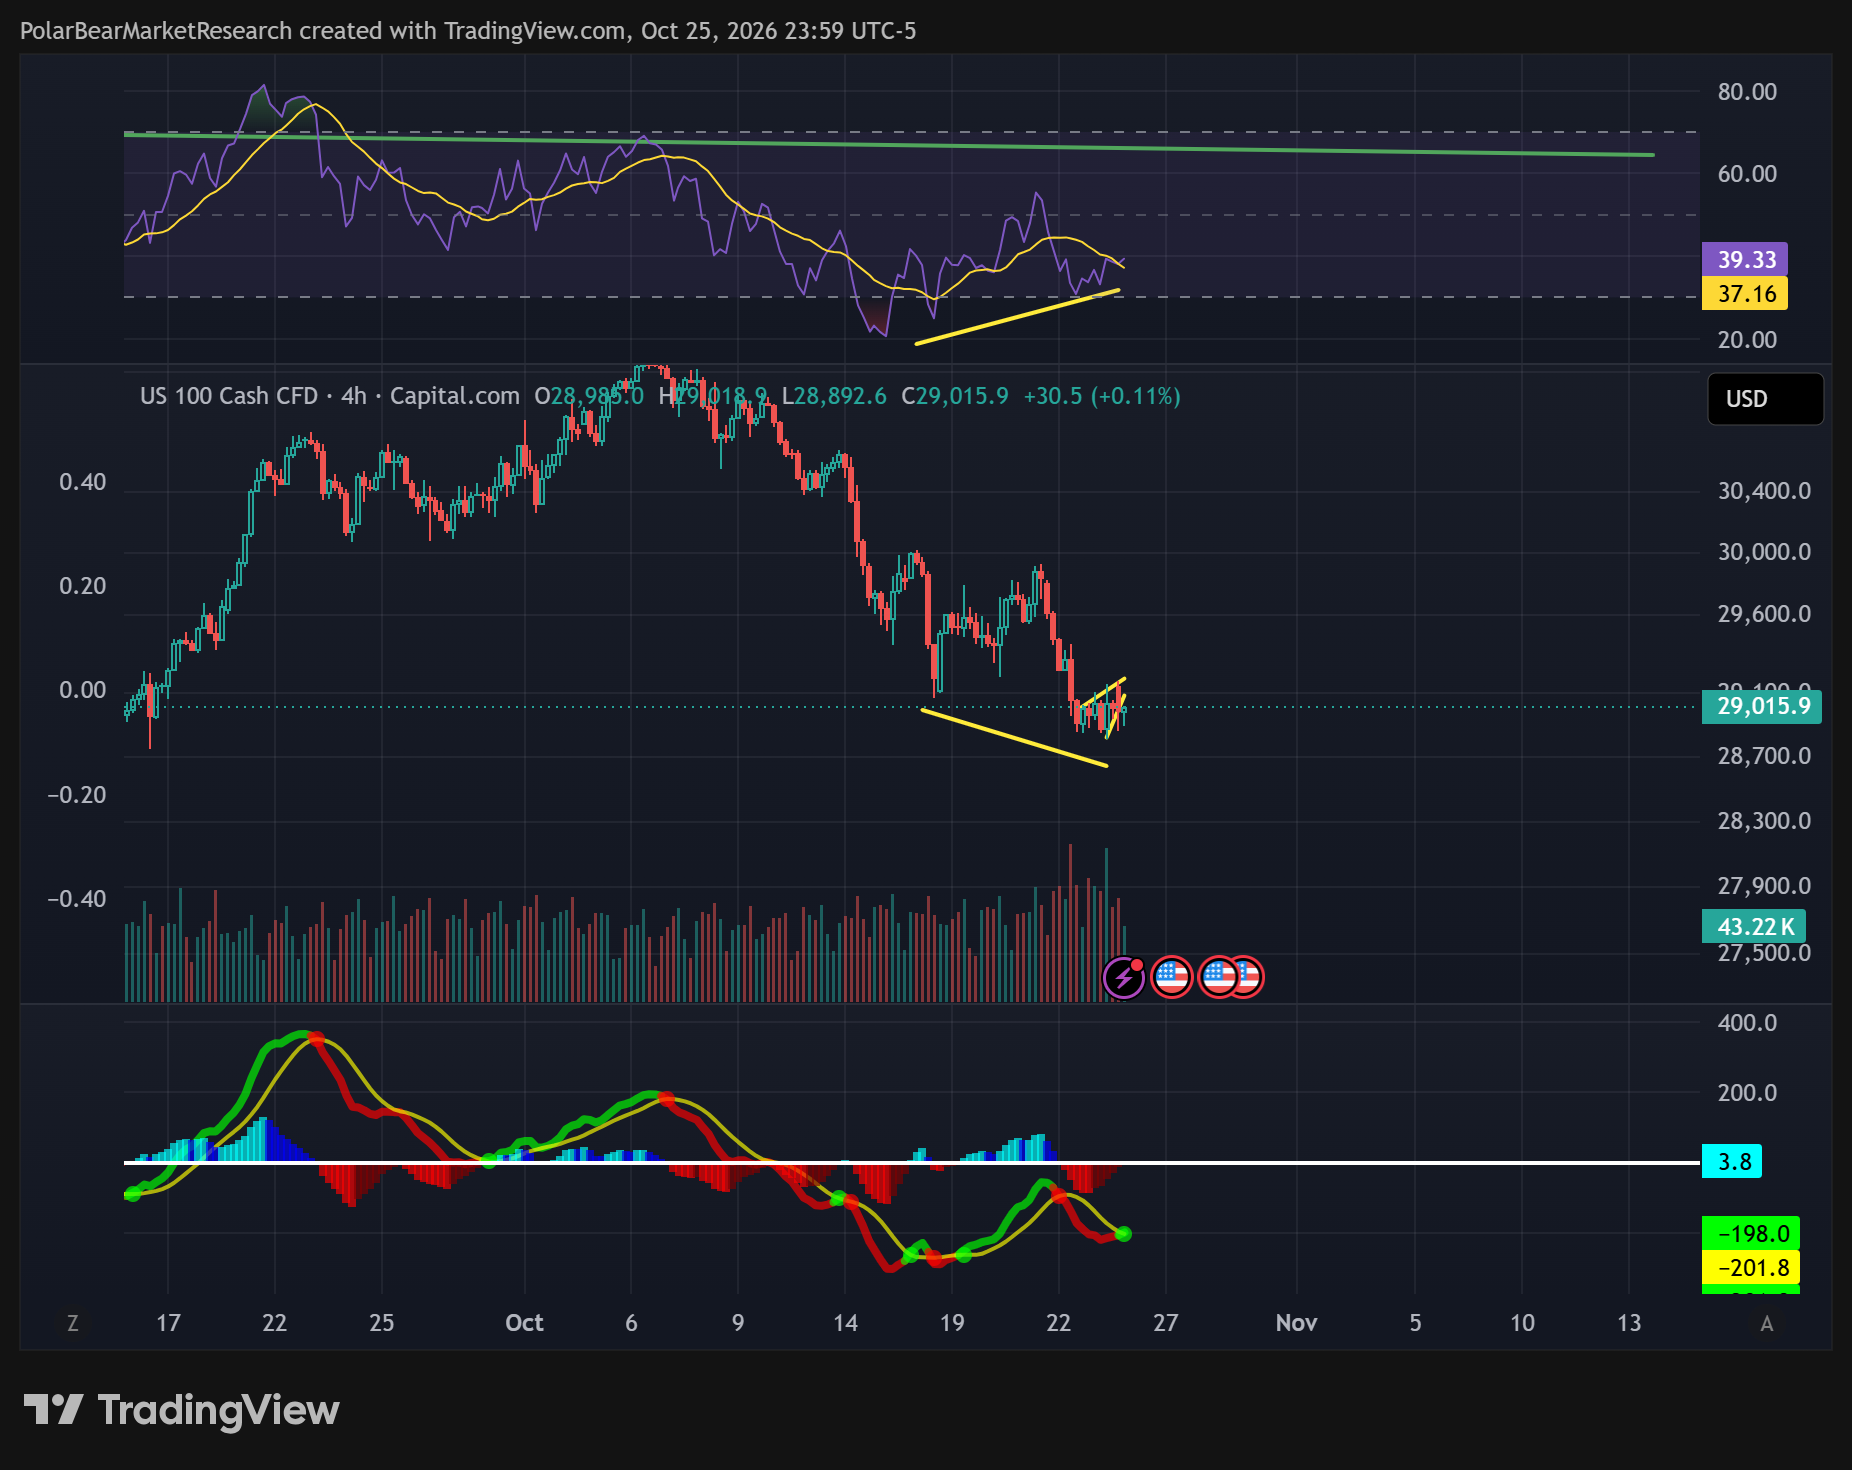
This invalidates with a move lower below the local RSI low.
I think the odds of new all-time highs are becoming less likely as momentum leaves high beta and enters value, commodities, energy, and defensives. I, like many others, am always skeptical of these beta blowout moments, because our policymakers have been fierce about ensuring each dip gets bought up with greater ferocity time and time again, as they unleash the 3-4% CPI range on the public (the real target range they’re telling no one about). In the overnight markets, we’re flat across the board, and there are some developing signs in the momentum tools we use that the selling may soon be done. While I’d like to see an impulse lower to help validate the odds of a lower high (which hasn’t happened in a very long time), this process will be dragged out. Oil prices are also going to play a key role in the process. Last night, I discussed why oil prices in real terms are not impacting US consumers, even though they will be very harmful for the GOP at the polls in a little over a week.
On the oil markets front, we’re seeing a very similar open to last Sunday: a little gap-down action on the fact that neither Trump nor Bibi decided to escalate before the elections. I highlighted yesterday evening in the Weekly Oil & Gas Macro Note that we’re likely entering the most difficult price range for oil since the start of the conflict and since this higher price cycle began. Yes, considerably more difficult than earlier in the year, when policymakers decided to unleash their SPRs on the world. Things are changing, and so is the world, before our very eyes… Patience through October remains the name of the game in the final week of the month as we enter the final sprint into the US midterm elections. The Strait and the Bab remain effectively closed, and one side will be forced to blink, barring a diplomatic resolution. When things seem a little too easy or predictable, we can be certain they won’t be, but I think our framework will continue to be effective in seeing through the crazy noise that’s going to hit the tape this week.
In Brazil, the elections have delivered a shockwave to markets so far. Markets are slated to open down about 20% tomorrow, and Petrobras is currently down about 15% in the overnight hours. This was the first major rejection in the Western Hemisphere of the major rightward shift the hemisphere has seen over the last 2+ years, with Milei, Trump, and many others. I suspect this rejection will continue over the next 2 years on our side of the world, and elections are going to be a very mixed bag from country to country as we play populism whack-a-mole… Can any of these candidates really deliver the solutions to get us out of our problems? Not in my view. We’re on a relatively autonomous train that will decide when enough factors line up for a crash moment, with interventions along the way, though that’s approaching things with a multi-decade framework…
This evening, we’re going to review our report schedule for the week, which is jam-packed with our 1H Oil and Gas Outlook and much more. We’ll look at this week’s macro events, discuss the FOMC decision and our view on the outcomes, lay out three scenarios for the oil pathway from here, and briefly talk about the elections and their impact across the countries named above.
Not yet a MacroEdge Ozone subscriber? Get all of our reports, data, portfolio strategy, commentary, and much more by upgrading:
On 11/1, we will be making a price adjustment to Ozone to keep supporting our growth and meet demand. Ozone will increase from $33.33/mo to $45/mo, and from $350/yr to $399/yr. None of these changes will impact existing subscribers, including those on an annual plan scheduled for auto-renewal.
Report Schedule for the Week
We’ve got a busy one ahead of this week, and we will be continuing the usual cadence of reports coming out between the 1am-4am ET hours. Don’t forget to change those clocks next weekend…
Tuesday: War Note - The Final Days of Patience thru October
Wednesday: (Private Publication for Oil and Gas Research Subscribers and Oil and Gas Advisory Clients → Our First 1H Outlook), Oil and Gas Strategy Note, Portfolio Strategy Note and Commentary
Thursday: Midweek Macro Note: FOMC Recap
Friday: Redeye Macro Note: NYC Edition
Saturday: Oil and Gas Research Macro Note
Sunday: Weekly Macro Note (Ozone)
Not yet subscribed to Oil and Gas Research? Upgrade below:
Macro Week Ahead
Monday: Chicago and Dallas Fed data
Tuesday: CB Consumer Confidence, September New Home Sales
Wednesday: FOMC Rate Decision
Thursday: Q3 GDP Advance, PCE Price Index
Friday: Employment Cost Index, UMich Consumer Sentiment - Final
This week will primarily focus on stupid NFL-like coverage of the FOMC rate decision on Wednesday. It looks very unlikely that the Fed will adjust rates this close to the midterm elections, though I suspect they will remain quite restrained on providing broader support to markets for the time being (... remember my note on ‘Powell’s Valhalla’ the other day?)... Warsh is no Powell for the time being.
Outside of that, PCE is the second important item, and UMich will drop right before the following Tuesday’s midterm - and likely show an all-time low reading for consumer confidence. UMich may need to start working on another axis or way to measure the index if we keep readings this low. Other than that, no real demand destruction for petroleum products, higher jet and diesel prices are crushing airlines and the freight sector, and things still need to go up to find an equilibrium - especially with current subsidies skewing real demand.
FOMC Week Ahead
Come one, come all, to watch more circus-like coverage of an FOMC interest rate decision and Warsh press conference. This week - it’s very likely that the Fed holds rates.
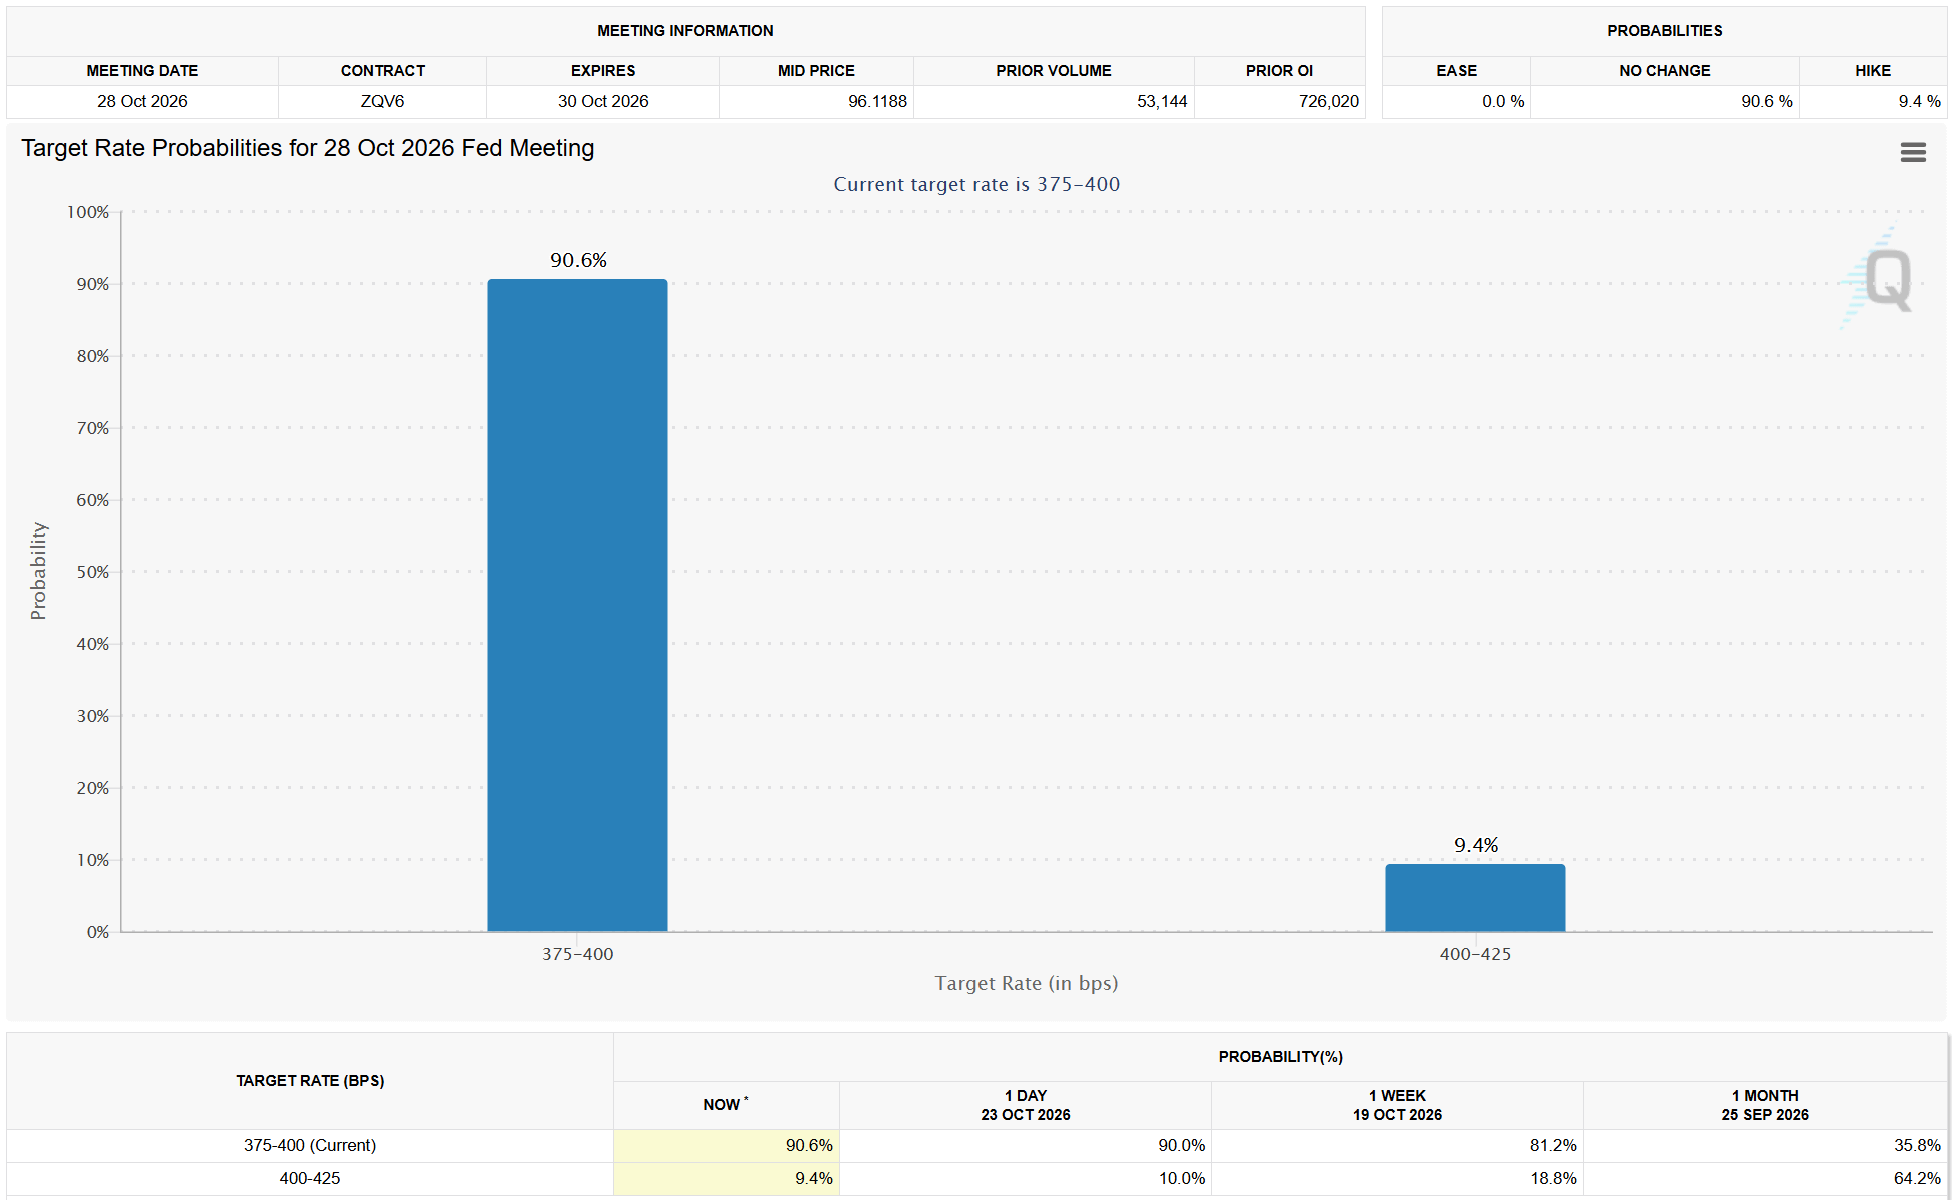
The PCE reading comes in after the decision - and I suspect that they announce they are going to move again in December on rates - which will put further pressure on the AI/data center trade apparatus and financing machine.
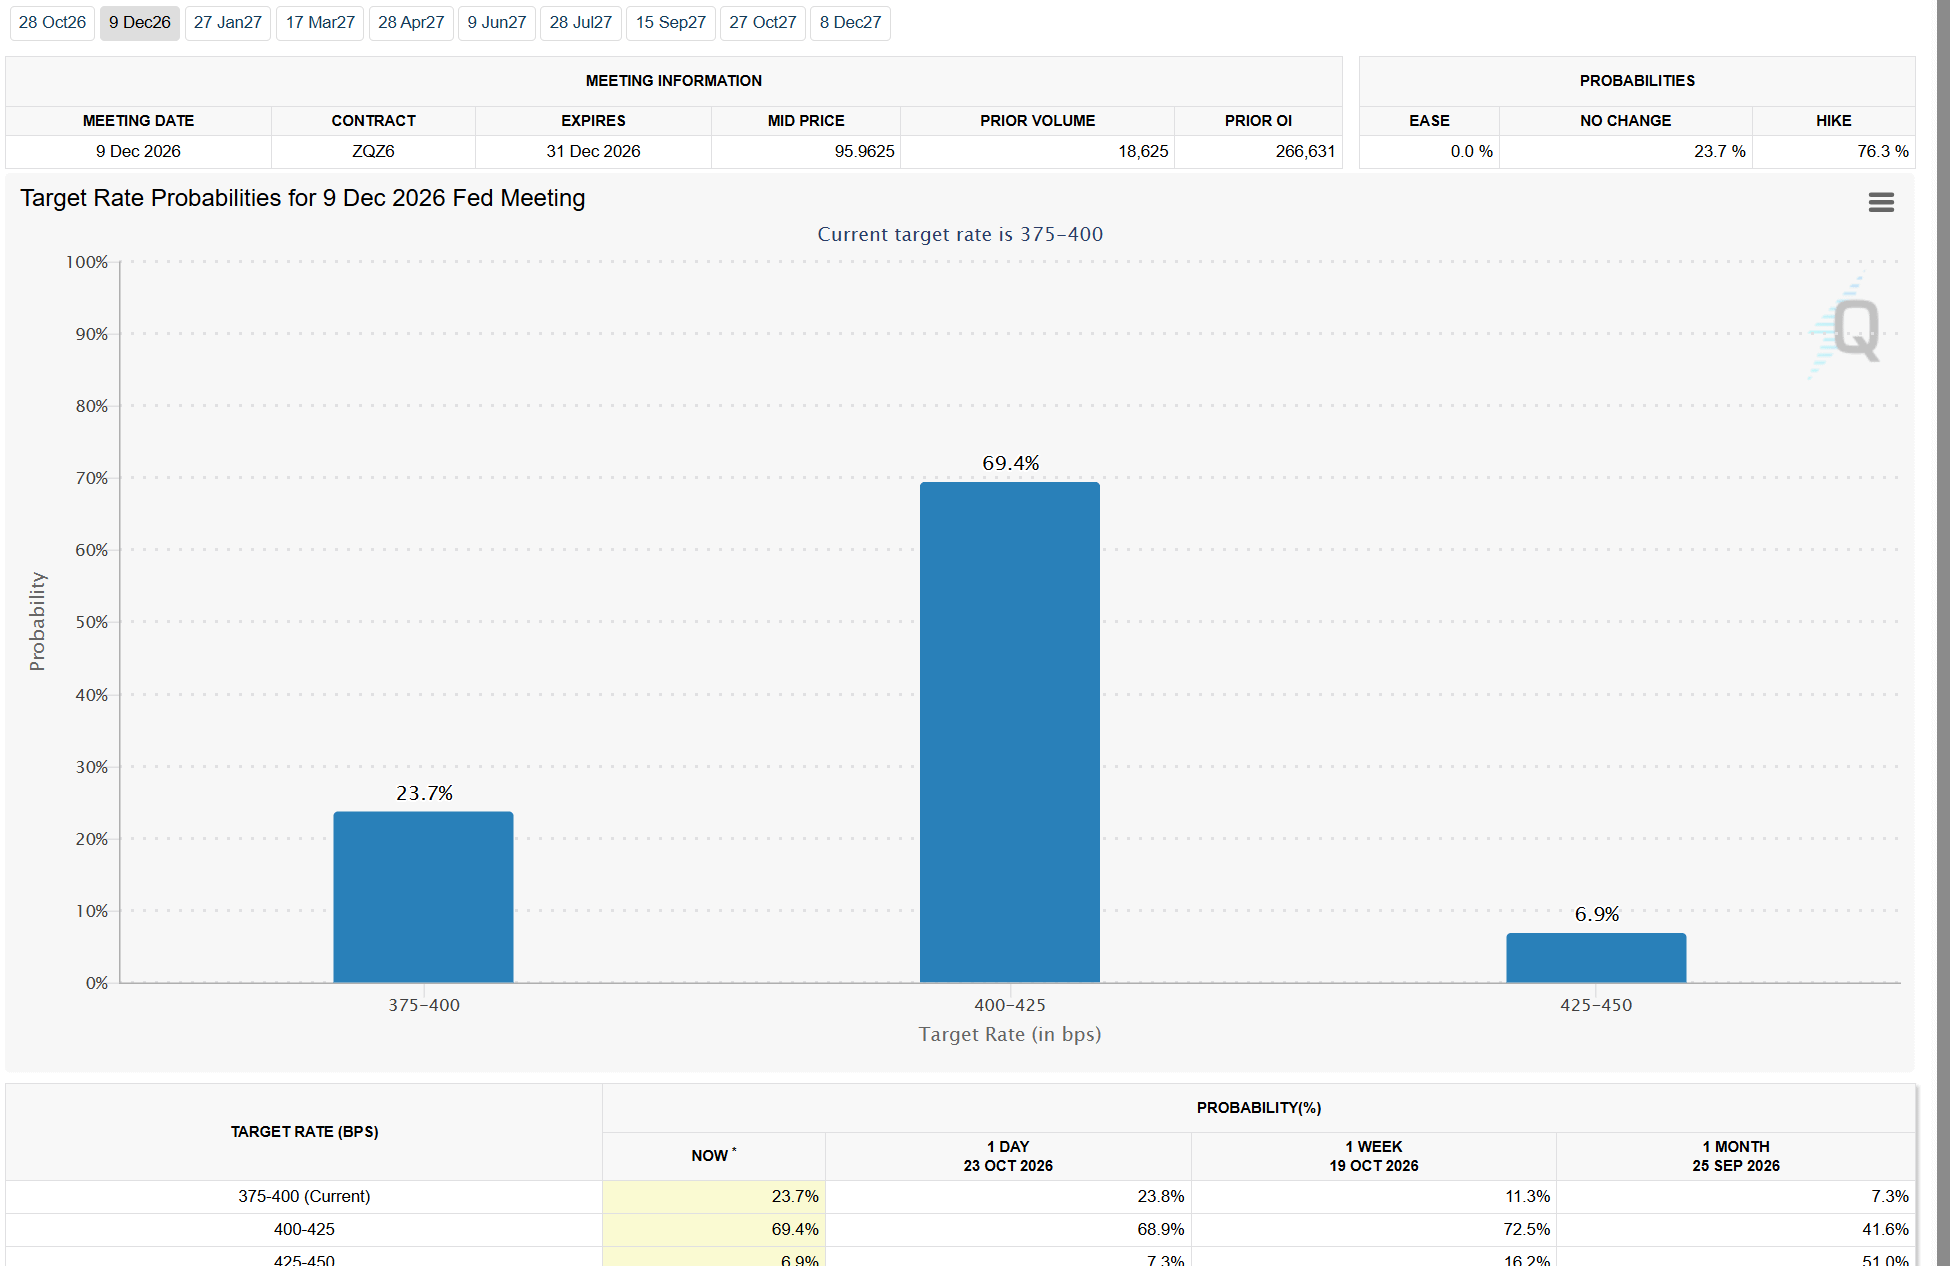
If we get a hot PCE - this December hike odds set will jump to about 90%.
The Fed is ill-equipped to solve a global supply shock - and a lame duck period from November to January could prove useful and constructive for energy prices to move higher - especially if we get a cold winter in North America and Europe.
Oil Pathways from Here
Continue reading below by upgrading to Ozone… Oil pathways from here, election outlook, and more…
