

Good Tuesday evening MacroEdge Readers & Community,

Hopefully you are all having a successful start to your week. We continue to watch dynamics evolve in the Middle East - particularly between the Houthis and Saudi Arabia - this shiny object (being Yemen) is getting shinier as a distraction, though it appears that Trump is showing restraint in order to prevent broader escalation in this pre-midterm window. With early voting already underway, the party in power is heading into midterm elections with diesel prices at all-time highs (they should be at or near on Friday) and retail gasoline prices set to rise further once again in the coming weeks. We may have another TACO in the pipeline - that may serve as the last - though there are still additional emergency measures that the President may undertake during this energy shock such as:
> Diesel export ban
> Oil export ban
> Additional SPR releases under state of emergency
> Seizure of foreign oil
> Defense Production Act (we’ve already seen this for refining capacity)
While some of these may sound ‘far off’ at this point given the $95 WTI / $110 Brent environment we have today, I don’t think several of them are that far off once we get through the midterm period and are looking at a President that could escalate things once again with Iran. With the Strait of Hormuz on the verge of seeing flows meaningfully impeded once again - we are in a world where that can simply not happen given the rate at which emergency barrels are being released.
We appear to be in an environment where we are slowly normalizing higher prices for longer, and look no further than the curve pricing in >$80bbl now, through November, as further evidence.
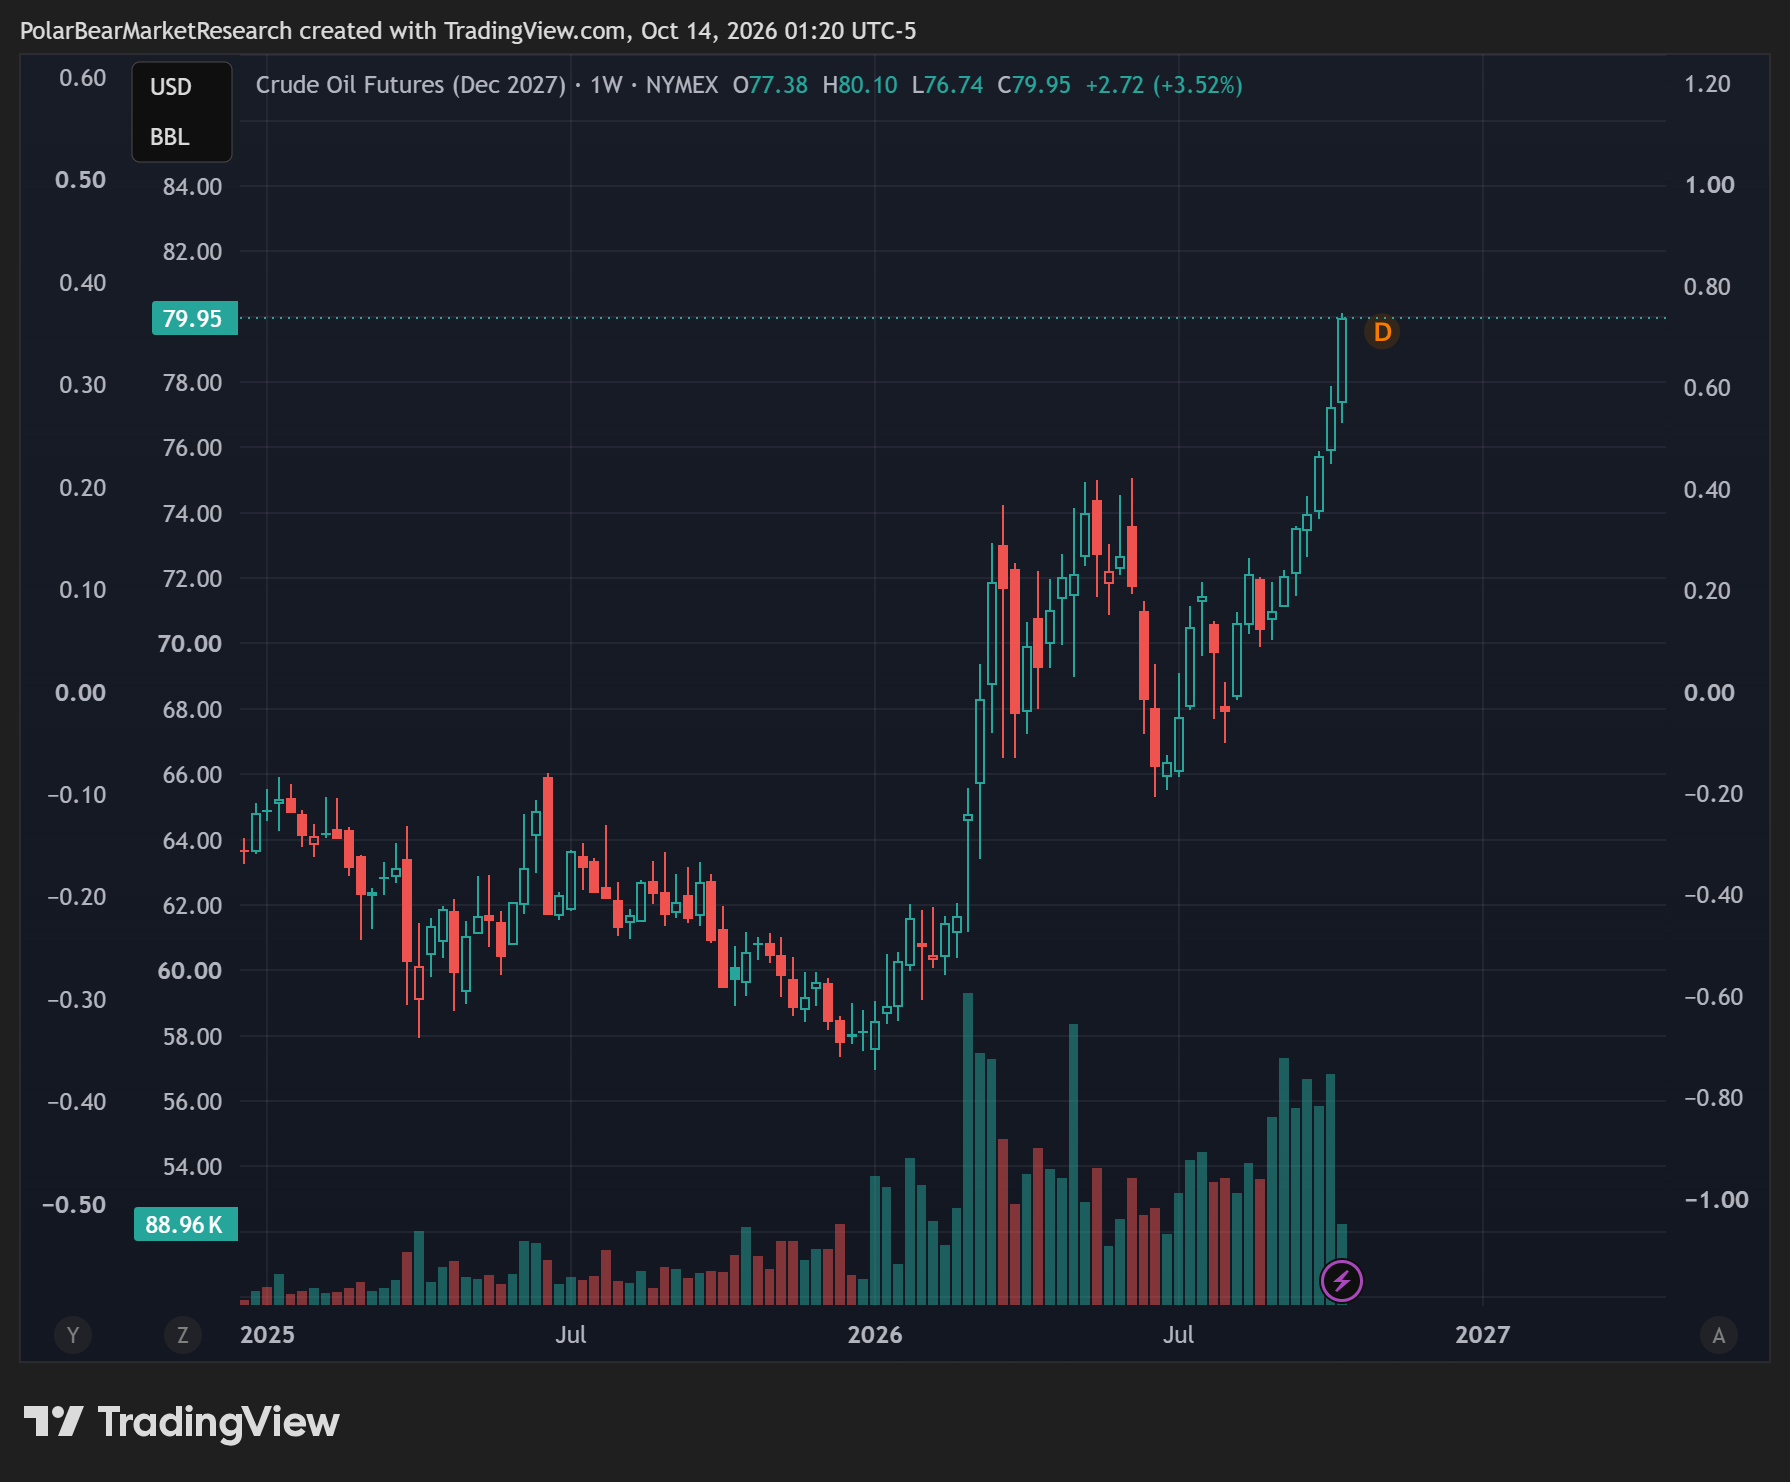
Diesel prices shifting to a higher for longer mindset too? I think so.
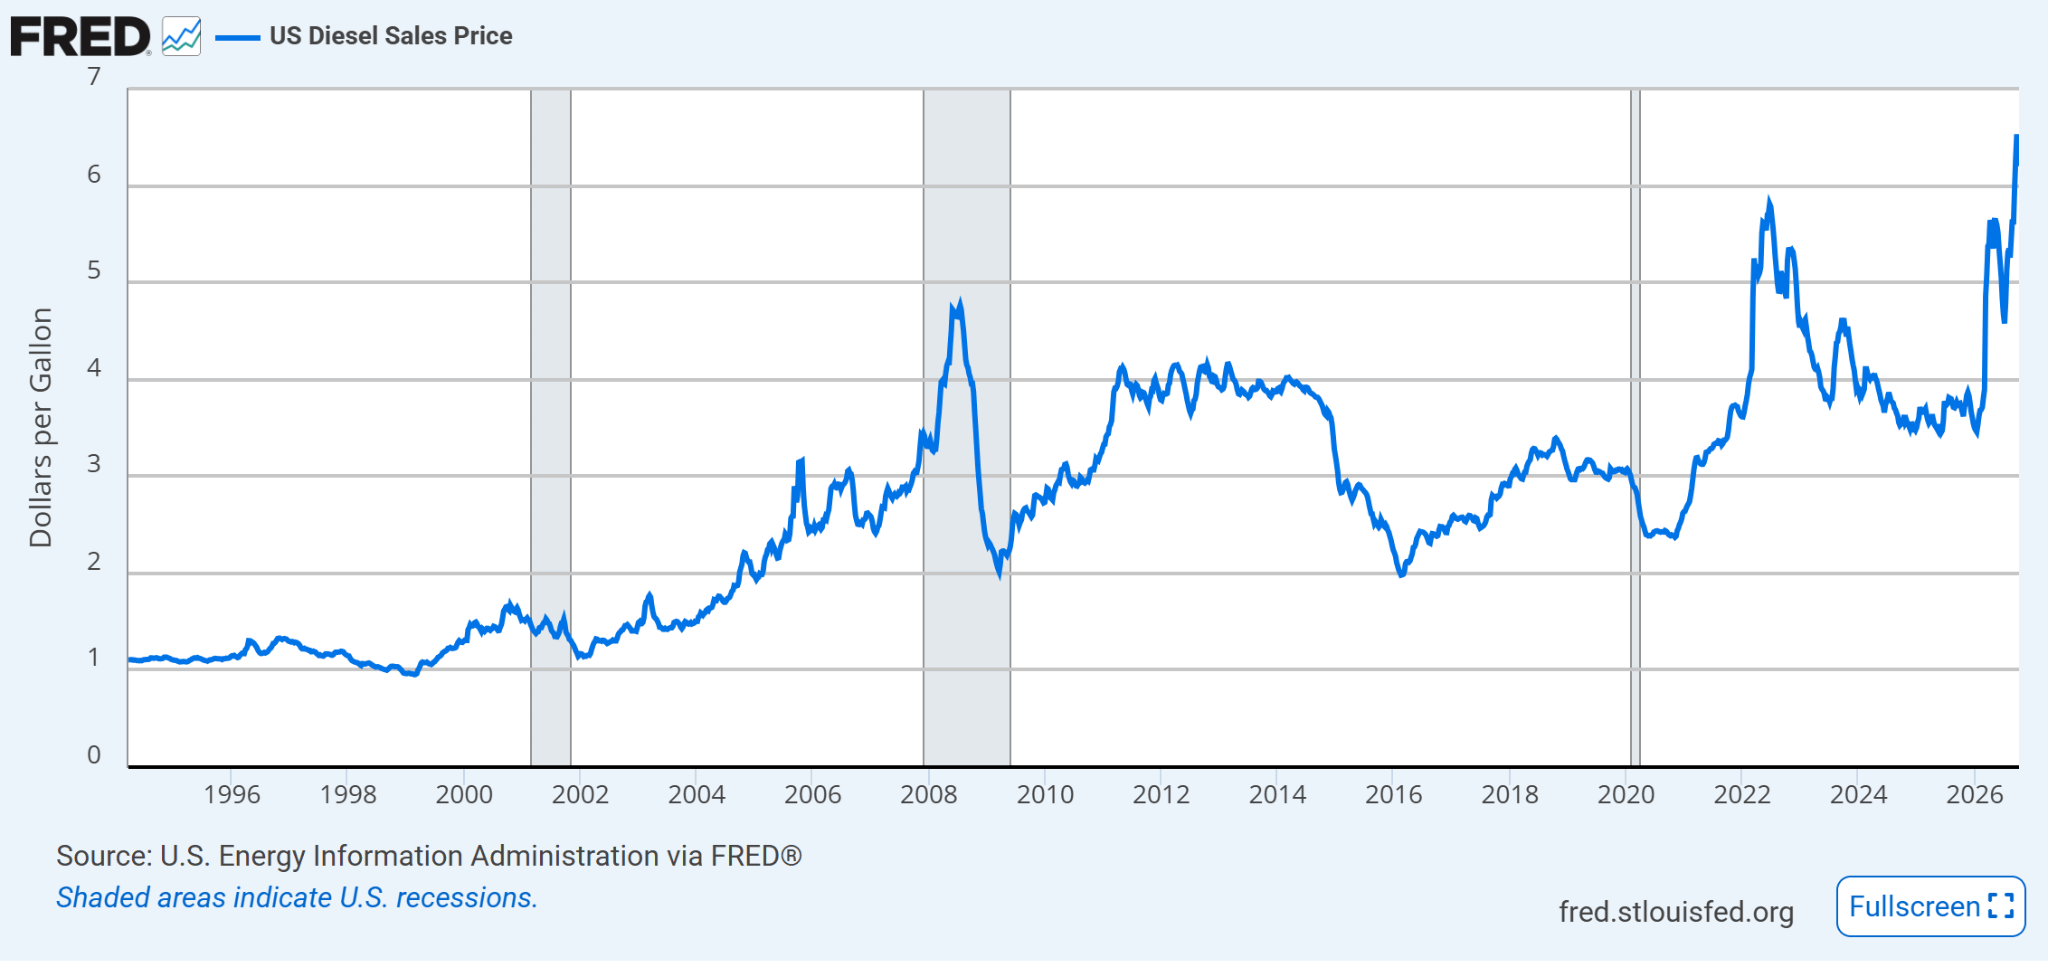
The next major shift we are likely to see from an energy policy standpoint, globally, is one from cooperation to protectionism.
Outside of the energy environment - which I expect will remain the most critical thing, along with bonds to watch for the remainder of the year - the AI landscape in Asia, particularly in South Korea, continues to see a wobble that’s getting more violent. In the Sunday Weekly Macro Note - I highlighted the tremendous vulnerabilities emerging in Korea on both a technical and leverage standpoint - and it appears that foreign investors are in fact taking notice of that tremendous concentration risk. If you’re not following our two, live portfolio strategies, we continue to position ourselves and adjust intelligently for this dynamic, yet apathetic landscape, make sure to get Ozone below before the price goes up at the end of the month (to $45/mo, from $33/mo):
On the docket this evening:
Schedule for the Rest of the Week
Mid-Month Update Out Thursday Evening
Asia Red Flags for the Semiconductor Landscape, Checking on the IBEX
Walking a Tight Rope
Schedule for Rest of Week
Wednesday: Oil and Gas Research - Looking at CRC and ACDC - Strategy Note, Portfolio Strategy Note - Ozone - Flagship Strategy Comments
Thursday: Mid-Month Update, Changes, December Event
Friday:
Mid-Month Update Out Thursday Evening
This Thursday - we’ll have our comprehensive mid-month update out on all of the changes, transitions, and positive things coming to MacroEdge. We are enhancing our organization with 2030 in mind: with improvements, changes, and a place to connect in December all in the pipeline.
Ozone → Transitioning to a Macro-based Strategy-First Focus - based on performance
Expansion of our Oil and Gas team —> Advisory Offerings and Oil and Gas Research focusing on private and public market opportunities
Revitalizing our MacroEdge Social Media landscape —> New MacroEdge team members will deliver critical data on a 24/7 basis, during US and EU hours - on both our Oil and Gas Research and the official MacroEdge page on X and Substack
Boosting MacroEdge Radio to a mainstream show —> Weekly Live Episodes, Recorded and Shared on our Platforms
Expanding our partnership network with new data providers and more - to bring you the latest real-time, and near real-time that actually matters
Asia Red Flags for the Semiconductor Landscape, Checking on the IBEX
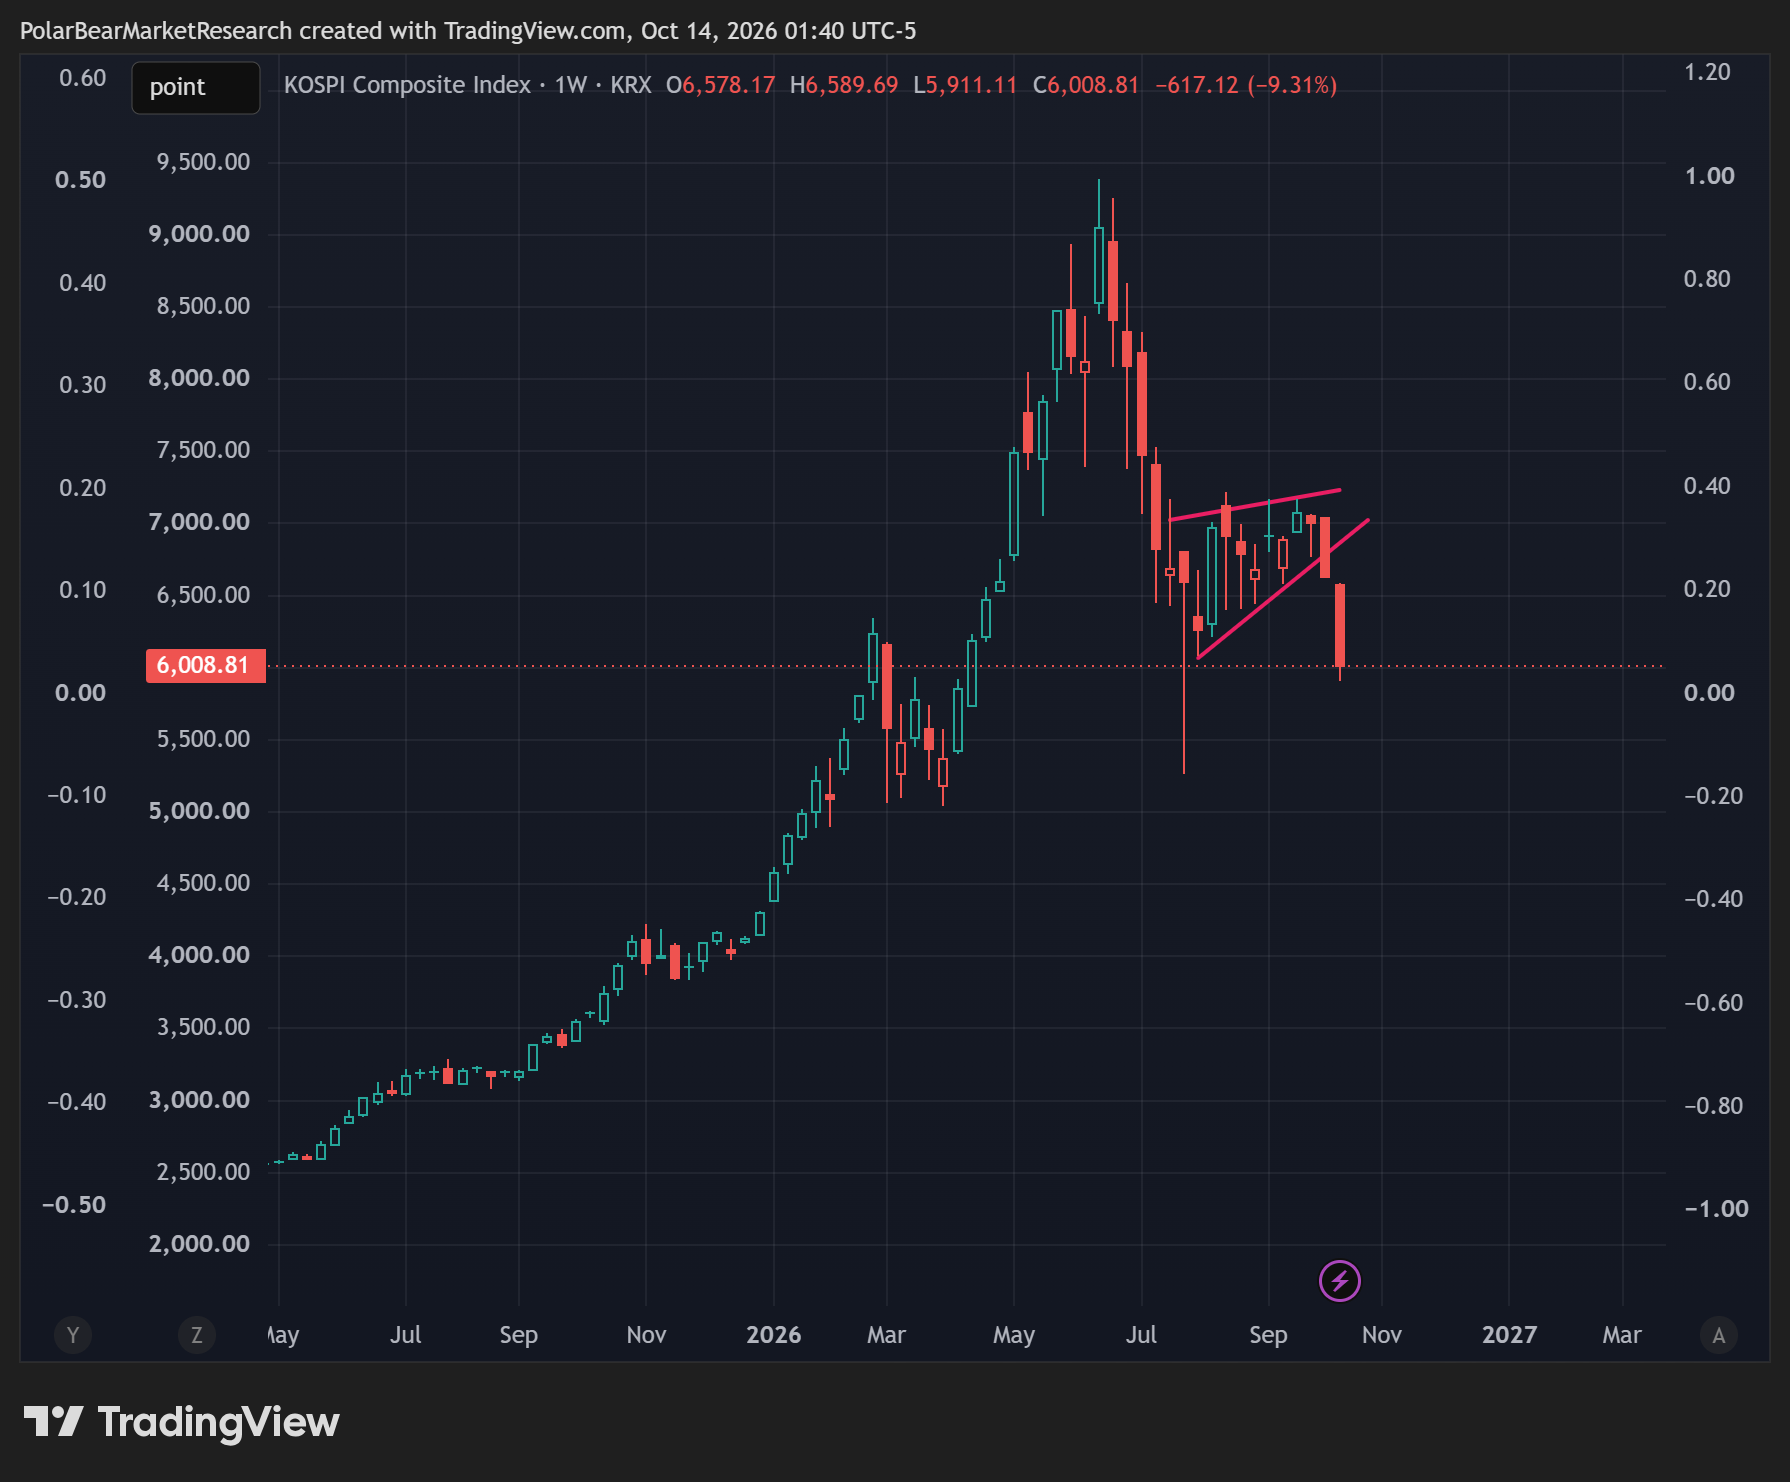
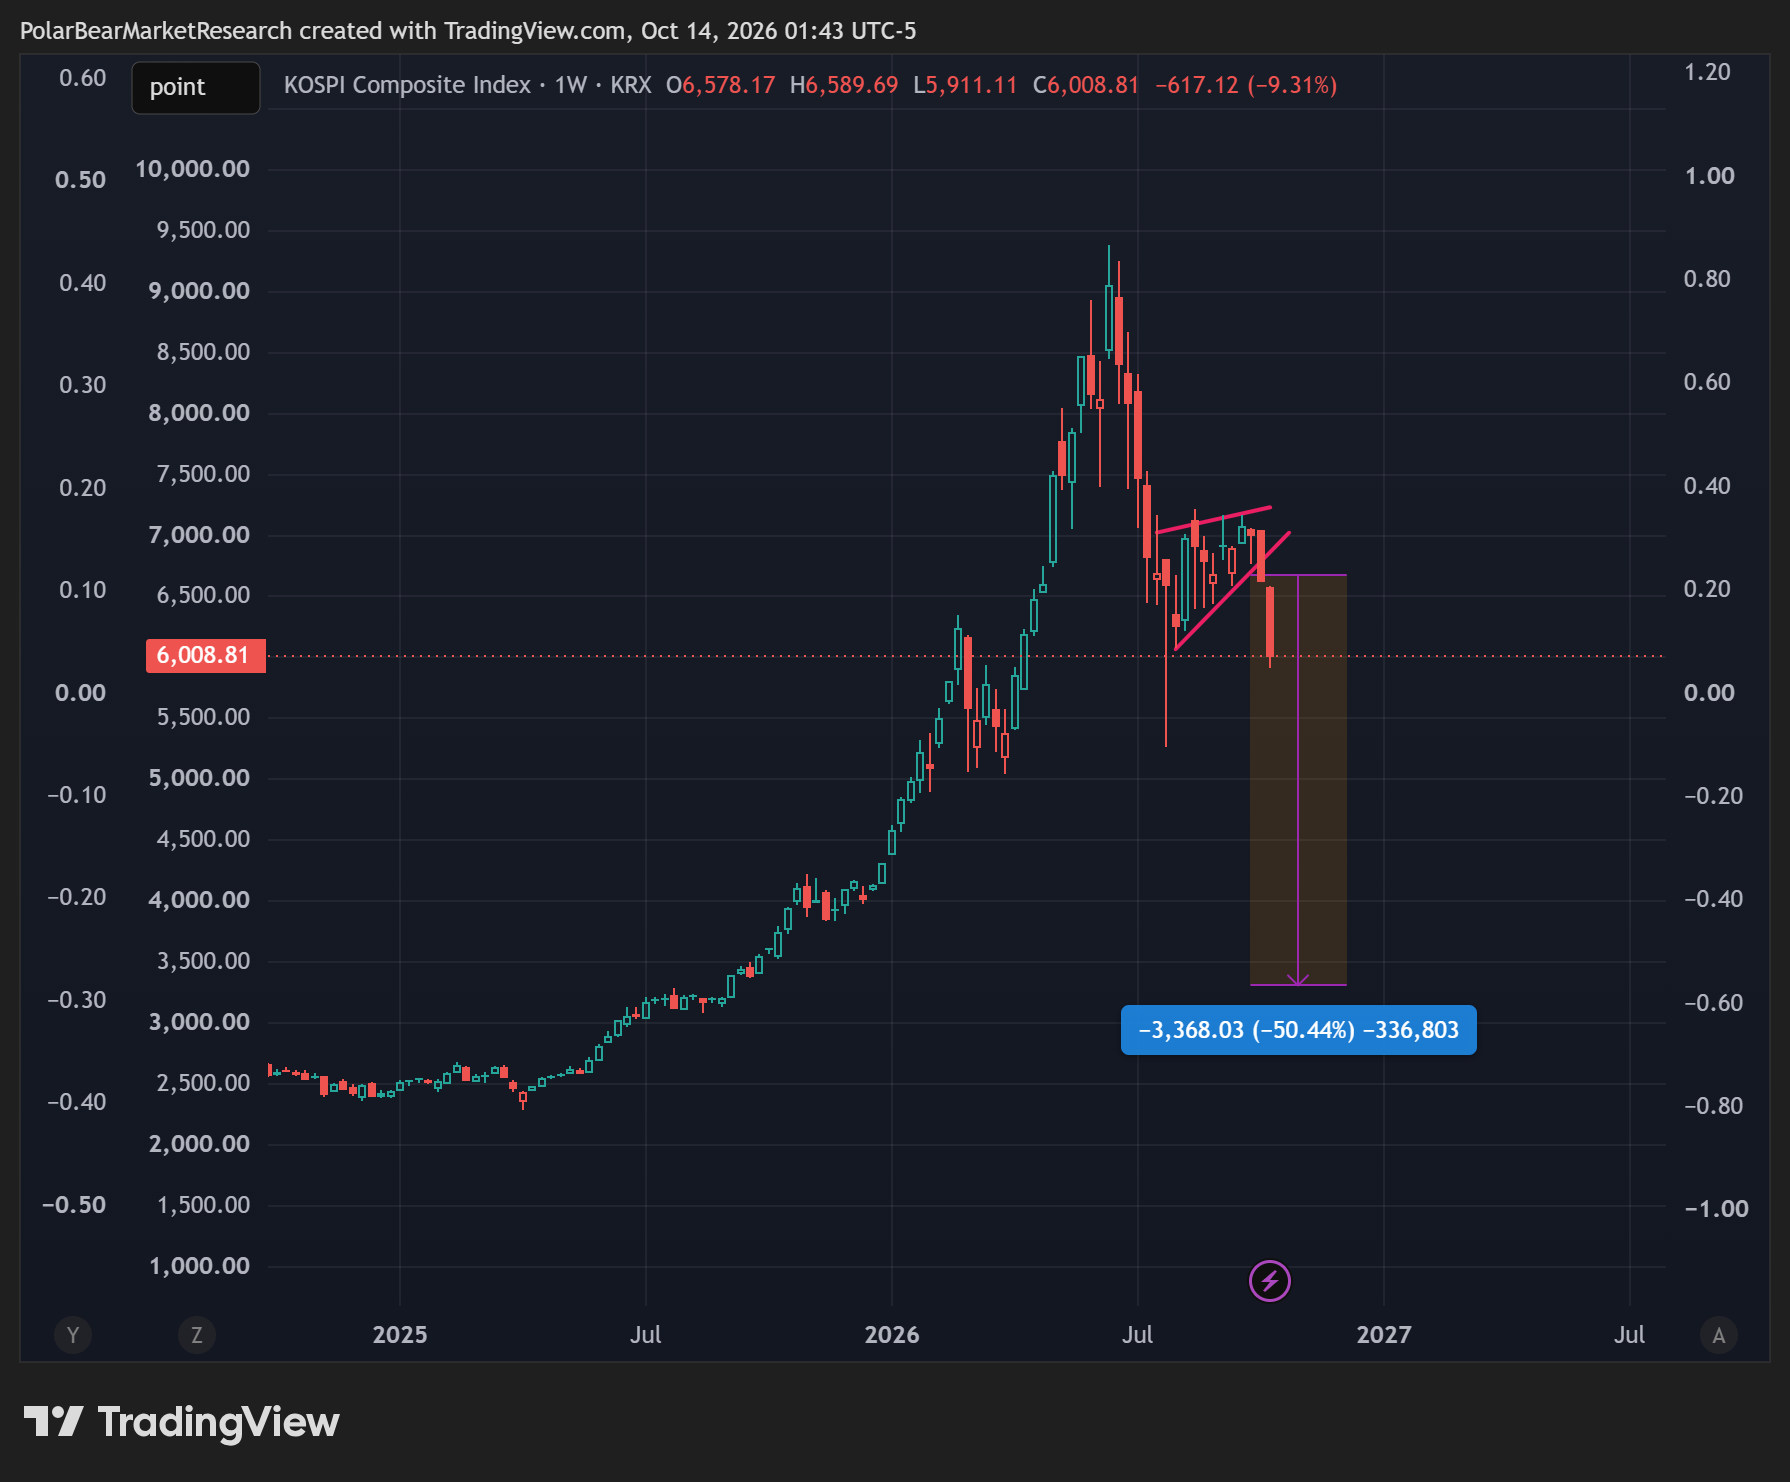
Red flags continue to mount in Asia - driven by wobbles in Korea, Taiwan, and Japan. While Bessent has a vested interest in continuing to bailout and protect Japan - the first two look very vulnerable with concentration and leverage risks at all-time highs.
KOSPI - bear flag galore:
Measured move potential, based on technicals:
Taiwan - lots and lots of nasty divergence potentials now:
Not yet a MacroEdge Ozone subscriber? Upgrade below:
