

Good Tuesday evening MacroEdge Readers & Community,
I hope you all are having a great start to the week… I am starting the first half of the week off in Arizona and to get to enjoy Arizona at 75 degrees with snow up in the northern part of the state is a great time to be here. As I mentioned on my X this morning - one of the themes I continue to notice is a complete lack of understanding around price pressures among business owners/decision makers & in particular how they are all tied to the Middle East/Hormuz situation. While it’s extremely complicated when broken down on a granular level - the reality from 30,000 feet is that so long as the Strait and Bab remain impeded to any meaningful degree - we will continue to see sizable price pressures and impacts across the globe.
We got yet another meaningful acknowledgement of these price pressures today with the announcement from the Trump Administration that they are moving forward with releasing the final 40 million barrels of the large Iran war tranche - which will be lent out to willing takers. This was an important component to my well-defined and outlined ‘patience through October’ narrative which has picked up traction among the smarter minds and commentators on & off of X.
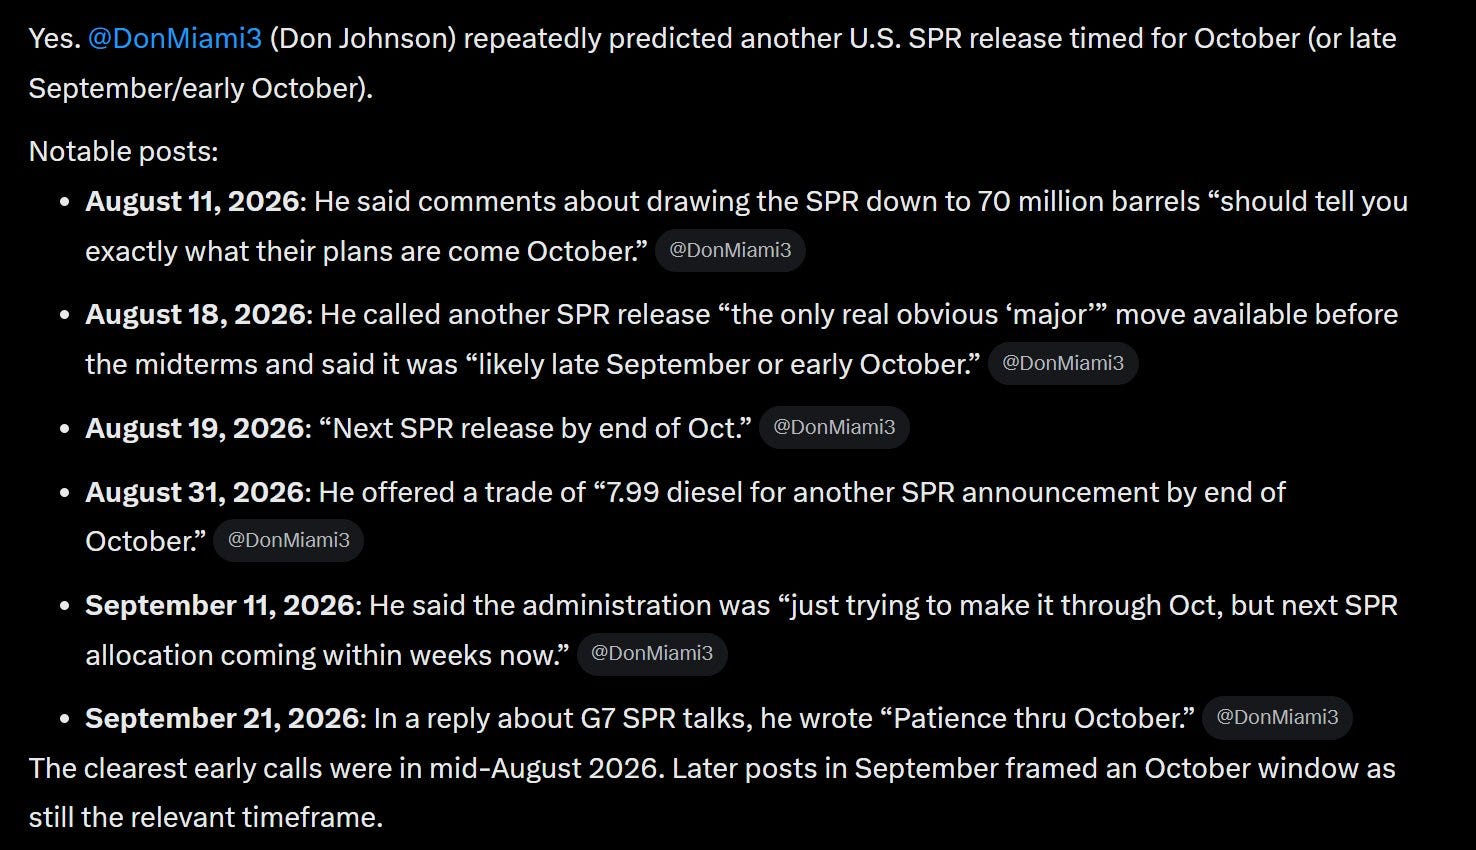
With the announcement of this now in effect, I suspect (and agree with HFI Research) that we start to see SPR releases climb back to the 3-6 million barrel per week range, which will likely take us into early/mid December. What I do not think that it does, unlike the May instance where the combination of headlines + SPR release occurred, is impact front-month prices to any meaningful degree. While we’ll discuss this more in depth tomorrow in the Oil and Gas Strategy Note - and later in the week on Saturday - the back-end of the oil curve is looking more and more robust. I am not using this as my base case price signal, but with the announcement today, I think we are moving toward solidifying that $80-$82/bbl price floor for WTI, which should bring some additional confidence back in the space - which still won’t mean a whole lot given the general permanent bearishness that operators and industry insiders alike continue to hold… It is a bizarre phenomenon, but probably more of an engrained survival instinct, above all else after decades of ruthless cycles.
Outside of the energy landscape, which continues to look robust - with patience, of course - yields have continued an absolutely mega run.
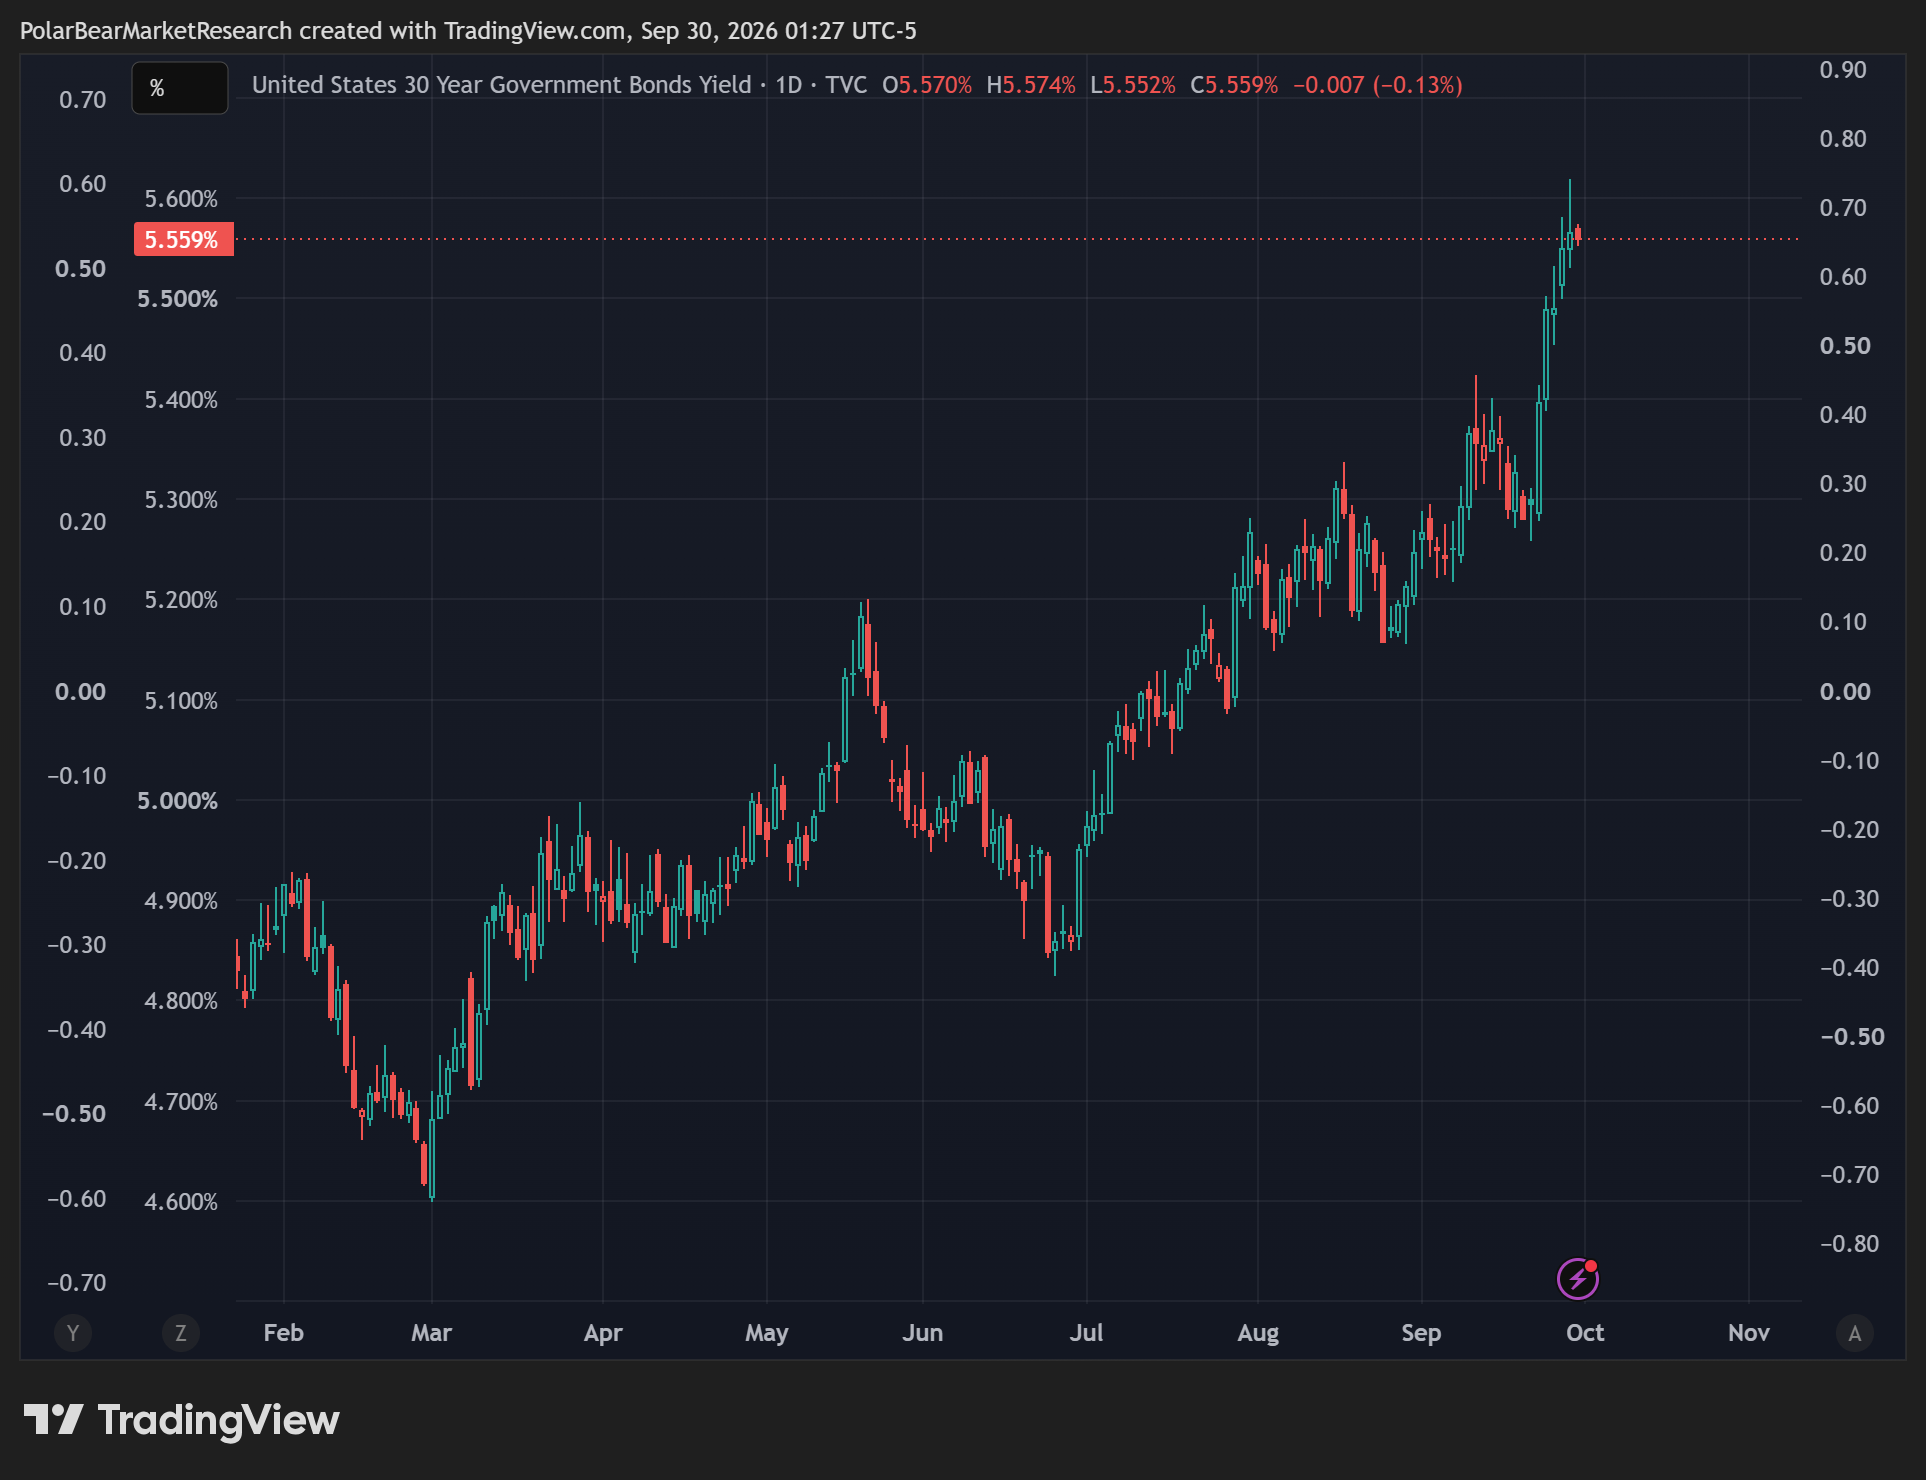
We’re starting to enter a parabolic shaped move in yields, though I still think the real ‘spook move’ could still be behind the curtain. The current move has been enough to spook policymakers to a degree, but other than securing another rate hike or two, equity investors continue to fly blind and roll the dice that a move like 1987 is simply impossible in today’s landscape. I personally think the exact opposite - in the predictable market of today that is relentlessly intervened in and protected at all costs - it will take a black swan to actually get any meaningful shock to the system… and it may even (very briefly) spook policymakers into action. The higher yields are having a dampening effect on cyclical business activity - and we’ll take a look at freight and housing below… Freight is getting the double whammy of diesel prices at/near record highs, and this is something that I have continued to call for softness in as we head into the holiday season.
Not yet a MacroEdge Ozone subscriber? Get all of our research, data access, portfolio strategy, and much more below:
This evening we’ll cover:
The final SPR tranche… for now - right on time
A Look at the Cyclicals - Freight and Housing
Losing Steam - Data Centers, AI, and Tech
Report Schedule for the Week
Oil and Gas Research Strategy Note (Wed) - Don
Portfolio Strategy Note and Updates (Wed) - Six
Midweek Macro Note (Thursday) - Don
Oil and Gas Research Macro Note (Sat) - Don
The Final SPR Tranche… For Now - Right on Time
Today marked a predictable announcement from the Administration in this pre-midterm period that they are moving forward with plans to loan out the final 40 million barrels from the committed SPR tranche that was announced at the beginning of the Iran war. While I do not think this is the end of the SPR saga - they also began prodding the EU to release emergency diesel supplies to get prices lower (a move which looks less likely to happen now than it did a week ago).
All of these moves are signals from a group that has little to no plan, in my opinion, regarding the war - and we could be on the brink of broader escalation once again if Iran finally cracks & lashes out against the naval blockade. There’s a complex economic war balancing act going on right now with Iran choosing to let flows increase through the Southern Omani lane and with ships having been moved further out to sea that were enforcing the blockade. While what we have seen thus far has brought about record high prices - the next phase - if Iran chooses to escalate, will be a grenade pin on prices… I do anticipate that the pin does get pulled, though the patience through October story means we need to maintain patience as emergency measures are burned through and announced.
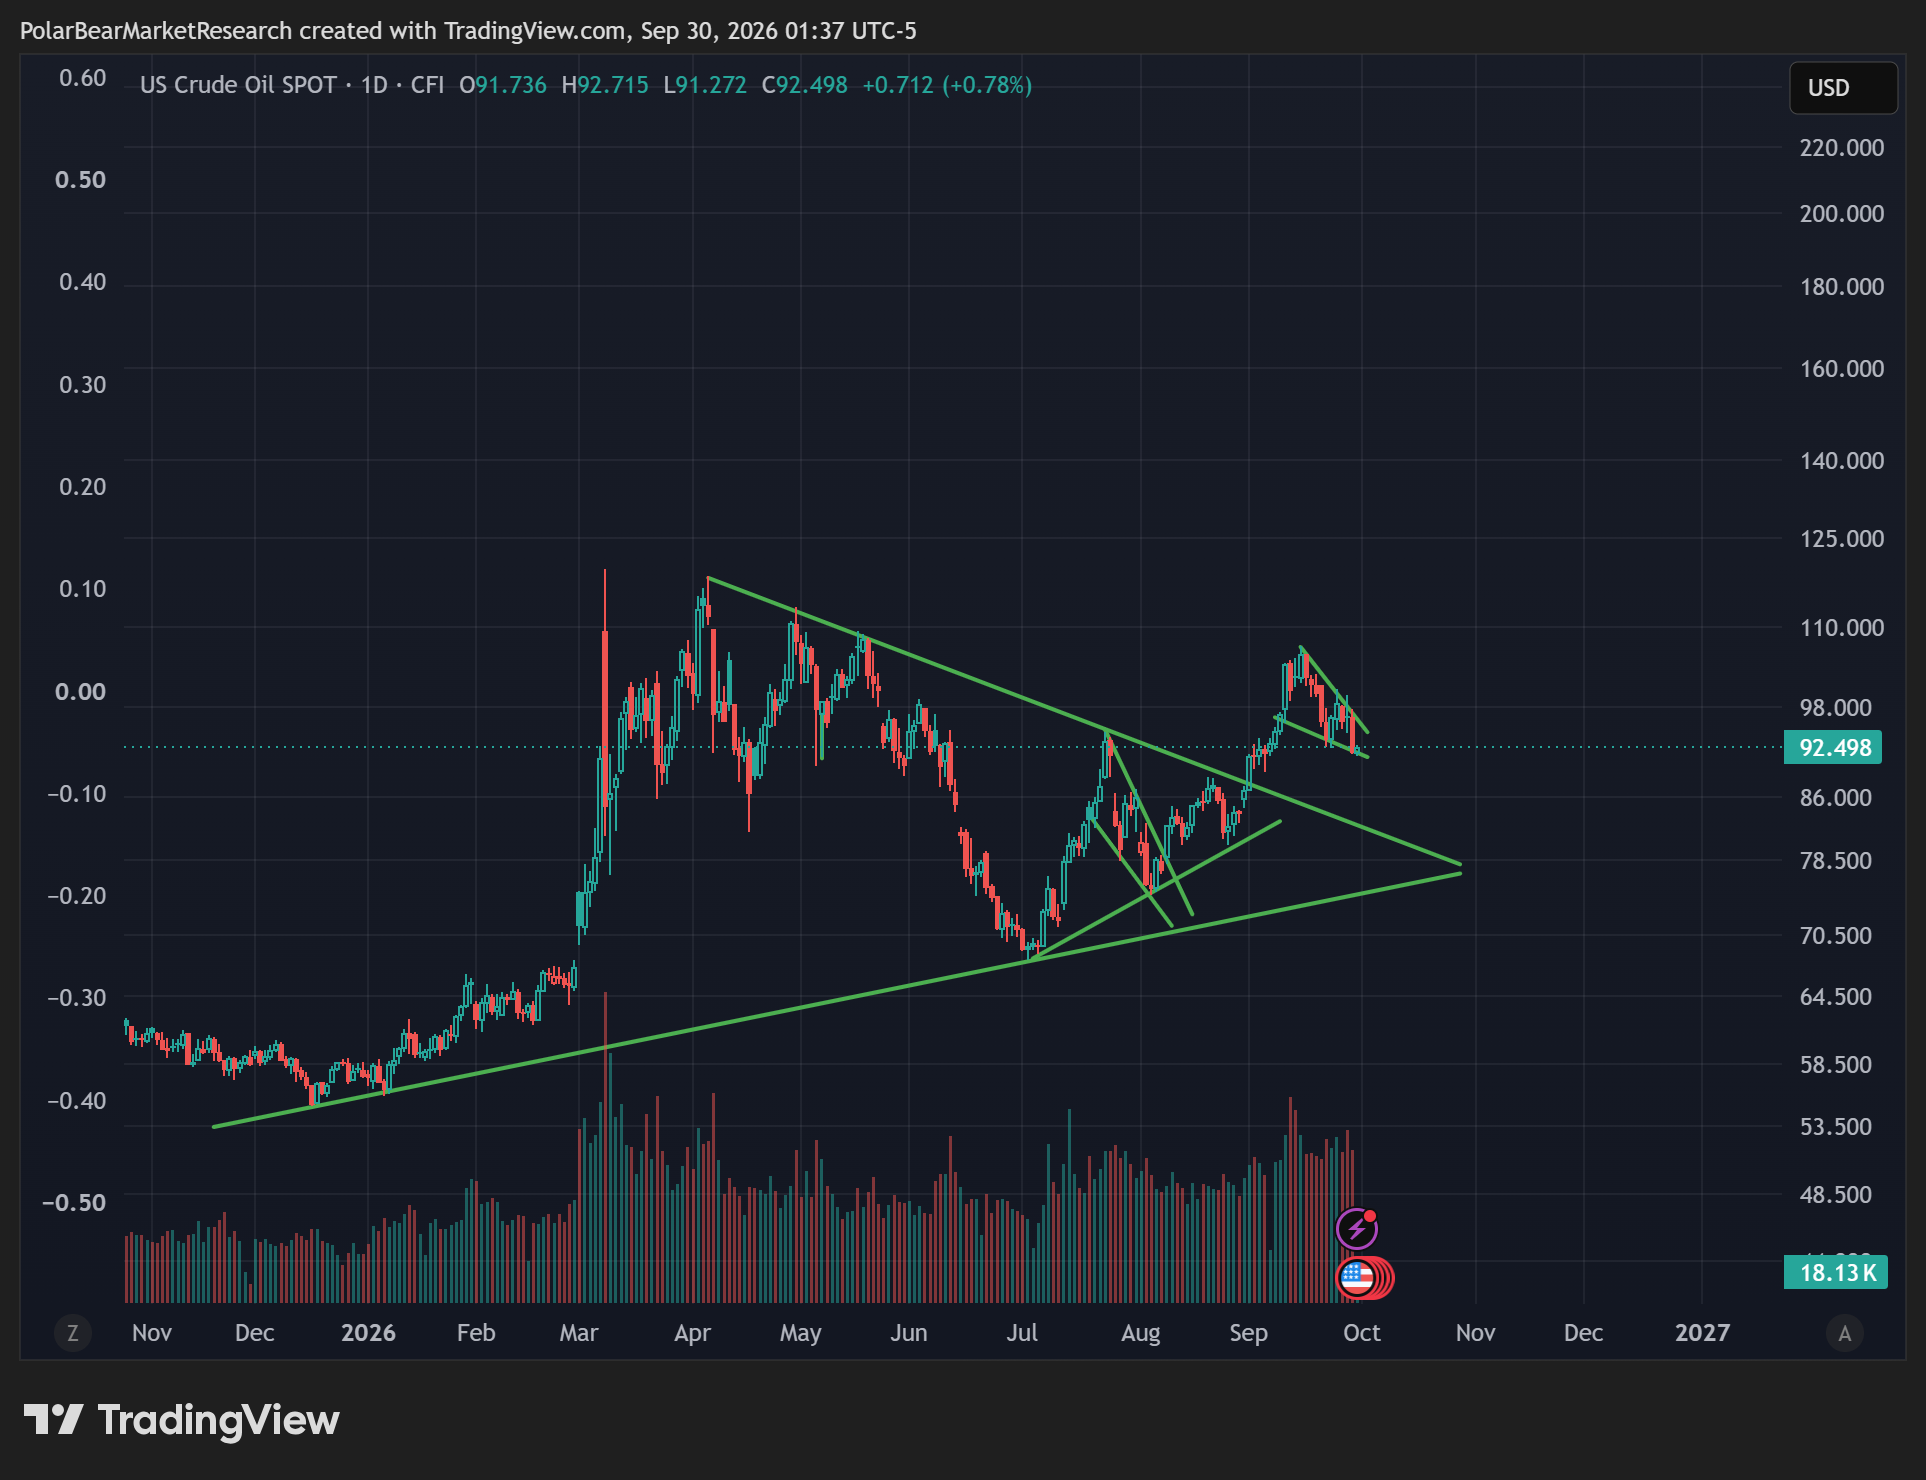
The technical structure for WTI (front-month) remains extremely robust, and the downside case has narrowed, as discussed below:
(Continued below —> The Final SPR Tranche… For Now cont., A Look at the Cyclicals, Data Centers/AI & More)…
