

Good Tuesday evening, MacroEdge Readers & Community,
Today confirmed our CPI expectations. Embedded inflation is becoming a bigger story, and rate odds (and Fed statements) shifted dramatically toward a 99% chance of a hike in December. That much was expected in our inflation outlook. What wasn’t expected was a Fed Governor noting a non-zero chance of a 50 basis point increase at next month’s meeting. I believe that remains an underpriced scenario going into Friday’s PPI report.
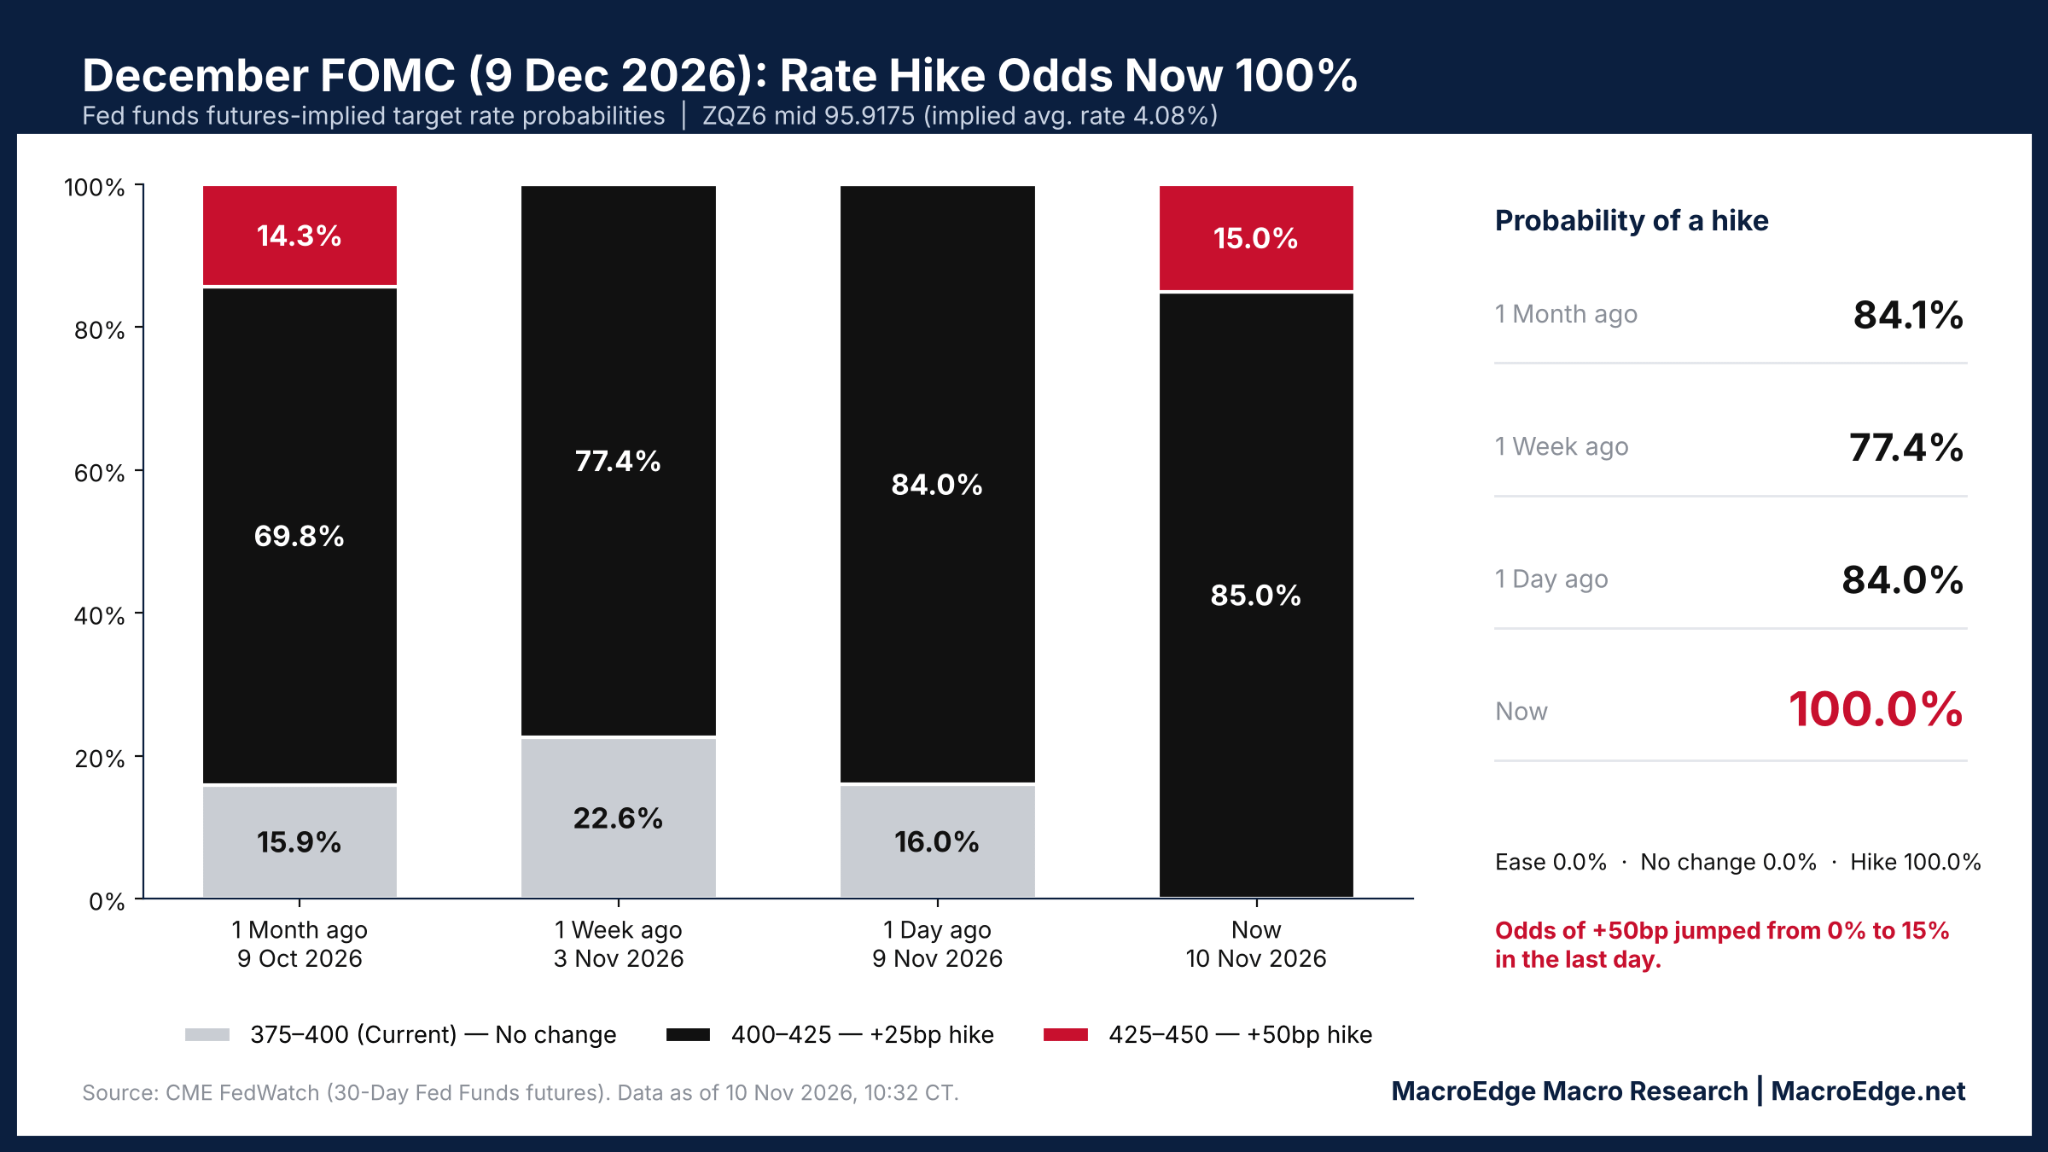
Bond vigilantes are waiting in the wings for the fiscal mistake to continue globally →
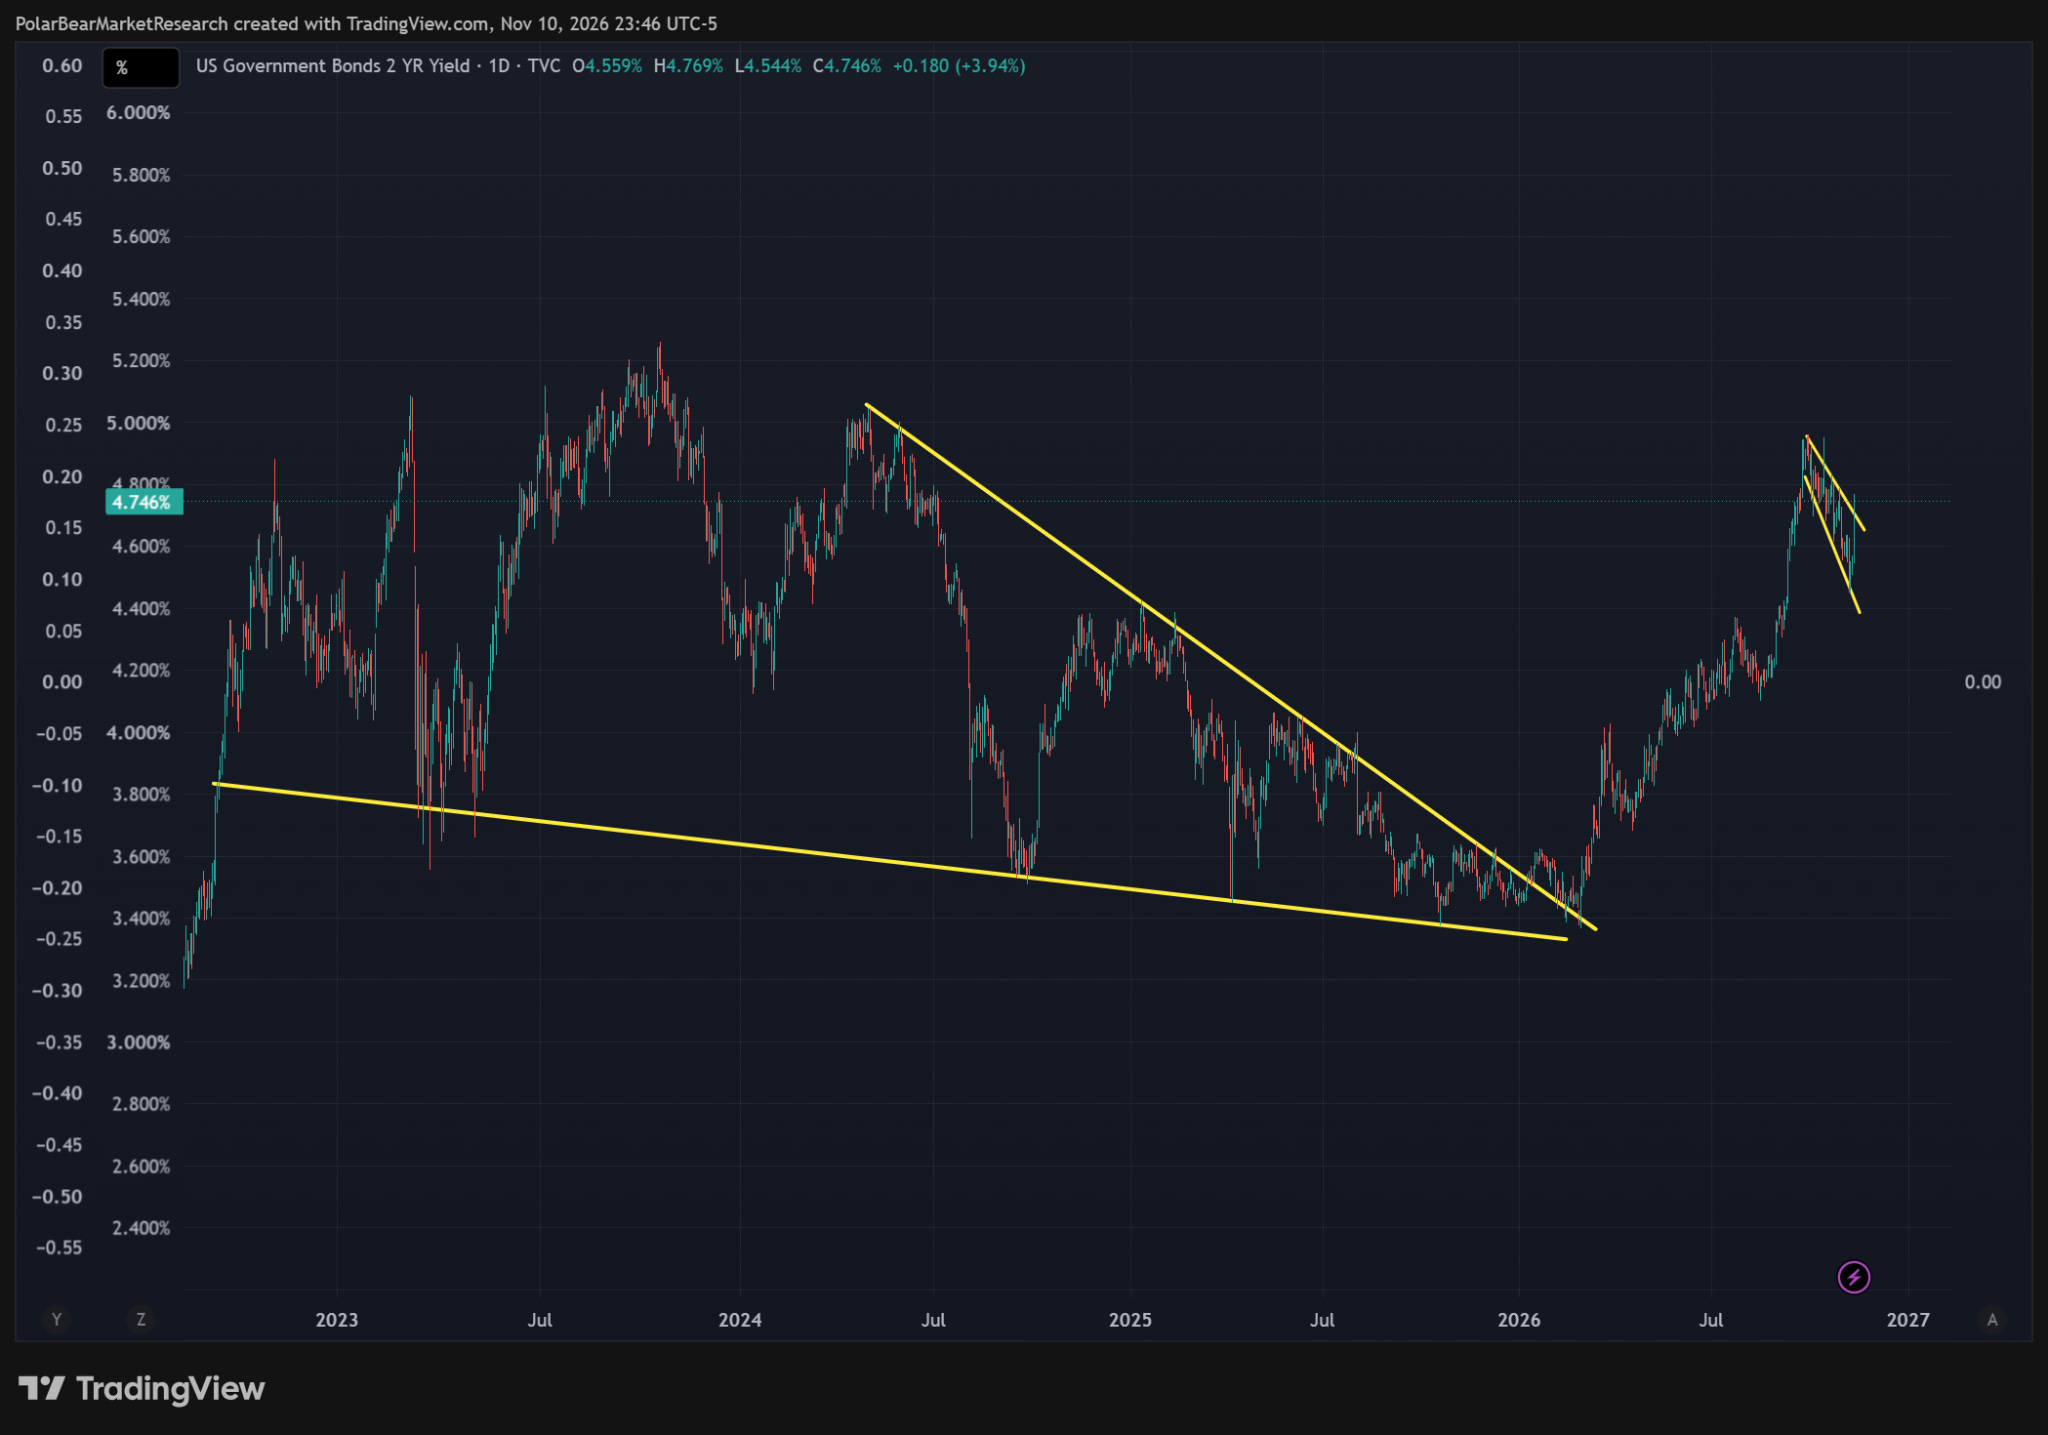
Risks are to the upside across the yield spectrum, particularly on the short-end of the curve.
In the overnight session, we’re floating higher ahead of what will likely be a very thin trading day tomorrow, with the holiday and the bond market closed here in the United States. Strict short-selling regulations in Taiwan have produced a market bounce, and the Bank of Korea has provided short-term support for Korean equities in this bounce. European markets have rolled right back to all-time highs after a very brief touch of the 200-day moving averages across many markets, and it will take more from the bond vigilantes to break the neck there. In the US equity landscape, we’re seeing more concerning signals, especially given today’s inflation reading. As highlighted above, a 50 basis point hike in December is the underpriced scenario going into Friday’s PPI.
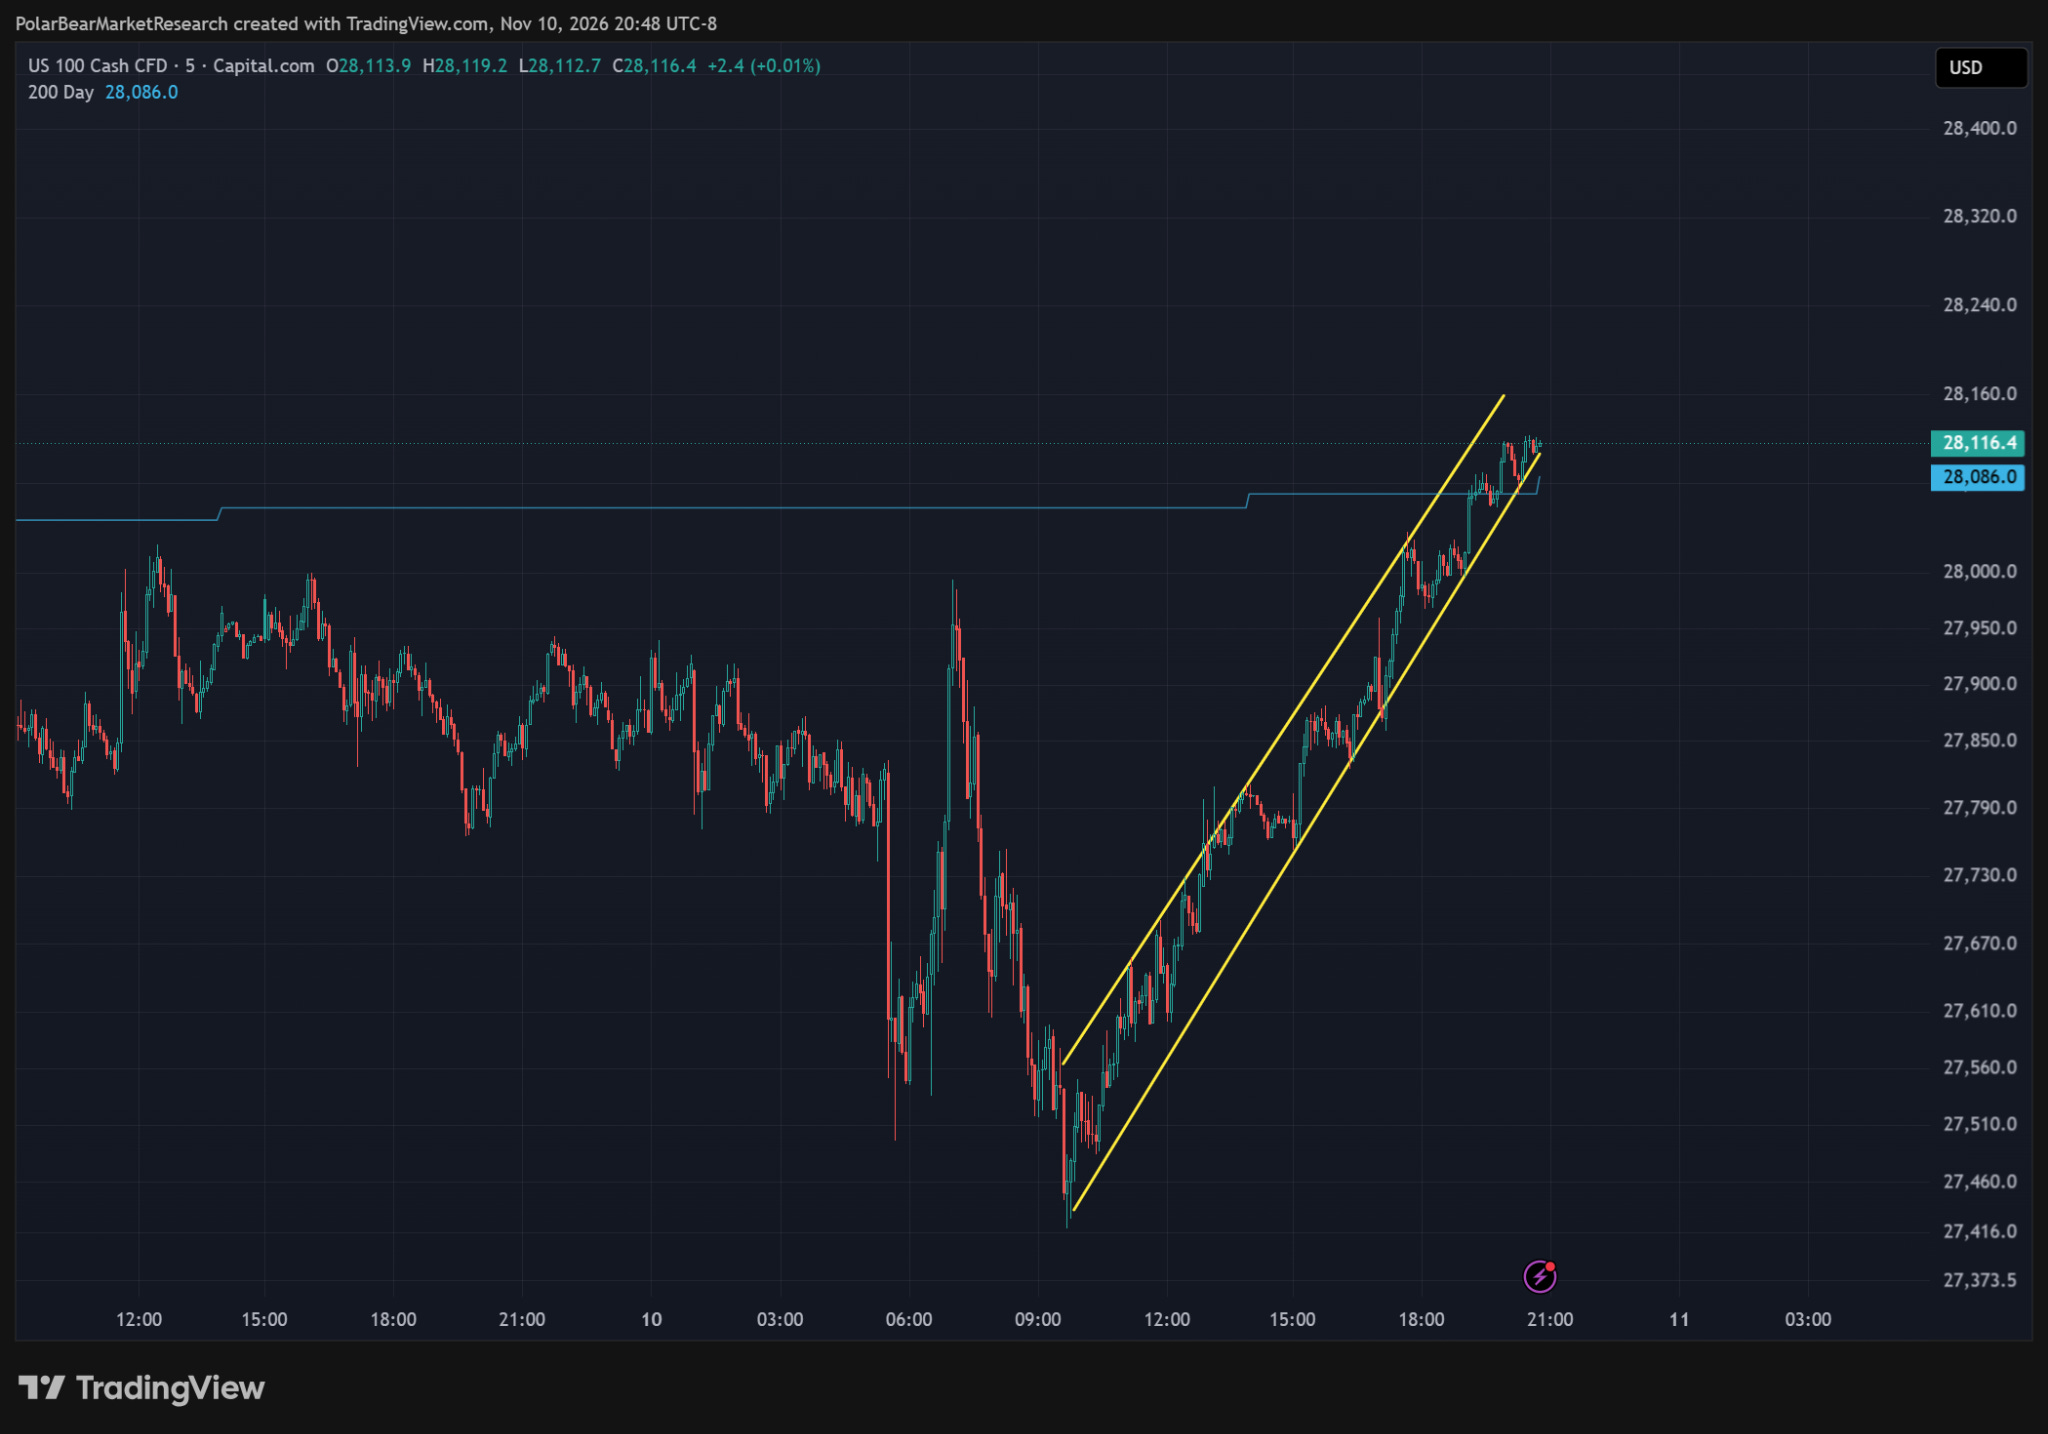
Going into the Anthropic IPO next week, we’re going to see an almost programmatic ‘IPO runway foaming’ to get it out onto the market. I have my opinions on the IPO itself, but there’s this one and OpenAI that they’ve got to get out of the way, and both will be fiercely defended given how interconnected market performance has become. While the S&P held its 200-day, the Nasdaq will likely finish tomorrow’s session right around its own, and whether it closes above or below is going to be a key test of this bounce and of whether we see new highs before the end of the year.
On the war front, things remain relatively quiet, though Iran continues new missile testing and ship attacks have continued daily over the last 4 days. I don’t suspect we’ll see that halt anytime soon, and I still think it’s very unlikely we will hand over control of Hormuz on a long-term basis. Given the shake-ups across the political spectrum, it’s not yet clear what the trigger for escalation in the Middle East may be, but this middle-ground environment seems to be the baseline for the time being, especially as it pertains to the Houthis in Yemen and the Saudis.
Bear with us for the next 6 days as the last major travel sprint gets underway. I’ve knocked out roughly the first 70% of my itinerary with great success, but the next 3 days in particular will be challenging on the logistics front given current scheduling. Reports may come out later than expected, and a few may land in the early morning before the market opens to accommodate this period of flux. I’ll have the full 2027 preview posted here in the next week or so as I finalize the office setup in Arizona, and there’s a lot to be excited about for MacroEdge. We’re currently putting together a refreshed lineup of 6 contributors, and there’s going to be a lot of exciting collaboration for the remainder of the month.
Not yet a MacroEdge Ozone reader? Subscribe below to get all of our macro research, data, portfolio strategy, and more →
On Holiday
Tomorrow is Veterans Day, so the US bond market is closed while equities trade. A holiday in the middle of the week won’t move much, but expect volumes at the bottom of the barrel as the financial engineers keep greasing the gears for the Anthropic IPO.
In this thin overnight session, the Nasdaq has already jumped back into its 200-day moving average. With the listing only a week or so away, expect Bessent to lean on the tape for more.
If there’s one thing I remain bullish on under this regime, it’s inflation, especially as energy prices (covered below) keep posting very large YoY increases off very low bases. That effect won’t start to roll off until March of next year. It’s creating a stagflationary environment, and I suspect we’re listening to the final tunes of this equity cycle here in the United States, particularly in technology, unless the Trump Administration can figure out how to keep letting inflation run white-hot (maybe a resumption of the war to stimulate equities, as one possibility?). There are a lot of scenarios we could drum up, but tomorrow should be mostly useless. The interventions by Asian financial authorities to curb short selling are just part of living in a financially engineered, mostly ‘faux-conomy’ world.
Continue reading below with Ozone access.
