

Good Tuesday evening, MacroEdge Readers & Community,
We’re going to keep the note rather brief this evening, since we have three different reports being released tomorrow:
Portfolio Strategy Note & Commentary
Oil and Gas Research Strategy Note
Oil and Gas 1H Outlook and Roadmap
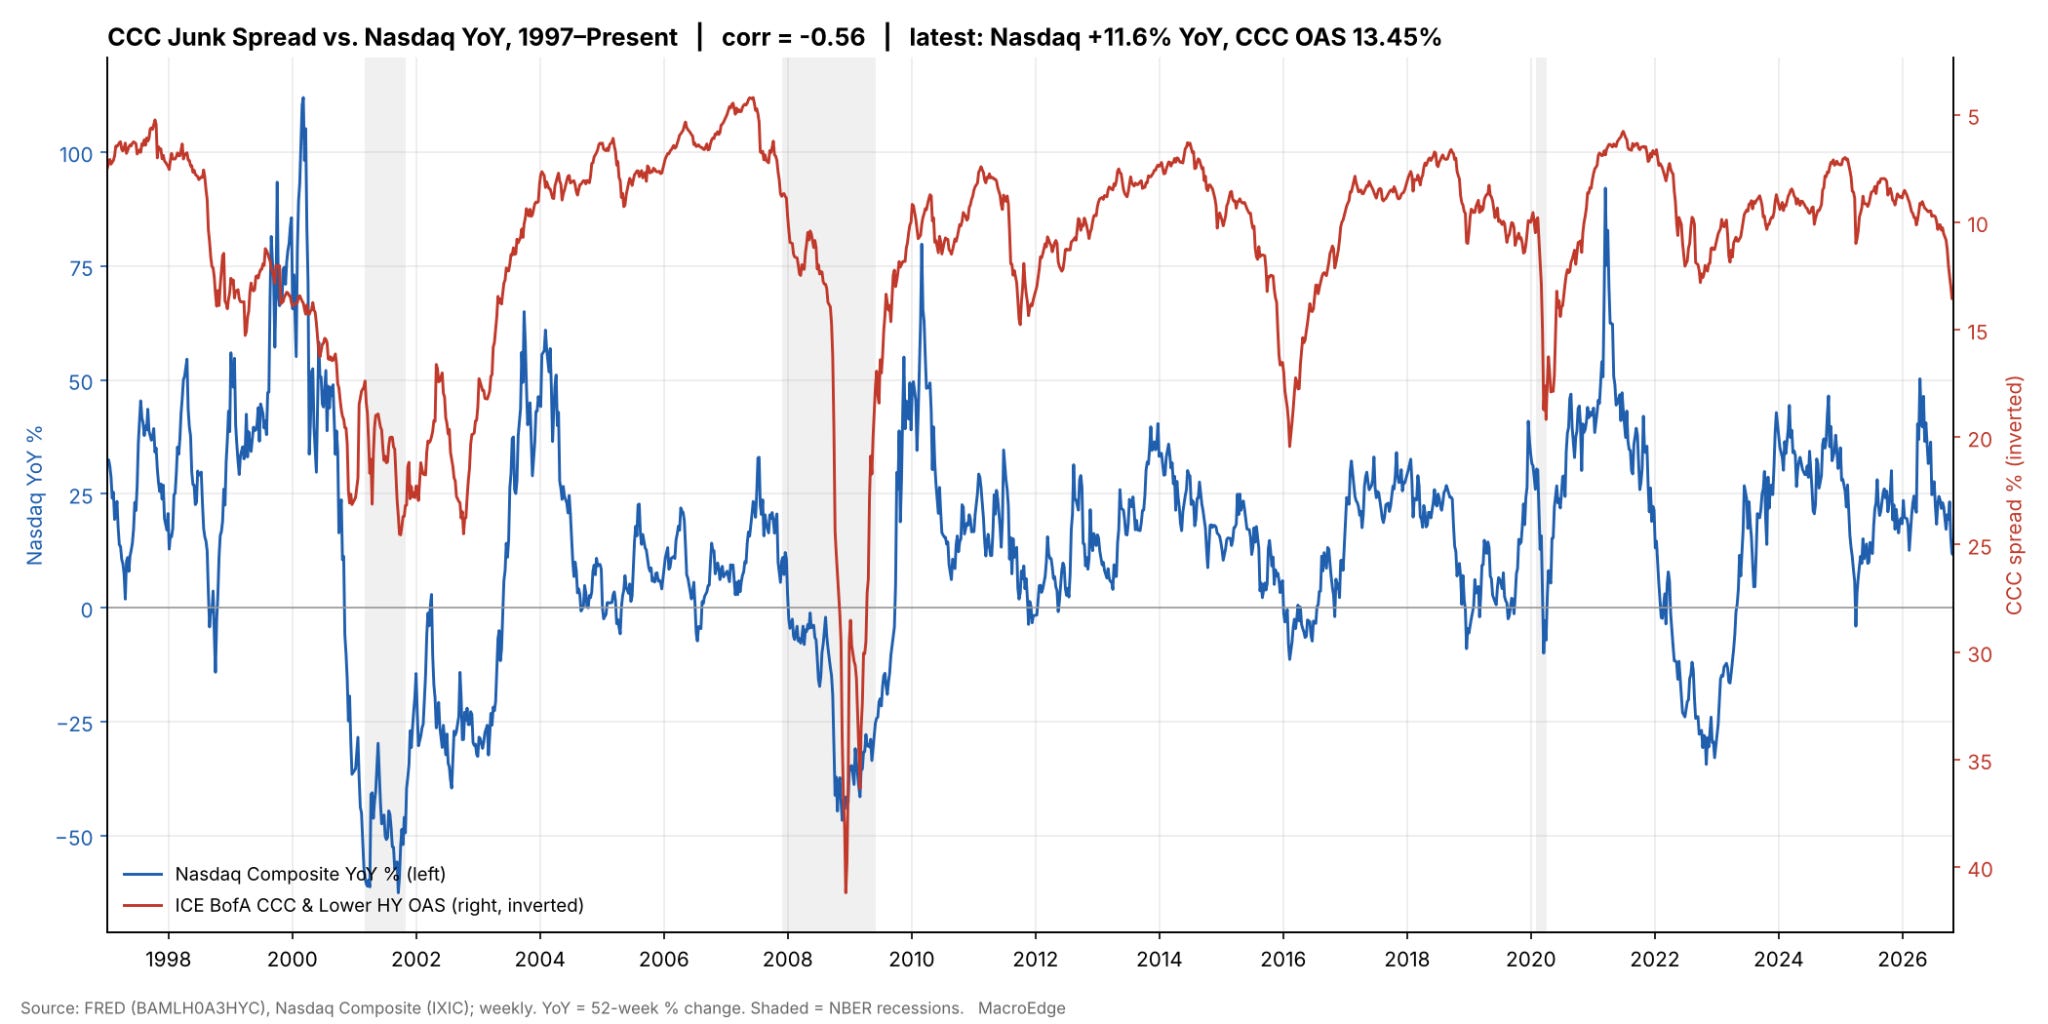
Tomorrow, we’ll hear from the Federal Reserve on its rate decision for October. Based on inflation pressures and inputs, it’s almost certainly a hold, but inflation continues to ripple across our economy, driven by large surges in input costs across the commodities and energy basket. This will show up in the next PCE reading. Even though we’re seeing the first signs of job cuts accelerating again, I still expect the Fed to hike in December. That may very well tighten financing further for the entire AI and data center buildout, which has relied on debt to make it this far and is now relying even more on fantasy financing to try to cross the line into 2027. That trade looks permanently damaged, as I’ll highlight below, with many names likely never to see their all-time highs again as the capital cycle continues to turn. Meanwhile, the CCC/junk bond spread is providing another useful signal for where we stand. Note that when spreads blow out, as we’re starting to see, it usually impacts tech to a significant degree:
For the time being, there’s going to be a lot of window dressing until we make it to the Anthropic IPO… These are companies that really shouldn’t be IPOing at all, but we’ll call it one component of the ‘can kicking’ mixture in this Frankenstein mess of a global market environment. Our GBI did a nice job of detecting a bounce given the short-term oversold conditions, and markets continue to trot along off the 4-hour springboard divergence in technology. Overnight this evening, Korea is up about 7% (nasty bear market rally action), Japan is up about 1%, the Nasdaq is up about 0.4%, and other headline indices are largely flat. I’d continue to keep an eye on Spain, Japan, Korea, and Canada as key guides for cycle timing, as well as on the potential for easing to start in Japan, which may happen as soon as 1H 2027.
Outside of the ‘keep calm’ trade, which will continue to be a distraction for some time, we’ll talk further about the next setup for oil below, look at the latest war and Israeli election details, and highlight the low odds of a Fed move tomorrow. Things will stay very dynamic into the midterms, and the Trump Administration will do absolutely everything it can to protect equity markets and the data center buildout, which remains one of the only things in our economy actually ‘growing’ on paper today. While these data centers are likely to one day turn out to be the ghost cities of our future, in the short run we simply have to capture the opportunities as they stand, especially in energy and scarce real assets (commodities, etc.), and let the music slowly wind down as Jensen carries the burden of finding more and more chairs to keep the game going.
Table of contents for the evening:
Latest war and Israeli election details
FOMC preview
Tuning out the noise
The next setup for oil
Not yet a MacroEdge Ozone subscriber? Upgrade below and don’t miss our portfolio strategy, commentary, data, and much more.
Latest War and Israeli Election Details
Elections in Israel have produced a deadlock, as we expected. This means Bibi will remain in power for another few months until the next election, since it’s unlikely any single candidate will land a coalition.
The Houthi-Saudi conflict is the largest component of the hot war right now, and it looks like GCC members have been making payments to Iran via flights to keep their boats moving through the Strait of Hormuz.
Directionally, oil is close to a max pain point for the elections, and Iran may now escalate through the Houthis before the US midterms.
I suspect peace will be driven by oil prices, which, in real terms, are still not high enough to dent demand in the West (gasoline prices aren’t either), even though we may see acute shortages and diesel prices are at a more concerning level.
(Continue reading below by upgrading to Ozone)
