

Good Tuesday evening MacroEdge Readers & Community,
Tonight’s War Note will be a brief one as we explore the latest Strait of Hormuz dynamics - and continue to monitor for signs of escalation between Saudi Arabia & Ansarallah in Yemen, which is occurring. The war dynamics have shifted slightly in this pre-midterm period, and Iran is using proxies to continue the war in a ‘more’ sustainable war for them for the time being. Sustainable is a bit of a ‘loaded’ term - as the situation is untenable beyond December for Iran given the economic calamity occurring - but that means, in my mind, they will be forced to escalate before that period of time. With midterms in the United States just around the corner, I expect to either see escalation now from Iran & proxies either about 2 weeks out from midterms, or post-midterms in an even more dramatic fashion. While the situation remains relatively fluid, attacks on Saudi infrastructure have not let up - and if the situation devolves into anything like the Russia/Ukraine situation in terms of attacks on civilian and energy infrastructure - the world is in for a ride when it comes to scarcity dynamics.
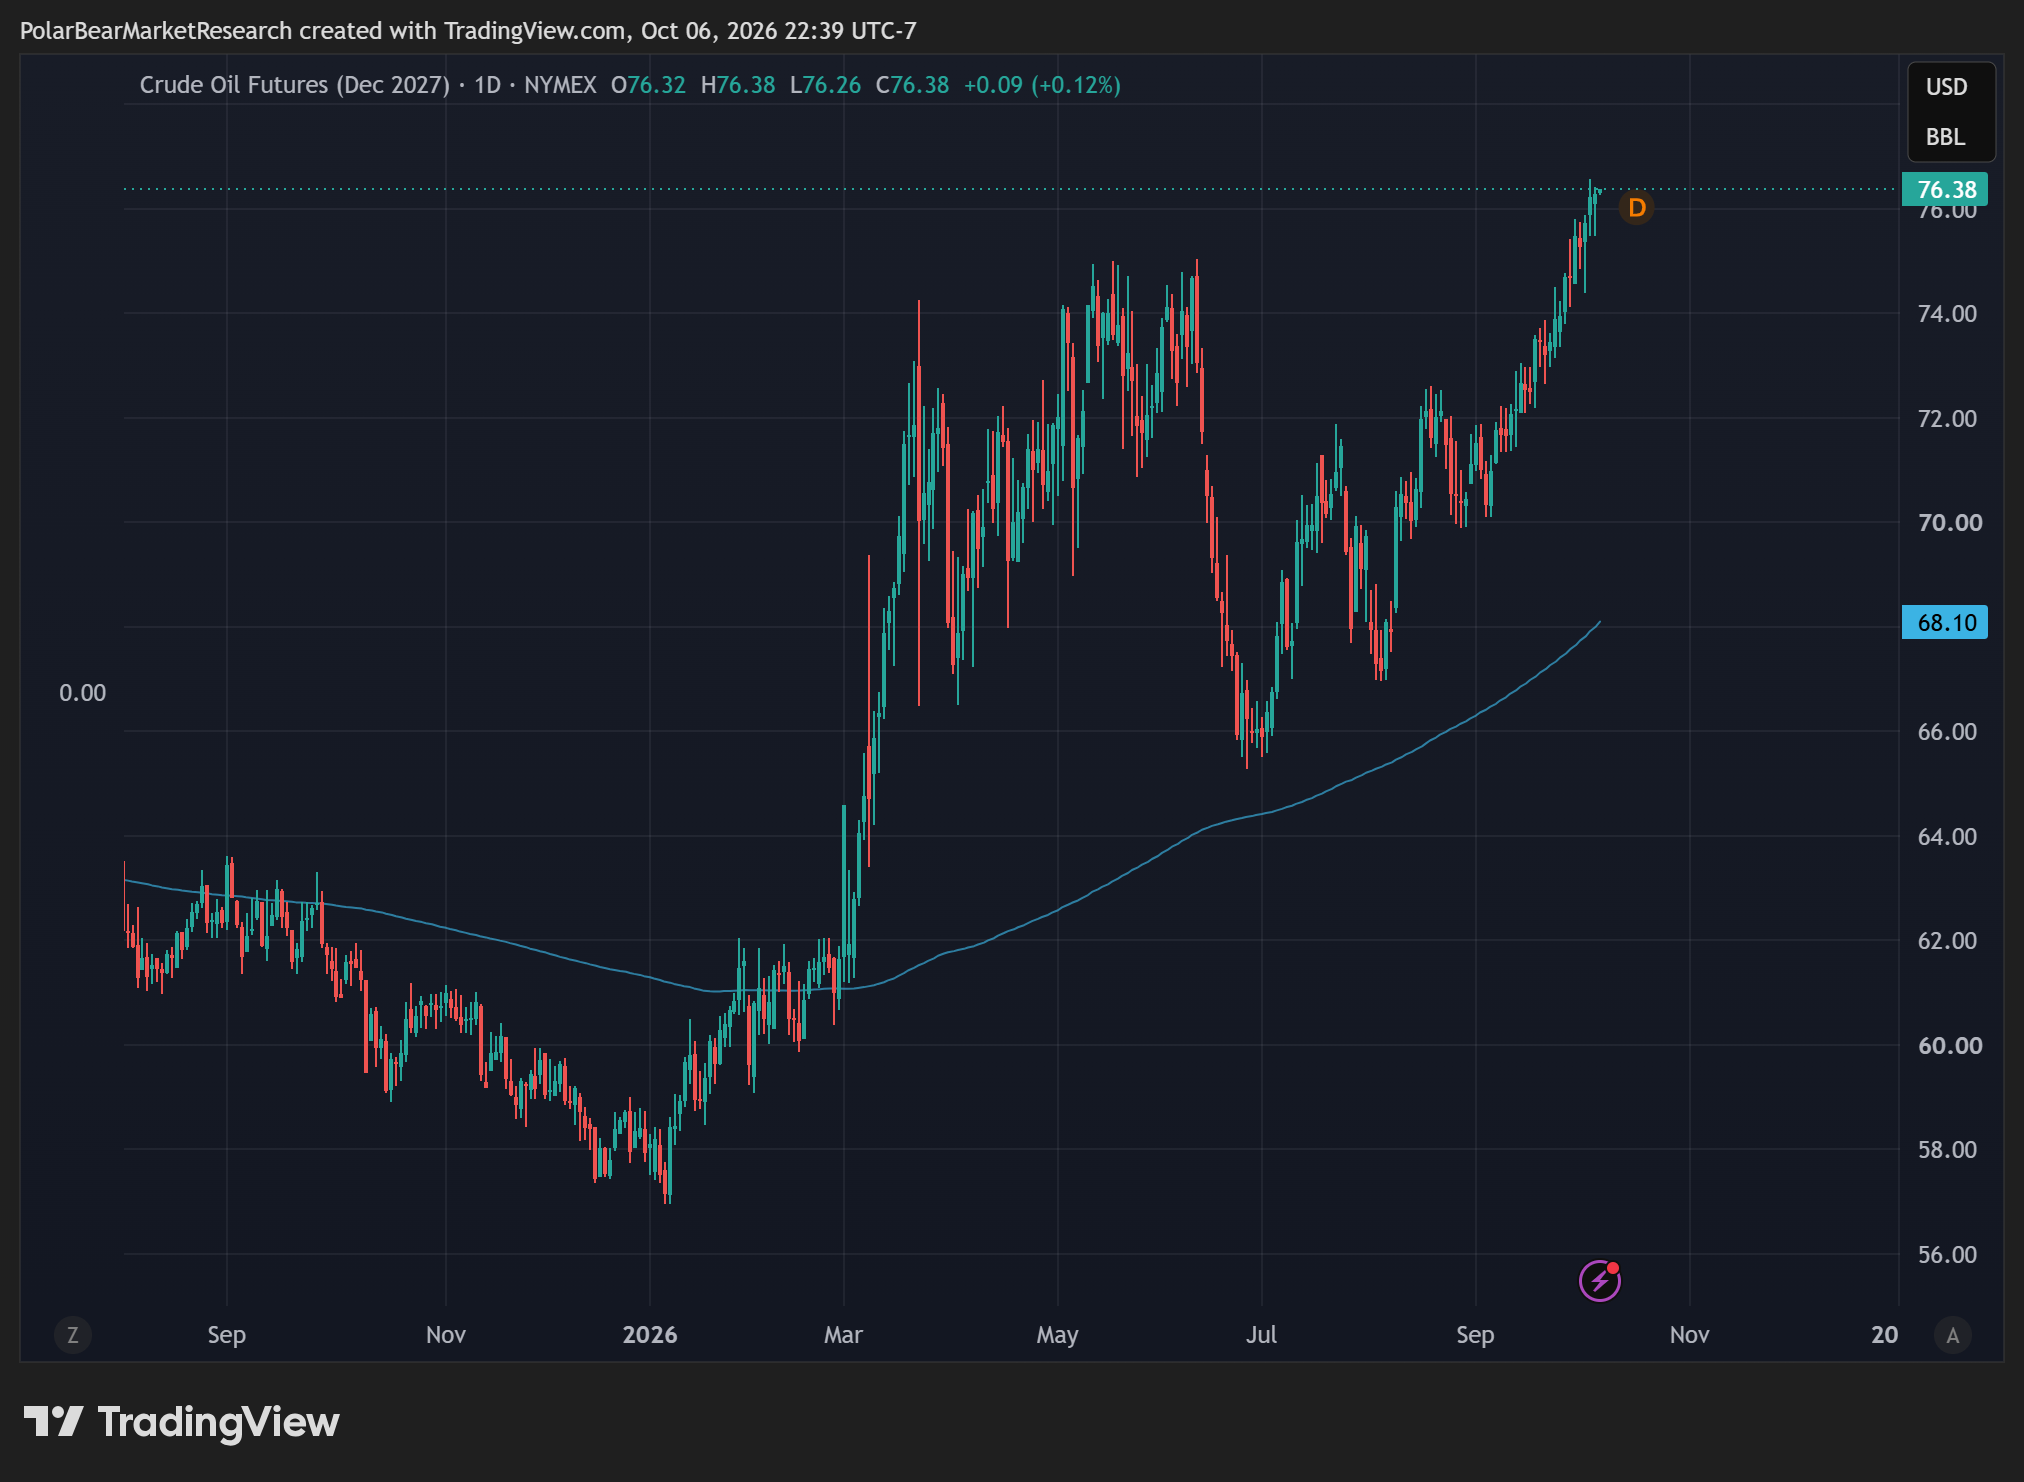
With the US pulling B-1s back from the front-lines, patience is warranted as we continue to tango through this complex pre-midterm and direct war lull period (specifically between the US and Iran directly), and we also see how Iran and the IRGC react to higher Strait of Hormuz flow levels. In the last 3 days or so, we have seen meaningful escalation in the Strait, and that translates to a tighter oil market with a lag, in the future - contrary to the narrative that market reactions will be immediate on this front. In this dip over the last two weeks, I noted a week ago that this felt a little like that pre-May period, and it feels like we’re in that now. From a technical standpoint, there are still some vulnerabilities to the downside, but we continue to march toward a further entrenching of the $80-$82/bbl floor on WTI.
Very little weakness on the back-end of the oil curve is extremely positive for operators, rational explorers/producers, and non-op firms:
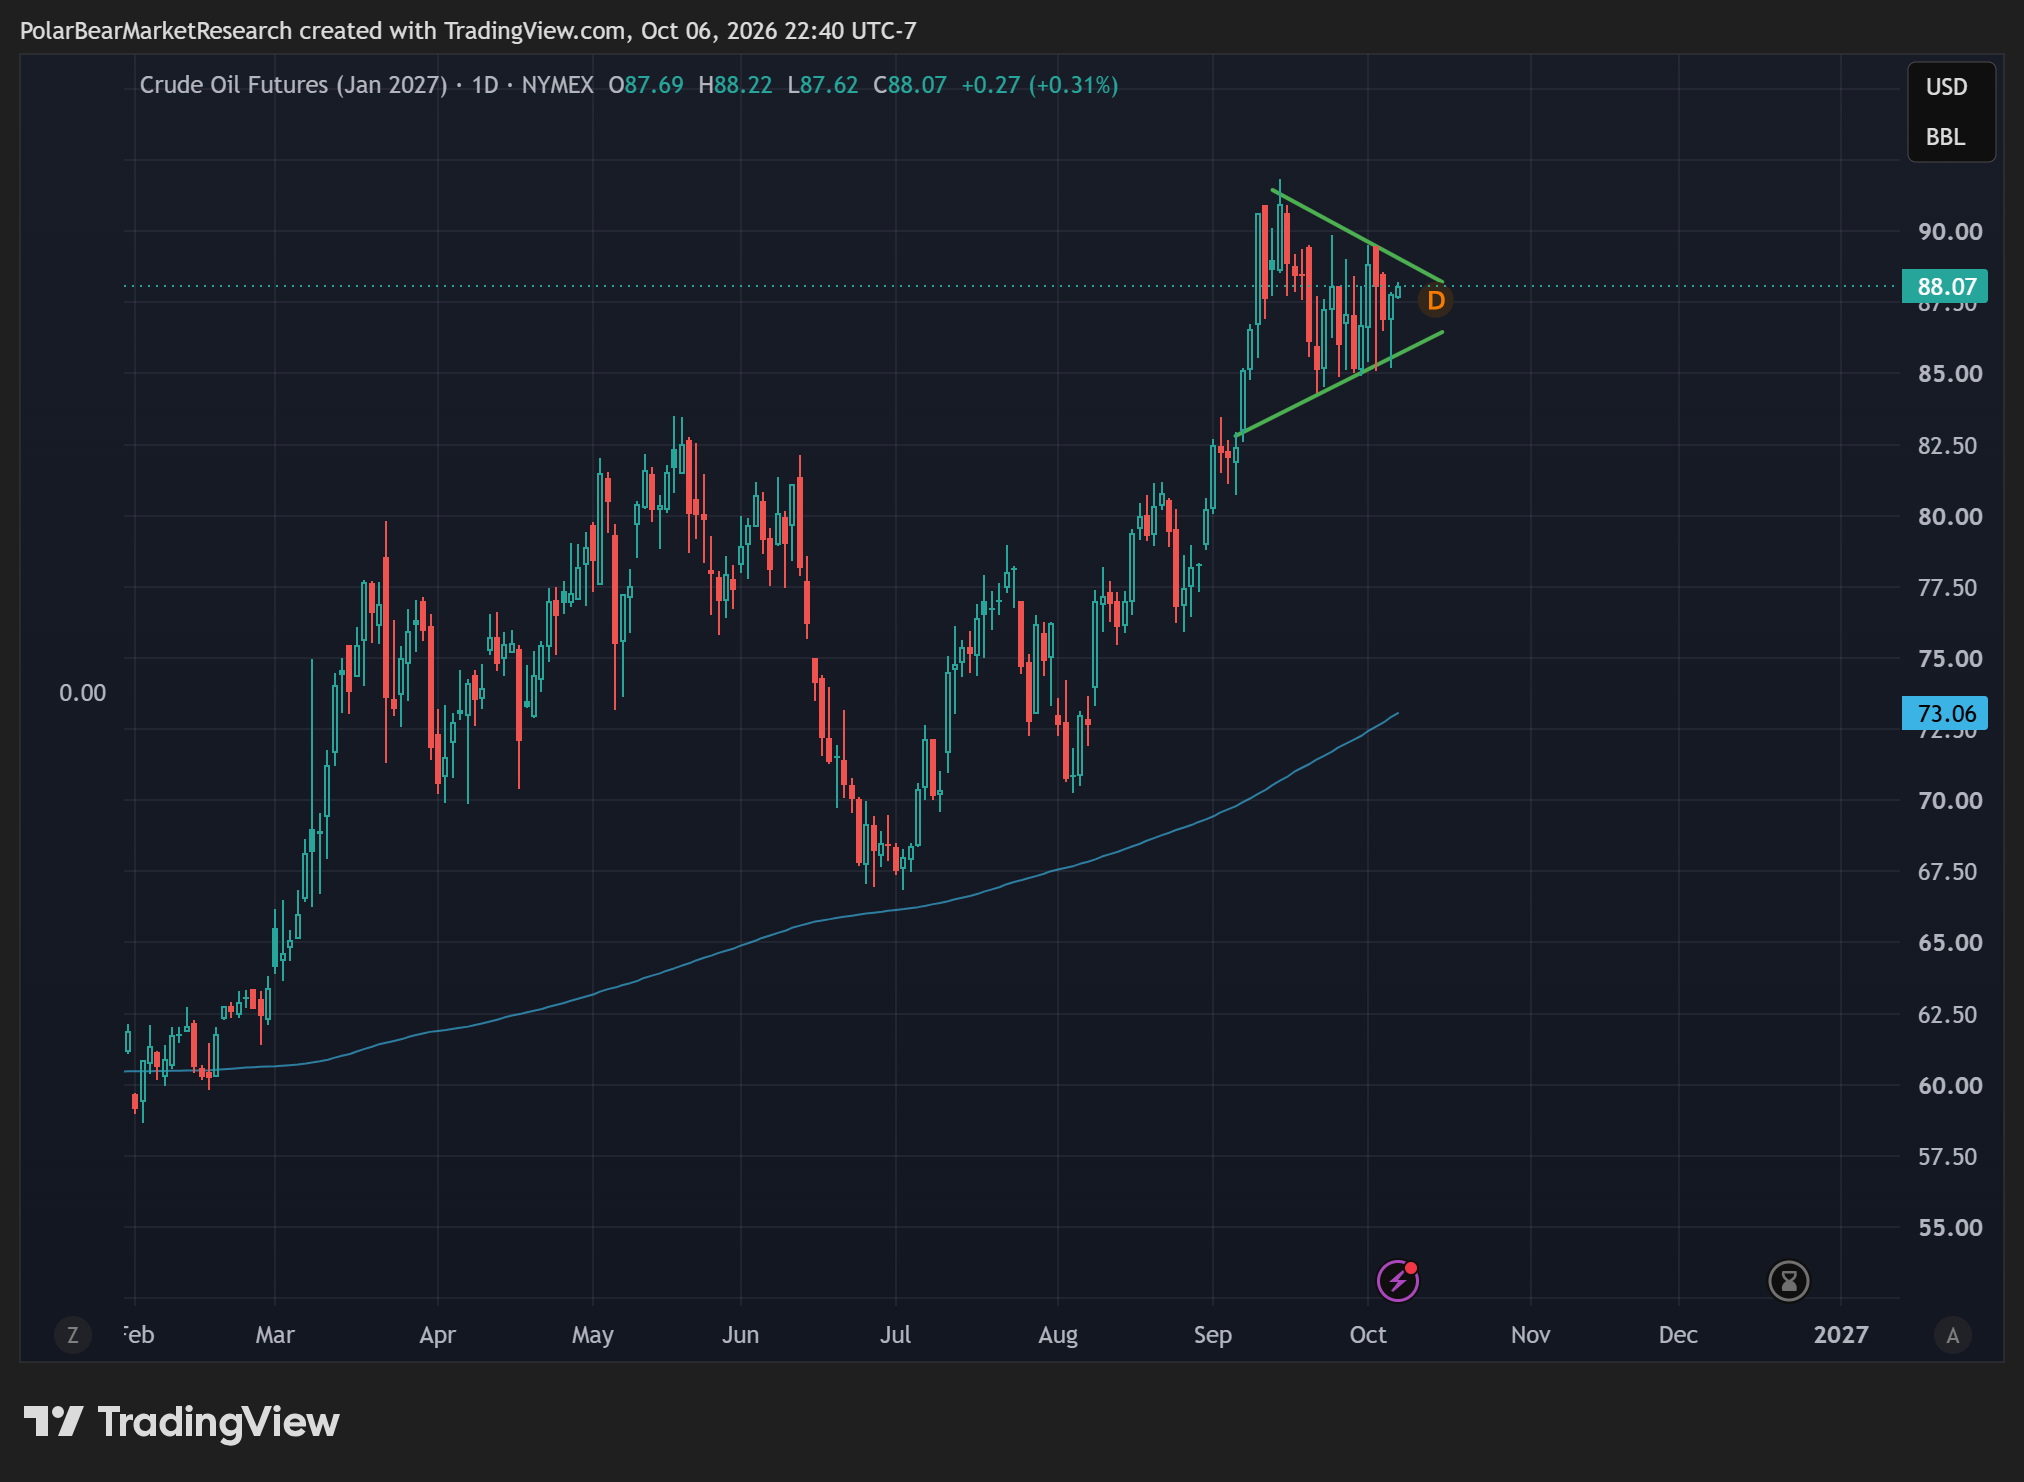
January 2027 also showing really nice strength:
Technology and high beta data center/AI-related equities continue to charge higher on a mandate from the Administration - though I am starting to wonder if we are in the final wave of this crack-up melt-up - on a more cyclical basis. As we know, this year has been relatively unprecedented, and I do not expect them to just fold up on the entire AI-ecosystem bubble, especially with just how much nominal growth is being driven by data center construction right now. Throughout the year our data has pointed to a Q4/Q1 27 rollover in the total construction # - and I think we’re probably close - especially if a blue wave materializes and environmentalism begins to pick back up as a societal theme.
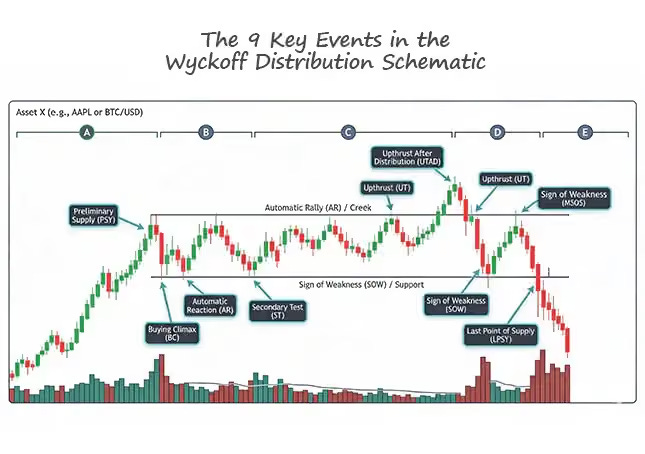
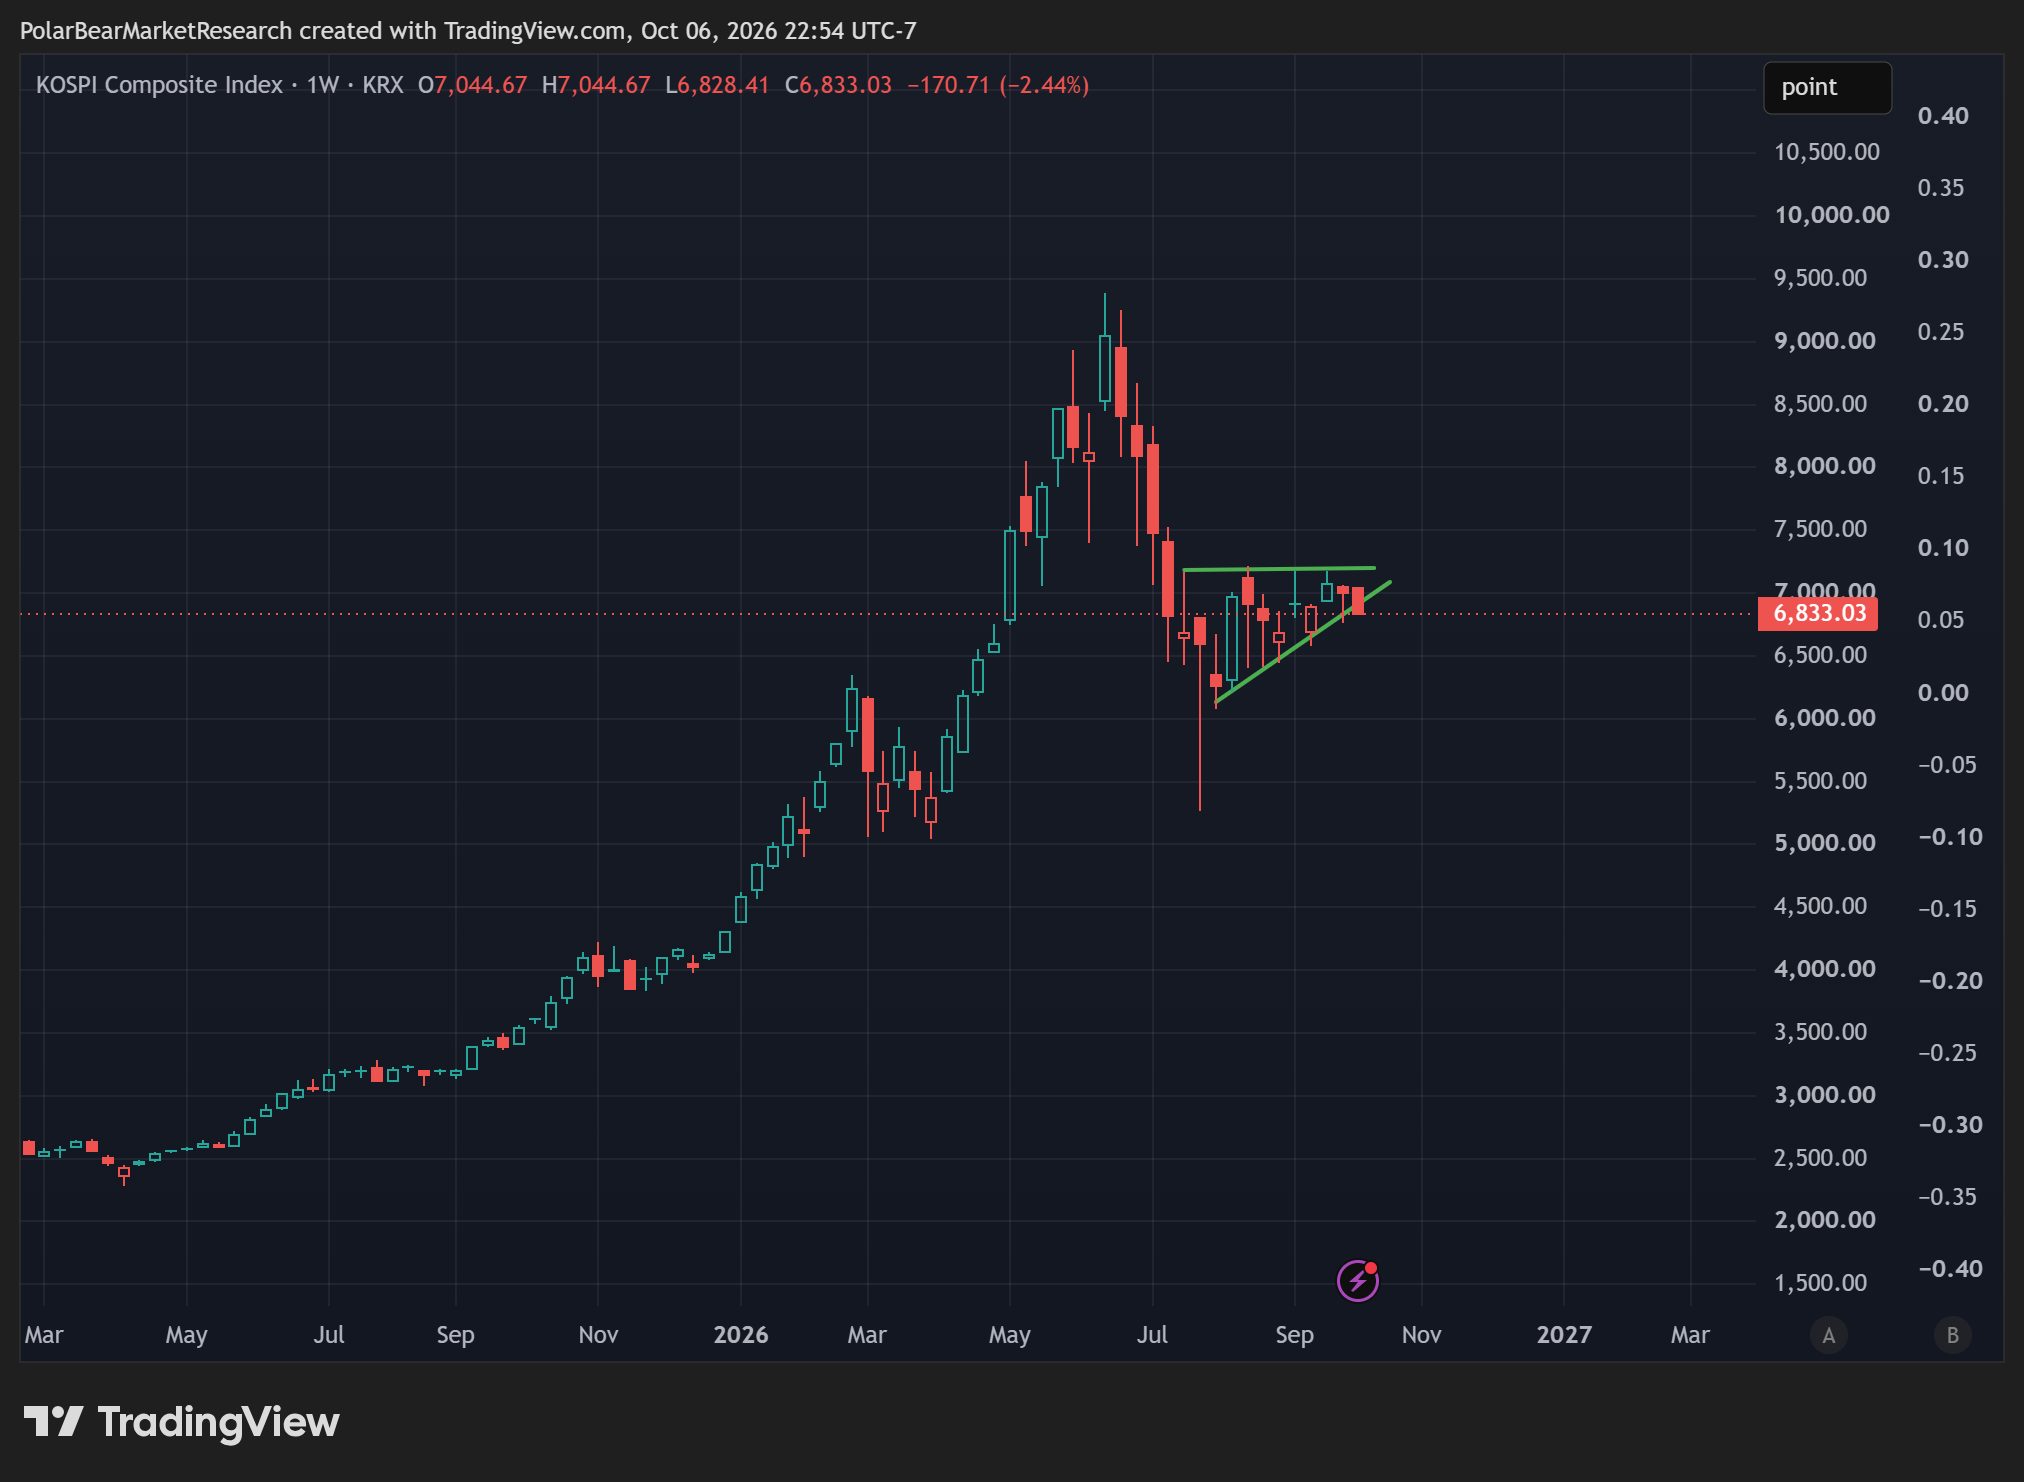
Mr. Wyckoff - is it you again?
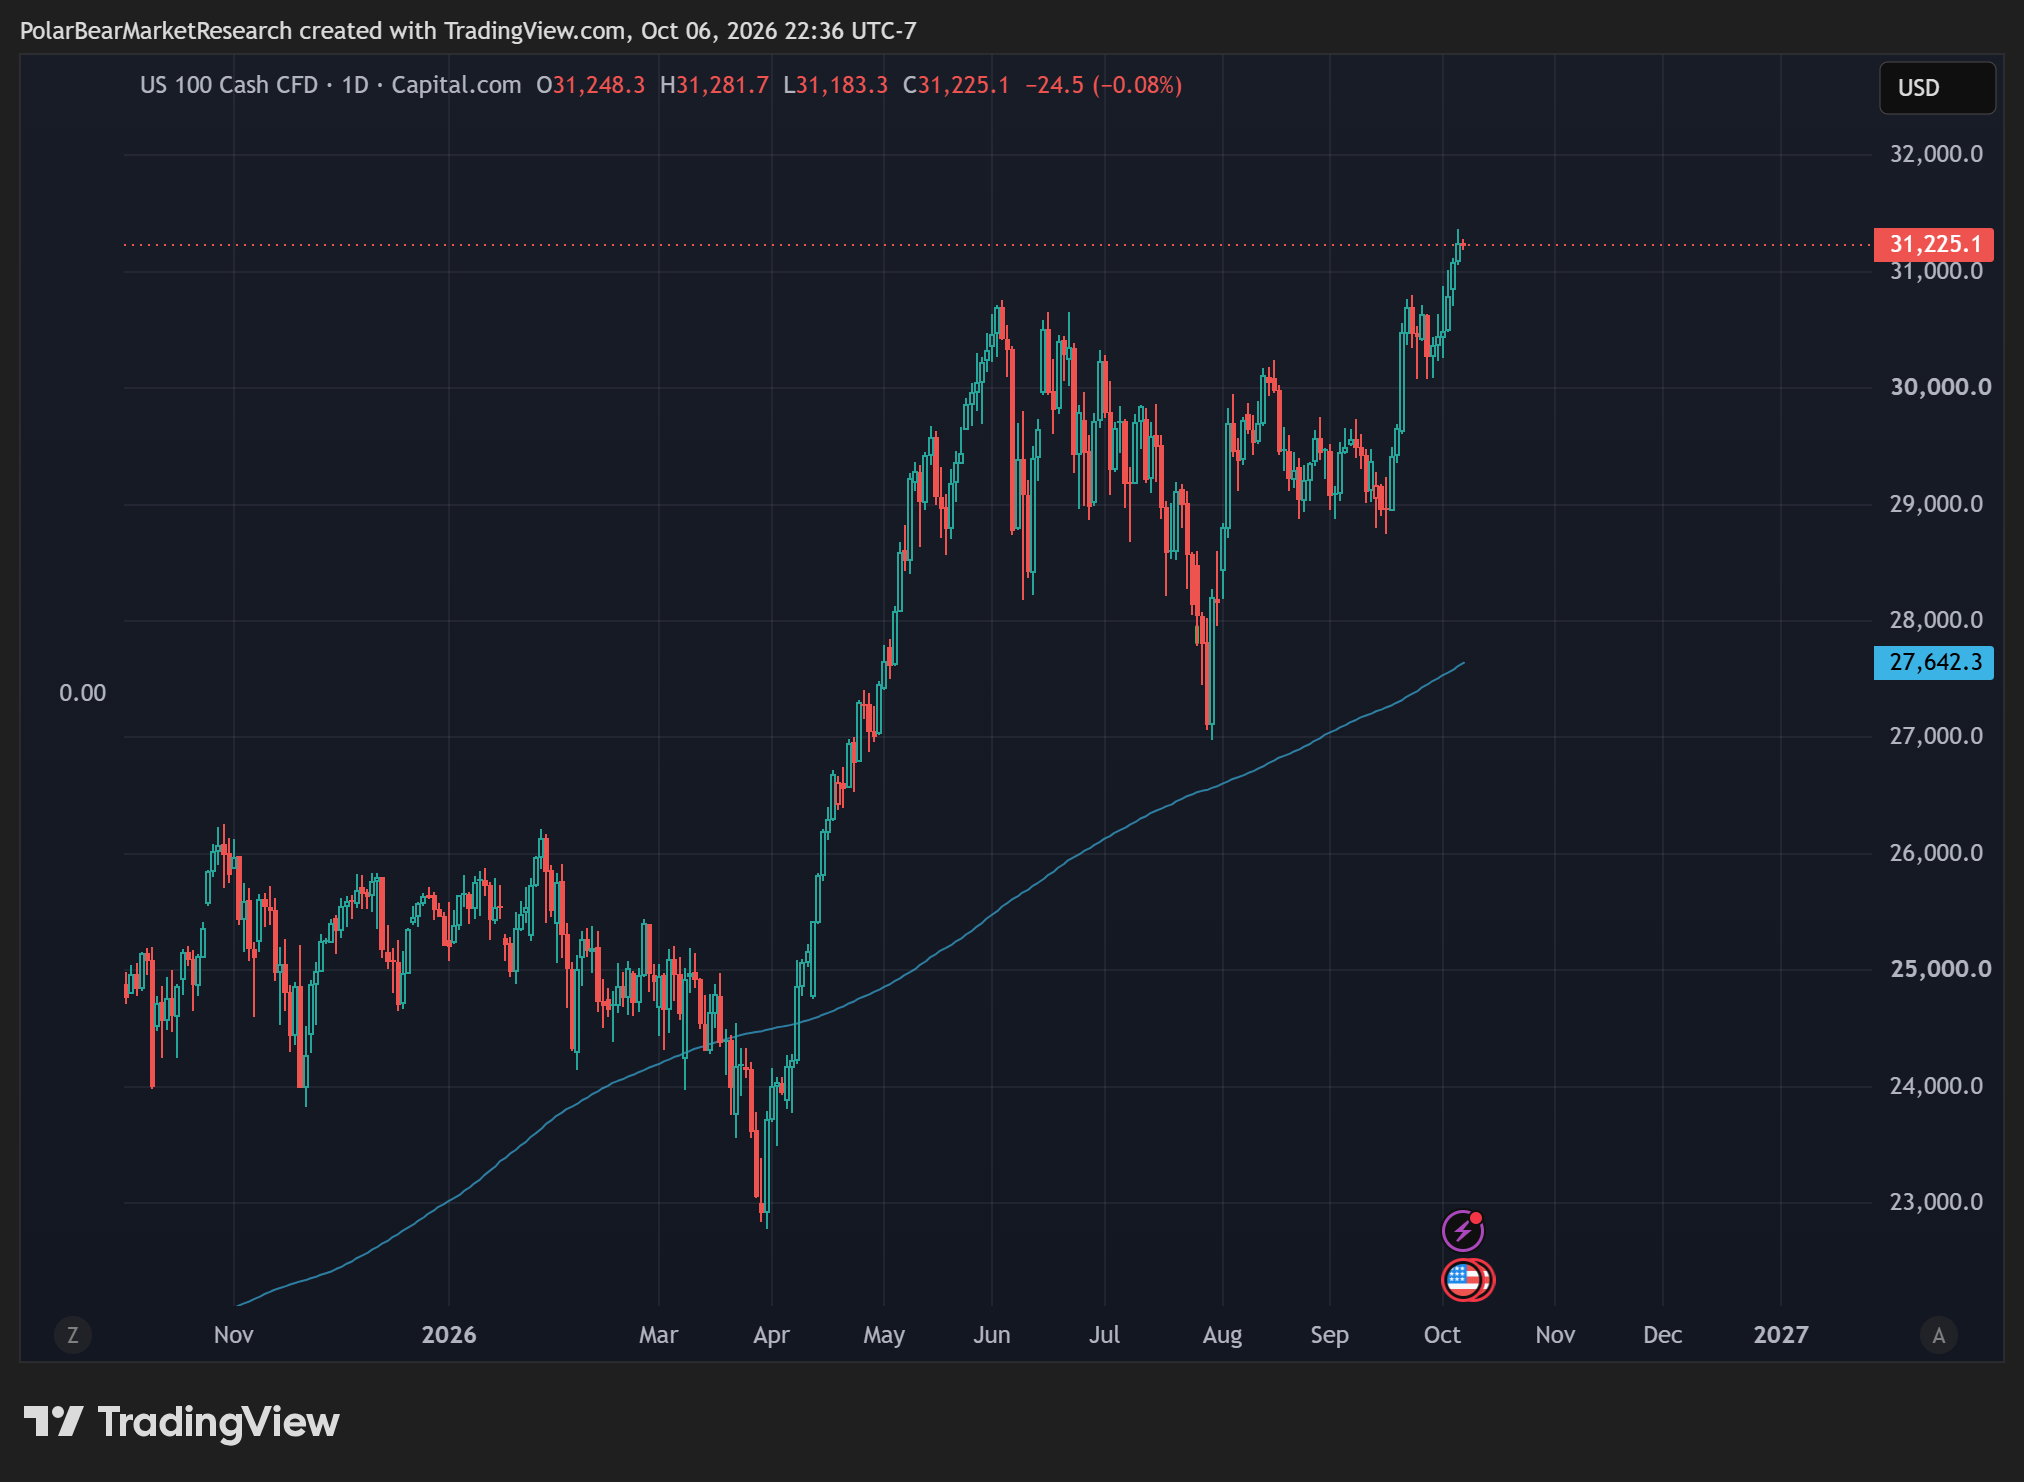
We will soon find out…
Keep an eye on the KOSPI in the next month →
In other news today - the MacroEdge Flagship Growth Portfolio went live through our partner Plutus today. This investable portfolio solution from Plutus allows you to invest directly in our in-house portfolio strategy design - and there’s a second strategy on the way, that I will personally oversee - arriving before year-end or early next year. If you missed the announcement on the new offering, and how it enhances our brand as we start to make this 2027 elevation shift - please see below:
Introducing the MacroEdge Flagship Growth Portfolio

Introducing the MacroEdge Flagship Growth Portfolio
Important Ozone pricing note… on November 1st, 2026 we will transition Ozone from $33/mo currently to $45/mo - reflecting the improvement in our Ozone capabilities and reach across and beyond the Substack platform. Those who subscribe or upgrade before the 11/1 deadline will be grandfathered into the $33/mo pricing. Annual subscriptions will increase to $500.
This evening’s War Note:
Latest War Dynamics
Next SPR Release Begins Soon: Consolidation Continues - Patience Pays
The French Circus
Not yet subscribed to MacroEdge Oil and Gas Research? Subscribe below:
Latest War Dynamics - The Strait and Saudi/Houthi Situation
Escalation signs continue to emerge between Saudi & Ansarallah forces - UK/French Air Forces are providing support, along with US assets
Houthis are likely to play the long game, they have absolutely no reason to over-escalate, while the Saudis do have a time game working against them - especially on the Strait of Hormuz/Bab-el-Mandeb front
Saudis will be flying solo (not literally) until after the US-midterms
Ground war for the Saudis will be disastrous, and they are well aware of this - Saudi ground assets are very weak, and they will rely heavily on mercenaries and rental forces until other nations commit to providing assets
Saudi allies are also smart enough to know a ground conflict in Yemen could be a multi-year nightmare against a highly unconventional force, and the IRGC could be utilizing Yemen as a trap and distraction before their own escalations in November and December
Iran cannot last through December without escalation right now given oil export levels, or they will be forced to close the Strait to levels we saw in August/September
I continue to expect a significant US escalation post-midterms, especially if the results are poor for the GOP - I actually think that gives maximum clearance for the President to go more ‘all out’ - especially on the Hormuz front, which is not open
Next SPR Release Begins Soon: Consolidation Continues - Patience Pays
The next SPR announcement arrives soon from the G7/IEA - and is likely to be in-line with what we already know - 100 million barrels.
