

Good Tuesday evening MacroEdge Readers & Community,
My time is winding down on the West Coast and it’s been a very fruitful two weeks. There are times that it’s nice to step away from the screens, machines, and never ending decisions & to do lists that we all get caught up in, in this ‘technology age’ or whatever the GenZ or Millennial folks might be calling it these days. Next up on the docket is the Permian Basin - and I will be joined by Six & a few others for a combination of on the ground research, discussions, and dealmaking opportunities that we are hoping to unlock in the coming weeks. One of the biggest changes from a social media standpoint in the coming weeks will be a much heavier emphasis on our Substack pages over the X page. There have been a lot of changes to X in recent months, and given our organizational changes that we are undergoing - especially in terms of juggling 5 different balls at once - optimizing where we’re putting out the best content matters much more to me than simply putting out content for the sake of staying relevant in the algorithm. Some of you have probably already noticed my page, @DonMiami3, getting a larger emphasis in the recent weeks…
More will come on some of the changes within the next two weeks as they are finalized.
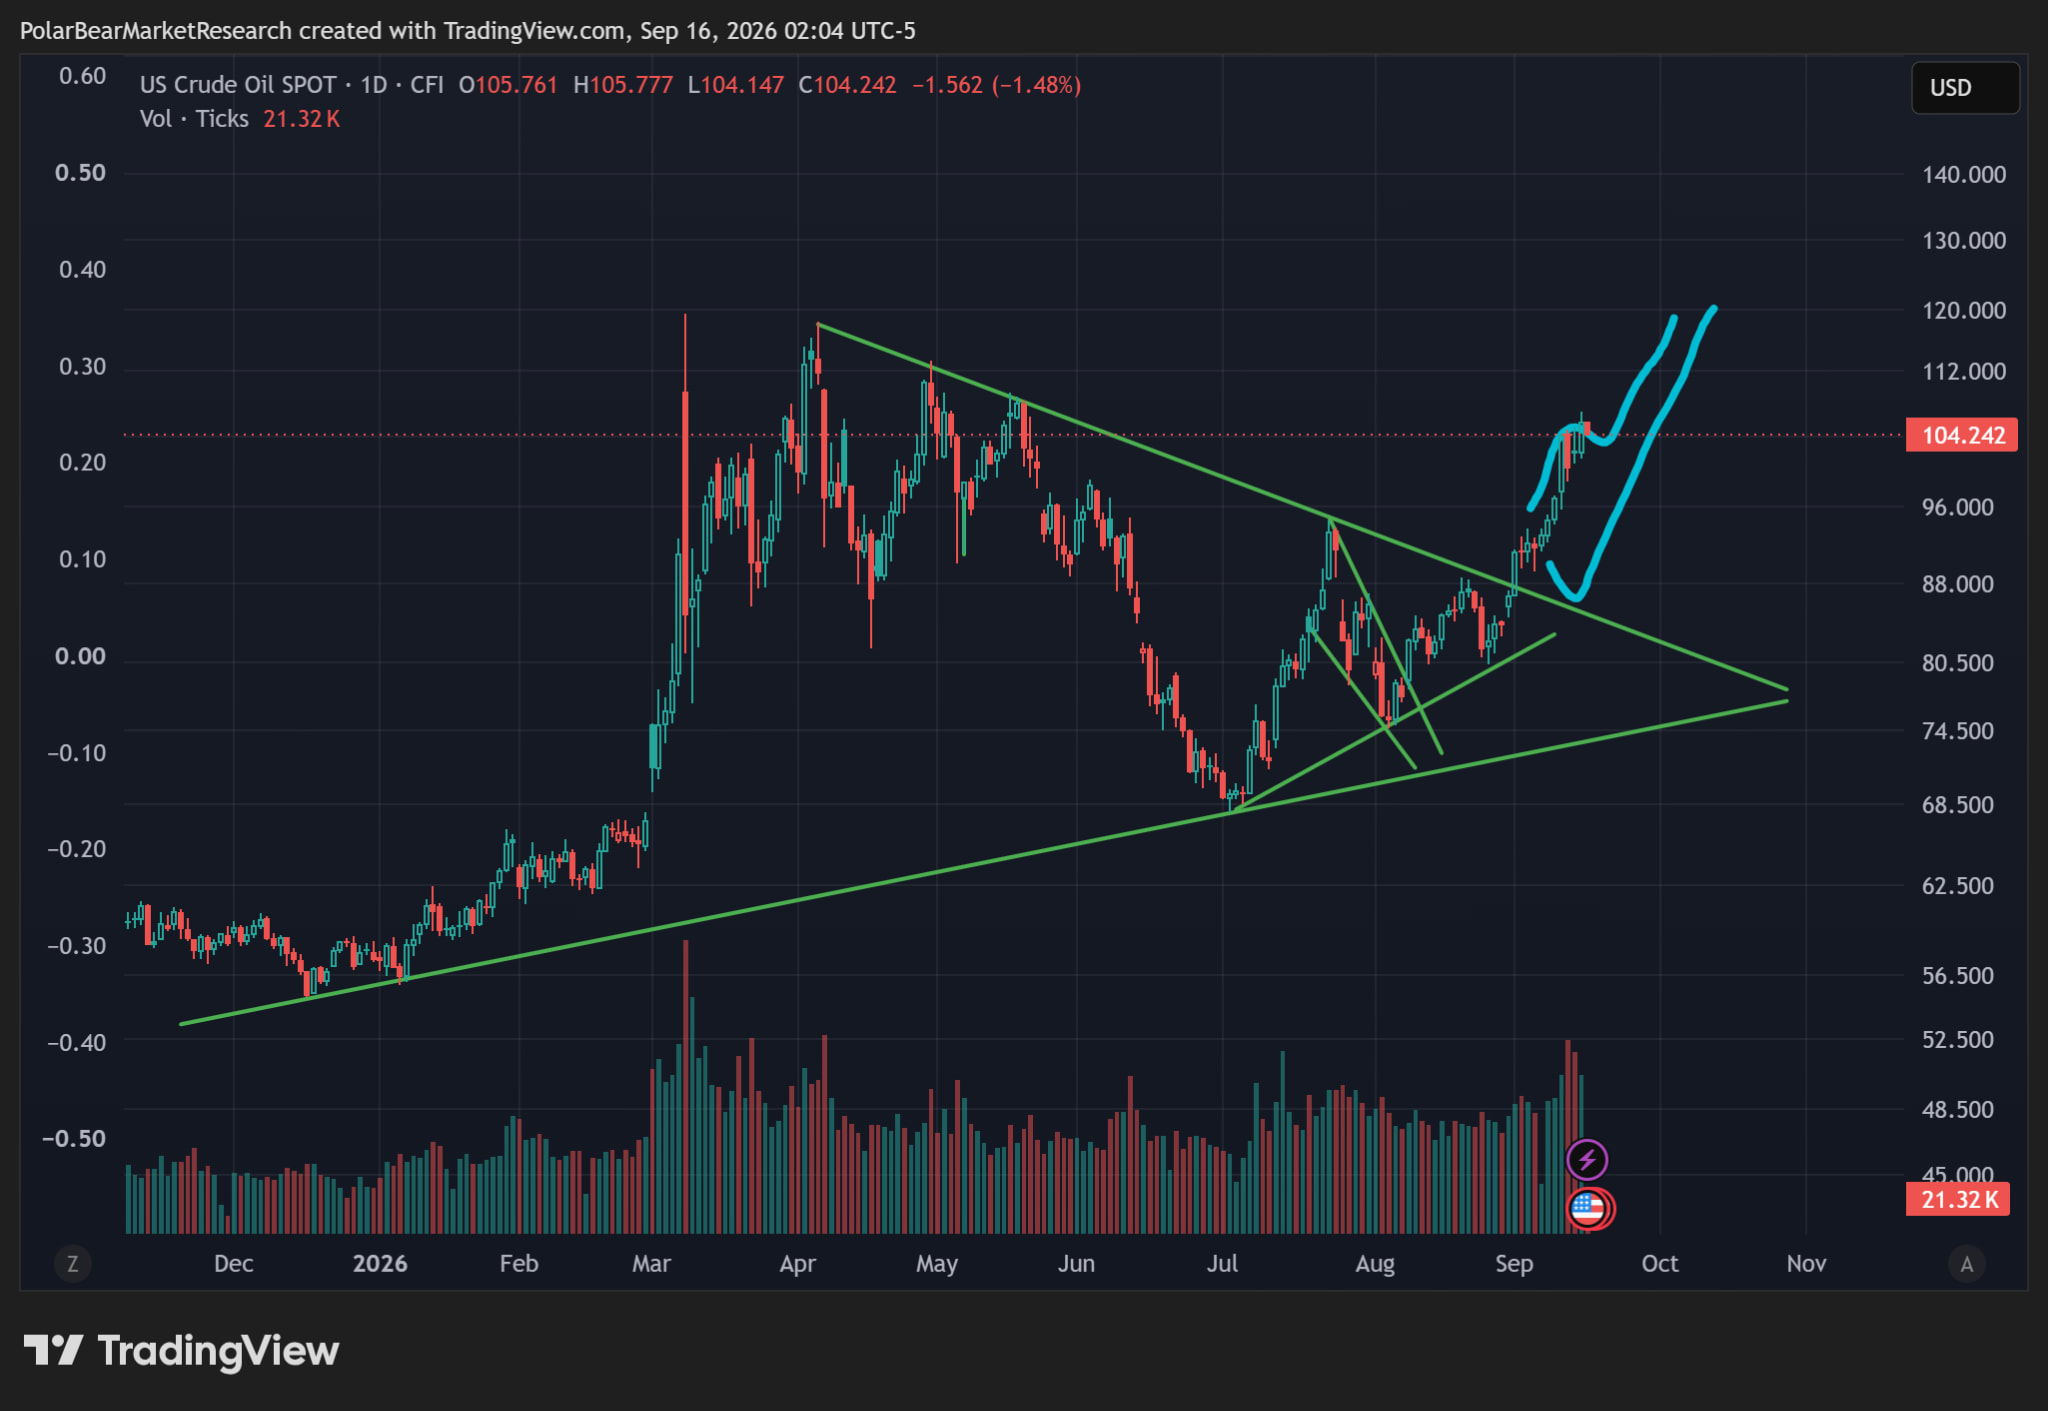
This FOMC meeting is being overhyped to a degree that I have not seen since the 2022 days, with full-style college football coverage expected tomorrow. Regardless of what the Fed does, which we’ll discuss below, the bond market has already done additional tightening that was reflected through movement in bond yields. It’s very obvious (apparently not to PhD economists - that there is a massive runaway fiscal problem that any administration, both sides, seem totally unwilling to address) and with that we’re starting to see said consequences both in the United States - but also around the globe. Couple that with the worst energy shock in 20 years, and there’s a recipe for higher inflation (CPI likely running about 4% YoY right now, don’t trust the Truflation figures)... While we may still see brief intermittent pullbacks on front month WTI, such as back into the mid-90s briefly, directionally there are many reasons to think that this cycle is going to be a structural change shifting to a higher base price level for a long time, rather than a cycle where the price move is short lasting. What we’ve seen thus far is still not enough to cause demand destruction, and relative to the supply situation, just about everything in the petroleum products space is still underpriced on a nominal basis.
In the Oil and Gas Strategy Note tomorrow we’ll discuss what I call ‘the final TACO’ and when it may be announced.
This evening we’re going to briefly review the report schedule for the remainder of the week - in which we’re going to cover a lot of ground previewing the upcoming Permian Basin visit. Then we’ll look at the diesel and refined products situation and preview the FOMC decision tomorrow, as well as discuss likely outcomes.
Not yet a MacroEdge Oil and Gas Research subscriber?
Upgrade below:
Report Schedule for Rest of Week
On the Ground in the Permian Basin, Oil and Gas Strategy Note (Wednesday)
Portfolio Strategy Update (Wednesday)
Welcome to the Permian - Midweek Macro Note & FOMC Recap (Thursday)
Saturday - Permian Thoughts Part 1
Diesel and Refined Products Tighten Further
Front month WTI continues to act as expected, with a higher base right now in the mid-90s at current Hormuz flows and inventory levels:
Gasoil has almost tripled this year, and I’d like to see consolidation before the next leg up - though that may be very brief:
