

Good Wednesday evening MacroEdge Readers & Community,
As we settle into this new cadence with these Wednesday Strategy Notes - Six & John are at the helm here for Ozone, and I will be providing the Oil and Gas Research Note. We’ve had a successful roll-out of our Flagship Portfolio through Plutus - and if you haven’t yet checked it out - you can do so here: MacroEdge Flagship Growth Portfolio.
It’s been dynamic week thus far and we’ve had some notable volatility out of Asia - that we’ve discussed extensively in the last few months. Asia (namely Korea) continues to get pulverized, and I very soon - especially given the pre-midterm period we’re in - expect emergency measures to be announced by foreign governments to quell drawdowns. In a world more reliant than ever on equity markets melting up and to the right in the face of declining real hourly earnings for the lower 90% of the ‘i’ - I’ve strongly taken to adopting Dr. Burry’s approach of seeing the opportunity as it presents itself, with healthy pragmatism, and then exploiting them. While we cannot change or alter our addition to inflation or equity market interventions, we can continue to get a better grasp and understanding of all of the complicated global macro dynamics, and position ourselves accordingly - whether it be through portfolio decisions, business decisions, personal decisions - the list really goes on & on.
Hopefully you are all having a great week & the second half is even better. Stay tuned for the Oil and Gas Research note out shortly.
Don
Portfolio Strategy Update - 10/14/2026 @SixFinance
September CPI came in hotter than expected and bonds sold off hard before climbing throughout the day. The correlation of yields up stocks up is showing initial signs of breaking down.
The AI trade’s second derivative is decelerating. Anthropic 3Q26 ARR report fell short of expectations, and there is a substantial deceleration in growth rate into an already bleak AI trade tape, while indices remain less than 2% off their all time highs.
The Flagship model returned 1.8% today as the SMH and EWY shorts that we put on Friday have continued to print, along with PFE LEAP calls as Pfizer hit a new YTD high today. Bonds appear to be inflecting, and bond futures are rallying hard in the overnight session. Regime change looks to be arriving.
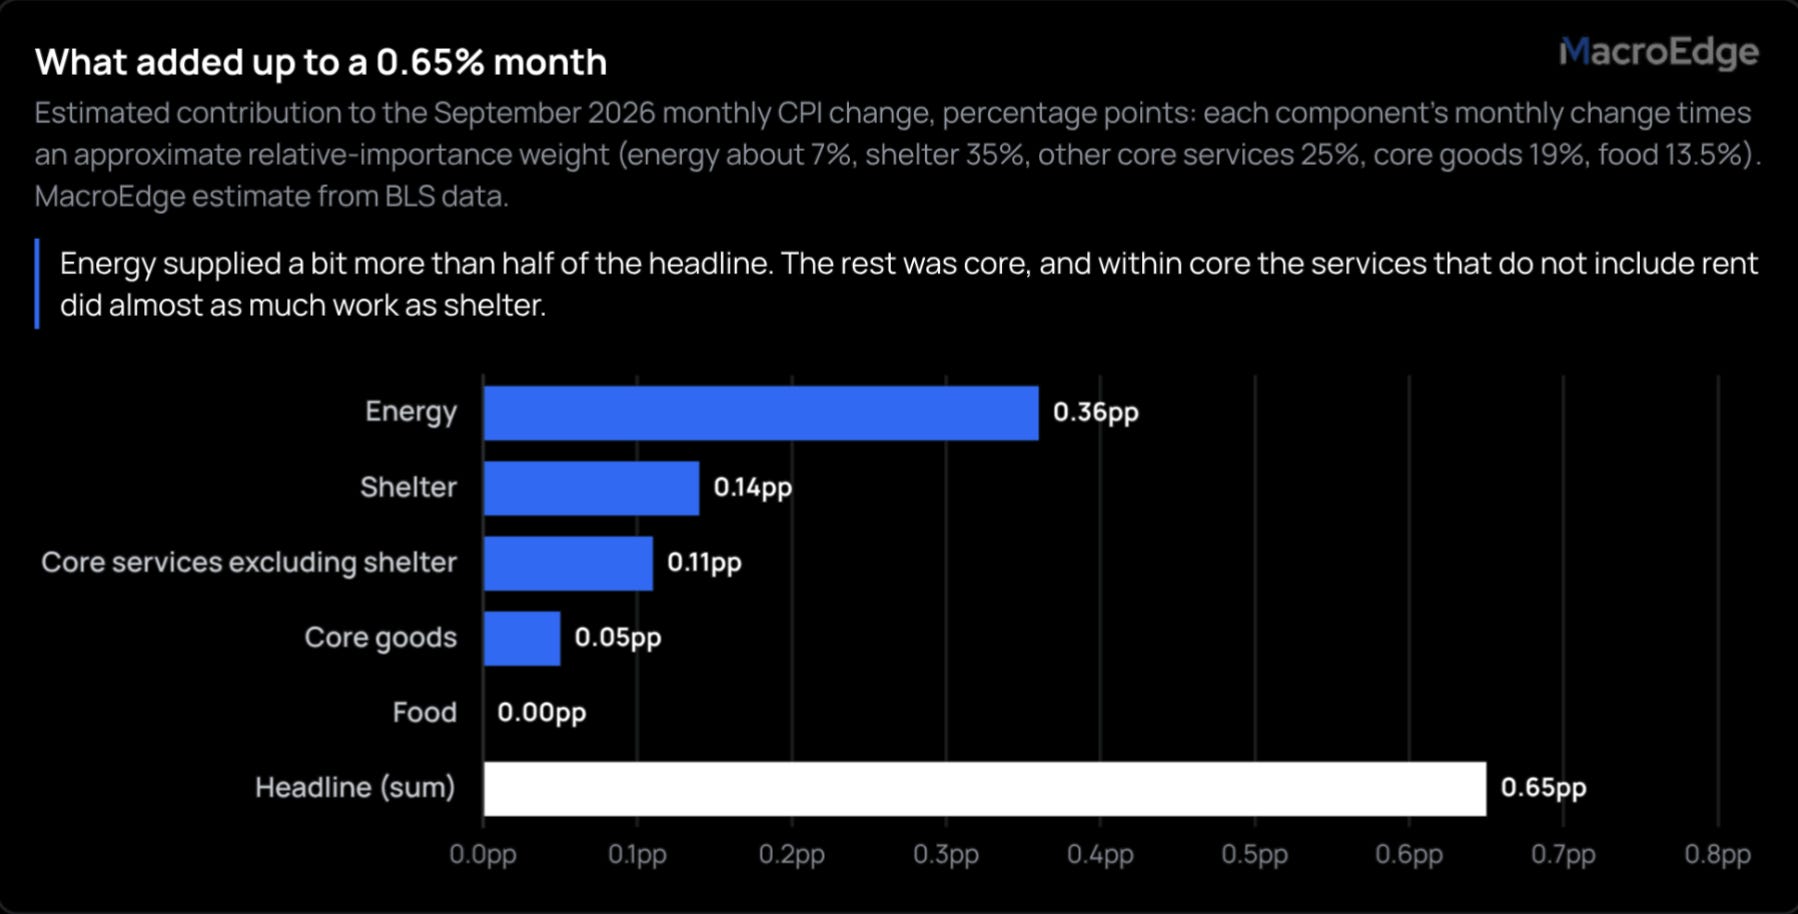
Energy prices are leaking into services, with car and truck rentals up 5.4%, hotels 2%, airfares 1.2%, and transportation services 0.6%. Airlines and rental fleets are passing through fuel costs. The beige book today noted that higher energy prices are affecting every district, and diesel costs are moving through supply chains. Several districts expect further cost increases as contracts expire and hedges fall off.
Fed messaging has shifted today staunchly back toward inflation being the main risk. SOFR futures sold off hard initially on the print before regaining ground. 3 hikes are already in the forward curve.
(Continued below: Portfolio Strategy Note, updates, and why the GOP is toast in November) →
The most important datapoint today was that bonds round tripped their decline and stocks did not. The US10Y rose over 10bps before falling on the day. Stocks continued to slide all day. Long semis and short bonds are the first and second most crowded trades in the BofA Fund Manager Survey, and both appear to be unwinding simultaneously.
Not yet a MacroEdge Ozone subscriber? Upgrade below:
