

Good Wednesday evening, MacroEdge Readers & Community,
This evening, Six will bring us the latest on the Portfolio Strategy front. We have an exciting update coming this weekend on the launch of our second portfolio strategy, the MacroEdge Oil and Gas Growth & Income book, available through our partner Plutus. I’ll be shifting gears this evening, and you can find me over at Oil and Gas Research for the Midweek Strategy Note. Things there have gotten much calmer over the last few days: we’ve seen some minor TACOs, but nothing worth pulling the parachute for. This recent dip has been enabled by a combination of bogus headlines and a resumption of the Trump Administration’s SPR drain, which will likely get them through early next year on the price front before things really start to get problematic for the SPR.
Next Tuesday, the new contributor team will get together for our first gathering on a report cadence, and I’m very much looking forward to the work coming out over the next two months. There’s a lot of great stuff on the way.
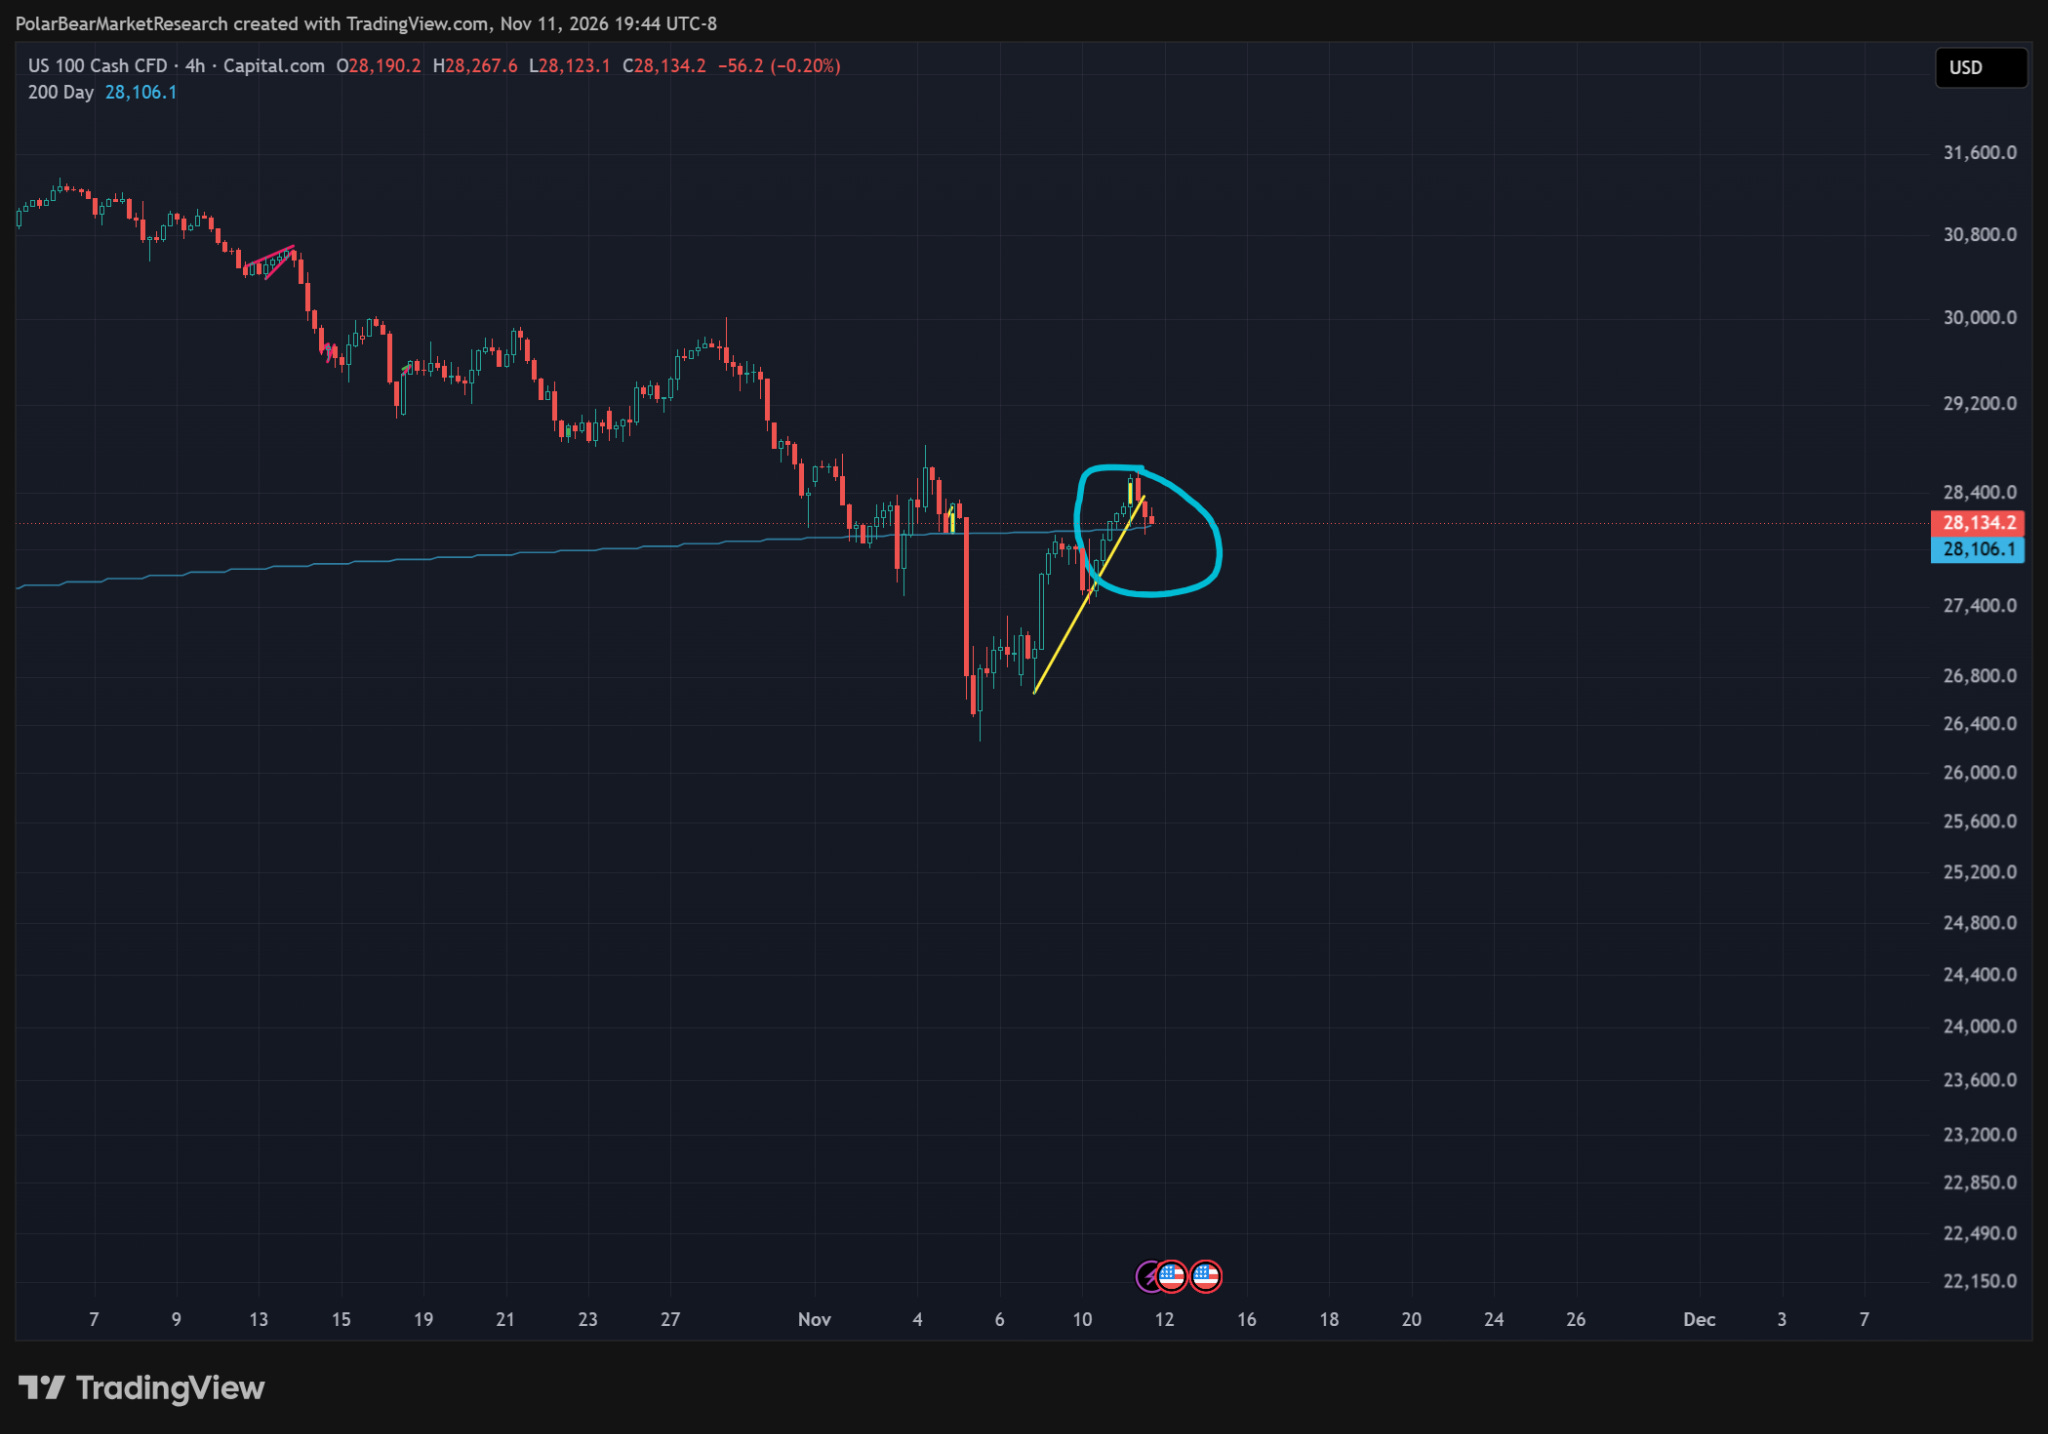
My contribution will be short this evening so Six can properly take the floor, but the headline that dropped after hours was another major left hook to Jenron’s Paradox… The timing of many of our recent reports on the matter has proven fantastic, and we’re now at a very critical point in the cycle, hovering around the 200-day on the Nasdaq. The action around the 200-day will be key to forecasting the next steps in the short to mid-term:
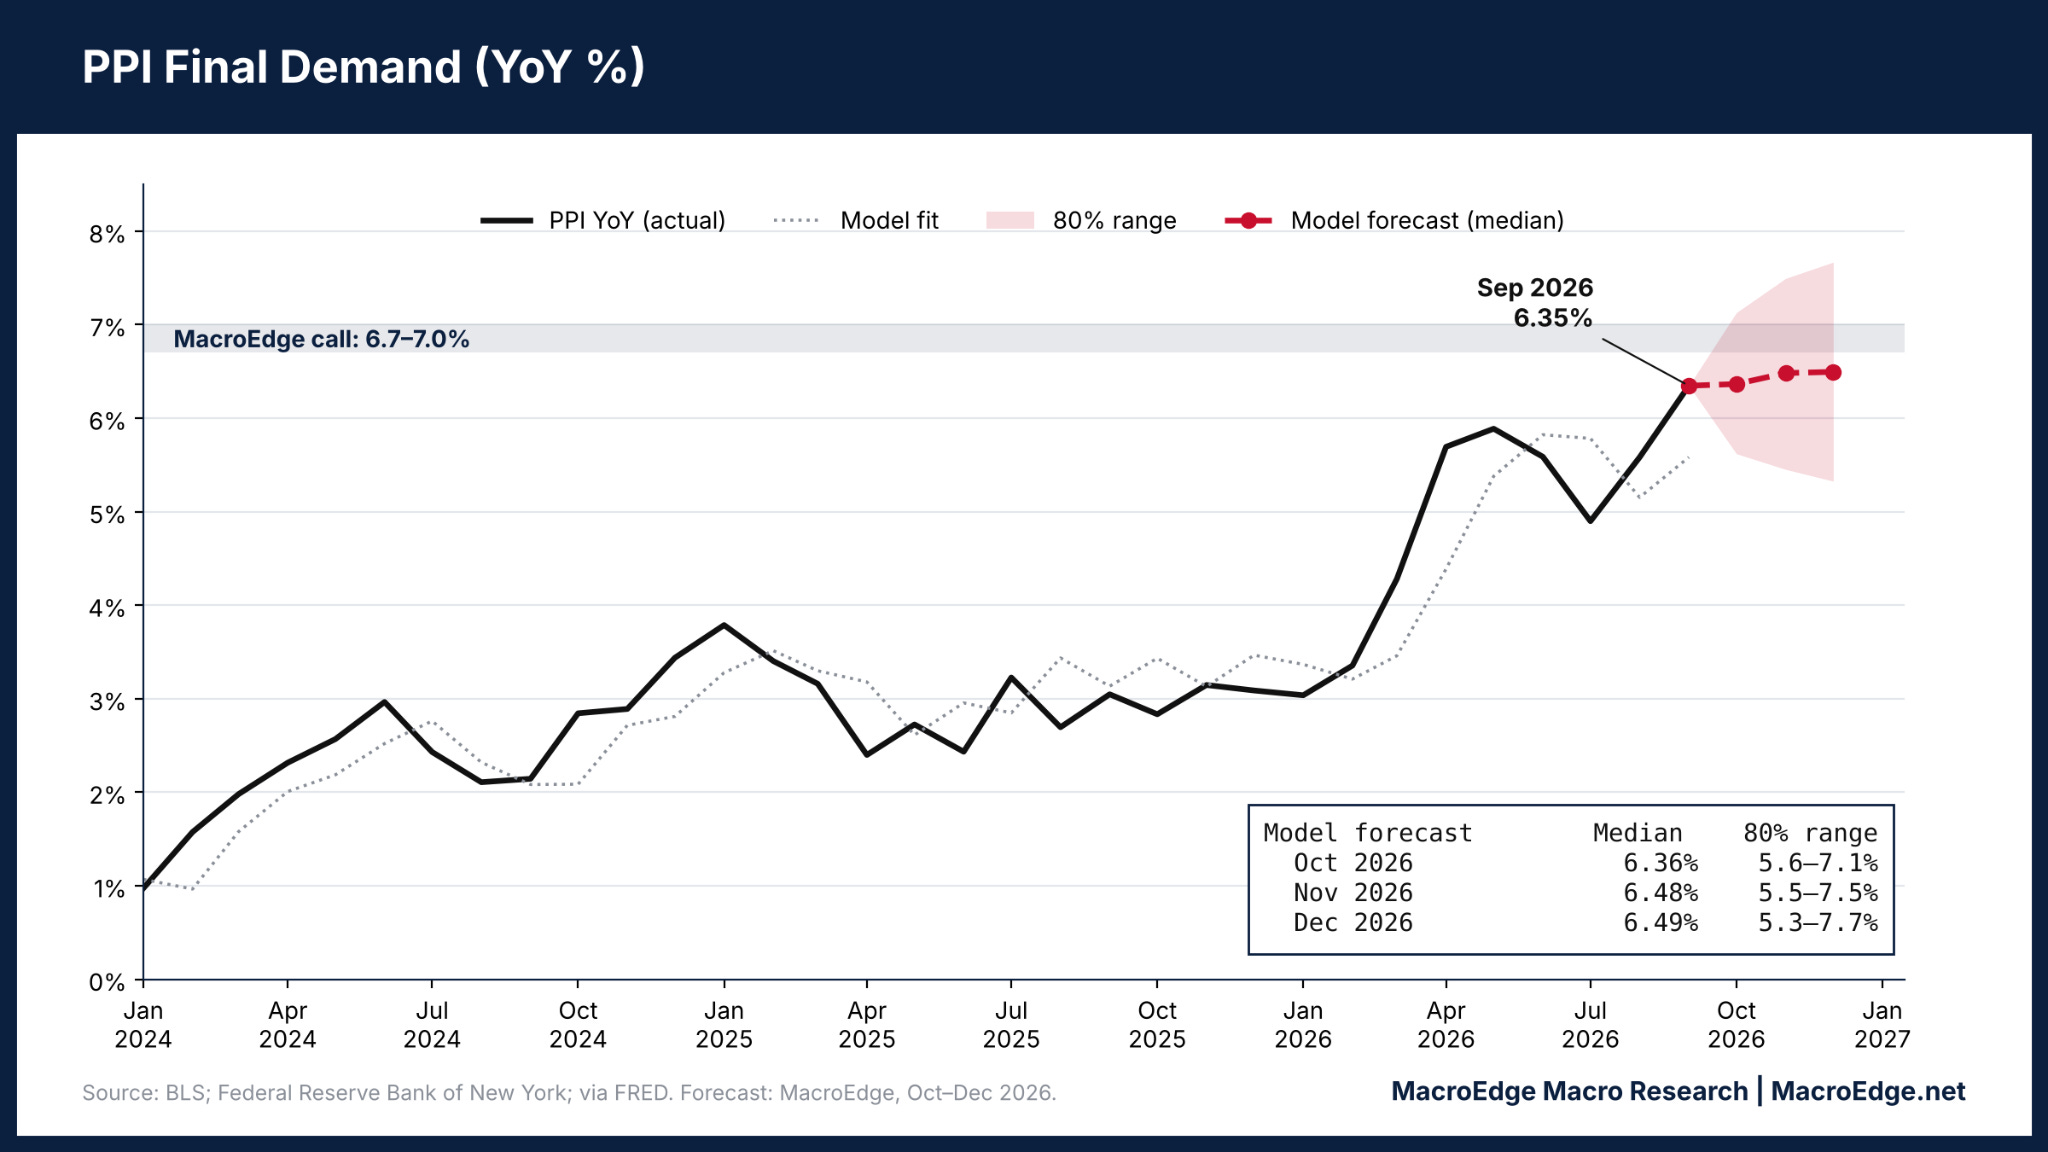
As we head into Friday, we’ll get the PPI report, and I suspect it could shift pricing further toward the right-tail scenario of a possible 50 basis point hike in December. I’m not fully convinced the ‘deflationistas’ are right about a single month’s drop in gas prices, since we’ll still be working off very low YoY energy base prices from last year through February 2027. Energy prices have pulled back a bit, but those input cost increases aren’t going away, and there’s a real chance of a 7-handle on PPI Friday. The Fed is now well behind again on tightening, regardless of personal opinions on the ‘i-shaped’ economy, and it would be wise to raise rates and take the fight to inflation more aggressively.
I’ll let Six take it away. As I highlighted yesterday, the next few days will be a crazy period of flux as we get our office set up in Arizona, before I head to our other locations next month as part of our global roadmap. Thank you all for your patience over the next few days. I’m thrilled about what we have ahead for you, from our new home base and our satellite locations, in the months and quarters to come.
Not yet a MacroEdge Ozone subscriber? Get all of our research, data, portfolio strategy, commentary, and much more, below:
Strategy Note - @SixFinance
The worst day for stocks since Liberation day 2025 has been erased in four sessions on declining volume. During that time, over a full 25 basis point rate hike was repriced back INTO the market. Jensen Huang has wielded NVDAs influence and balance sheet to become a de-facto “Central bank of AI”, and a second affair exposed by the media outlets has pushed Nvidia to prepare to remove him. His successor is likely not to have a firm grip on the balance of the AI ecosystem.
- The rebound is its own issue. Buying the dip in four days removed the primary factor that could have let the Fed skip a December hike, or at least guarantee it wouldn’t be a jumbo 50bps increase: tight financial conditions. Payrolls of +165k and a third straight core CPI of 0.3% did the rest of the work, and the September 2027 SOFR future lost 42bps.
- Neoclouds are the levered marginal producers of compute and many will not survive a glut, but rental prices are still rising and the stocks are deeply troughed. Despite that trough, NVDA, led by Jensen, has stepped in to support the ecosystem every time it has wobbled. That backstop may disappear with Jensen Huang’s exodus.
- The Chinese National Team is buying Chinese ETFs in large size, and the PBOC has put stock market stability in its focus, publicly.


