

Good Friday evening MacroEdge Readers & Community,
My time in the Phoenix metro is coming to an end in just a few days now. If you noticed our announcement on X, and through Substack, we are transitioning to a hub & spoke model in the new year to better service our client network and entities in and outside of the macro-sphere. As we continue to grow, even through this minor adjustment period, there are many positives to the coming changes. More on this is available below, and a full announcement will be available mid-month, on the necessity for this transition, adjustments to our services and deliveries, expansion of our oil and gas operations in and outside of advisory, our portfolio strategies, & more.
I sometimes feel compelled late on a Friday evening to publish a note, and this evening is one of those. This Redeye Macro Note will be structured in more of a rant fashion, which means less structure than our traditional publications, but such is the hour of the night. We’re quickly approaching a world in which the only thing being celebrated (or maybe that’s left to celebrate by those in charge) is equities going up and to the right on a nominal basis. The doublespeak in the last week has just reached levels of crazy that I did not think we would be seeing until the 2030s - up is down, left is right, the sky is green, the Strait of Hormuz flows are at pre-war levels, and we should turn our collective ignorance levels to 1000 as we turn “the game!” on TV up a little bit louder… While that seems to be consensus living in these times, and more & more are simply checking out - I challenge our audience this evening to seek out a mission to see through the fog and find purpose.
For the remainder of the article, please pardon any typos, I have drafted some of it from Substack on the mobile browser.
The ‘slop-society’ as I now label it - is pervasive, and it’s only getting worse… Next time you’re in an airport, or at the train station, or maybe even just the grocery store - walk around and take mental notes of what you see? Particularly when it comes to observing - I notice a general sense that the light has simply left the eyes of most Americans. Maybe that’s a little critical or jaded, but I tend to occupy that label with ease these days, as does anything falling outside of the realm of ‘collective ignorance’. I also think there’s a tremendous opportunity for those of us that don’t see in monochrome. All of this to say, much of what we’re seeing isn’t something special in the context of societies and economies - we’ve simply chosen, collectively, to sedate ourselves with short-term enjoyment and benefit, rather than ever take the medicine necessary to correct the very troubling course we’re on. Yet more signs emerge by observing the levels of self-enrichment from the very top, corruption wide out in the open, and almost Orwellian doublespeak (mentioned above) that has become the norm since the pandemic days.
While I have hope that the bond market and the so-called ‘bond vigilantes’ are finally starting to see through some of the noise, especially as it pertains to BLS employment reports, I also know the measures taken in response to the bond market movements at some point will pour gasoline on the underlying ‘Project South Africa’ machine that gains a little more momentum with each passing year. This book concept has not yet made it off the ground - and won’t for some time given our expanding commitments and what will be a fantastic end of the year and 2027 - but the underlying concept is simply something that we can continue to observe and understand. Sure, it can be uncomfortable to discuss, but history shows us time & time again that history is not bliss.
In February of this year, when I spoke with Business Insider, I warned that the US was missing a so-called ‘growth engine’ - that growth engine has become nominal inflation with data centers stacked on top. The latest shiny object understood by few, celebrated (and even worshipped) by many, remains something that I am deeply skeptical about - especially with who is behind the ‘growth engine’. What looks on the surface like an economic miracle in a post-2007 era of relative stagnation, is much more likely to be a mirage as we turn the corner into 2027. Though we no longer publicly publish our data center construction data - especially after drawing a special kind of heat from that crowd earlier in the year - America’s latest rehashed bubble, still called a miracle, has a date with destiny sooner than most think.
Also… this is a headline you might excerpt to read in a paper in Argentina, Venezuela, or Zimbabwe -
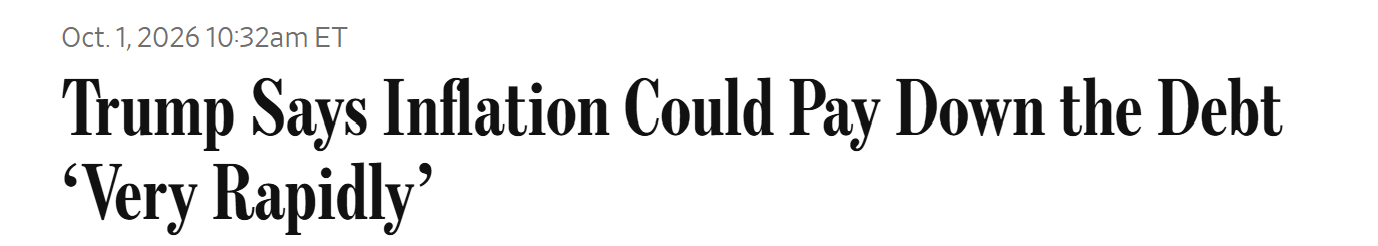
Here in the United States? Well it’s simply consensus policy now… we don’t want to talk about it, but it’s exactly what both sides are planning on doing until the bond market tells them otherwise.
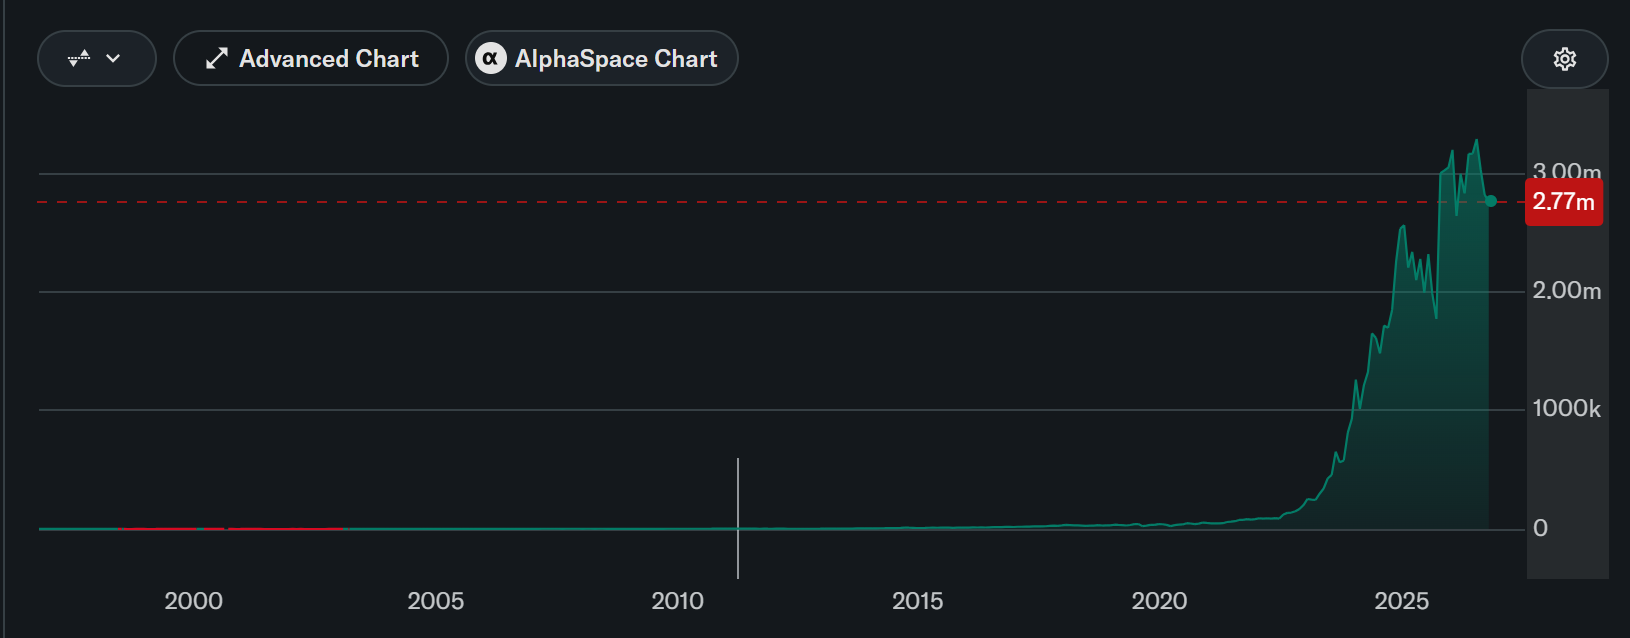
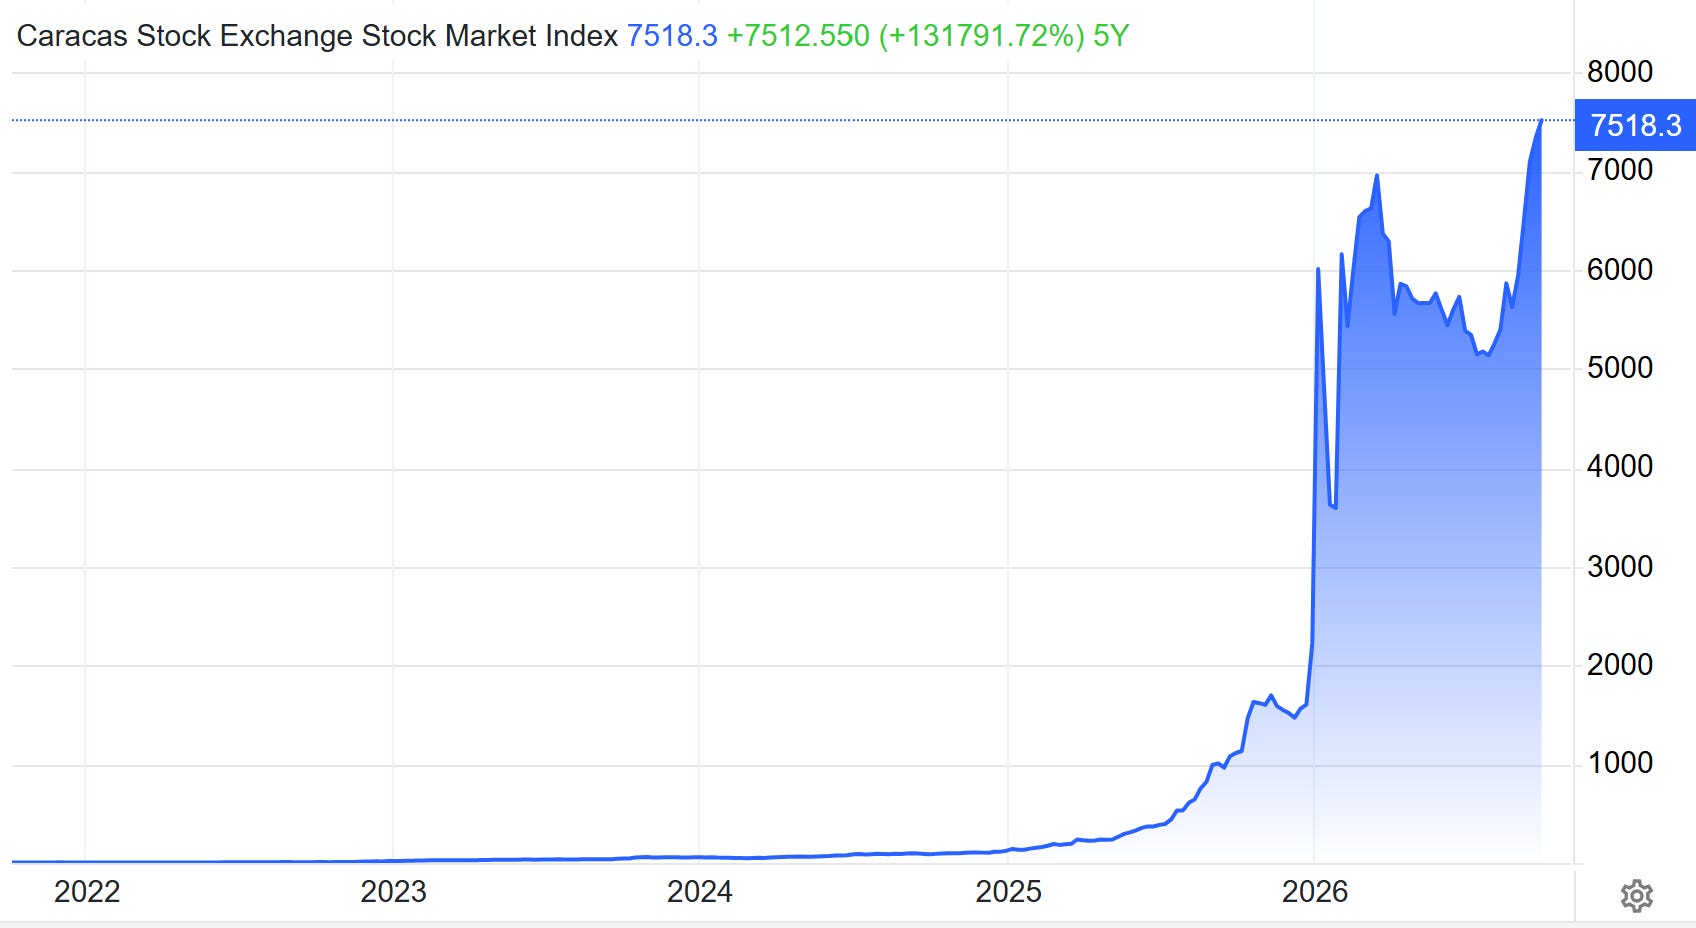
A reminder… Equities going up and to the right, without examining the underlying cause(s) is not inherently a positive thing, in and of itself →
Argentina is one lesson, in motion:
The IBVC is another:
& we can go on and on, with lessons from history…
Let’s not over extrapolate a flight to safety, and 10,000 other causes driving our policy failures, as success in a vacuum:
Ie. Zimbabwe
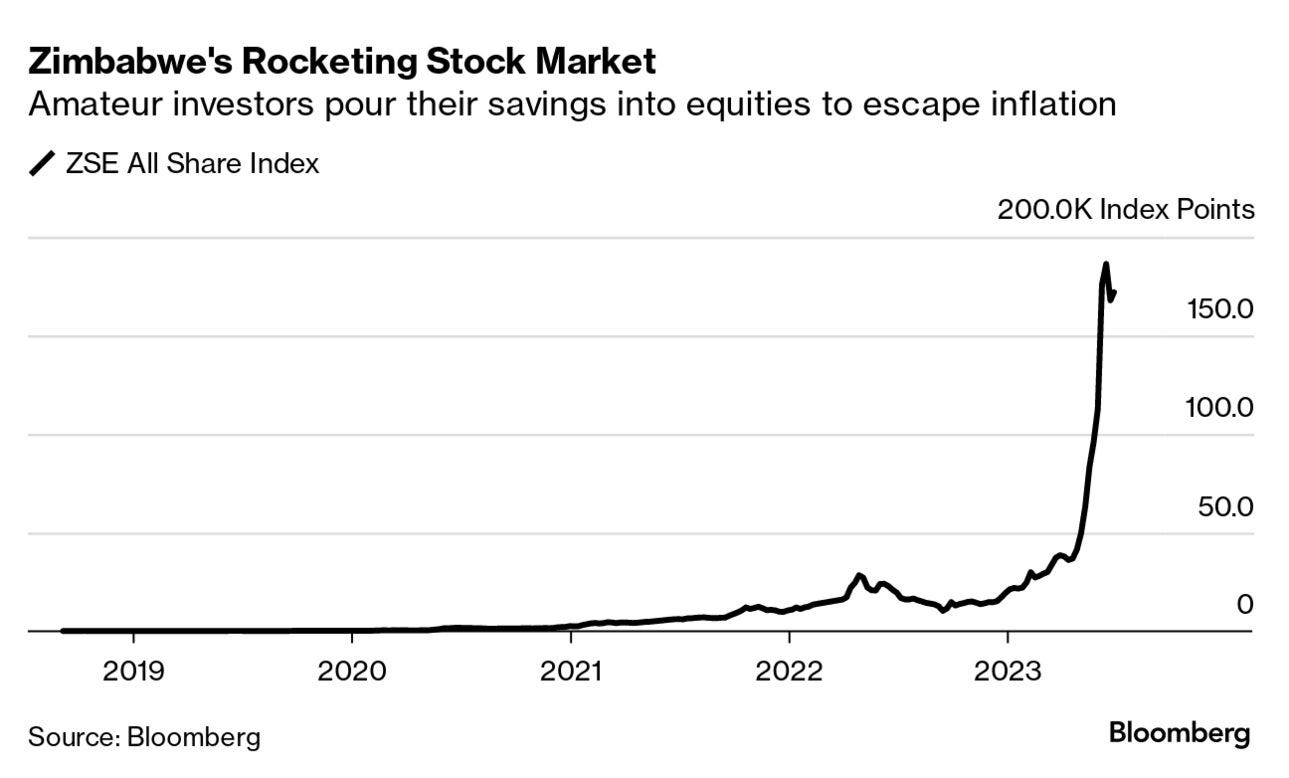
The end result of regime after regime and inflation at this point in our stage of debt-burden is that each one will get more & more obsessed with the short-term stimulus boosts, the ‘data center’ style growth engines, pulling forward a quality of life boost for an aging population, and nominal everything.
Turning our attention to what I will cover briefly this evening - so I don’t continue to write past the 3am hour - I want to briefly touch on the SPR release announcement today, discuss our future as an organization, and look at Europe - which is soon to find itself in major trouble without immediate course correction.
In one of the most well-telegraphed groups of policymakers of our time - is this a warning we should heed seriously?
This is certainly an outcome that cannot be ruled for large EU nations as we progress through October. A wildcard, however, is that Europe could back-out of the agreed to SPR release today - and that is not something that would surprise me after the President went out and said he was never planning on an export ban. While political upheaval is becoming a real thing, particularly in France, a lot of these tremors have some 2008-style elements - particularly on the energy price front… This month is likely the last where we see these announcements have any sort of meaningful impact on energy prices, especially if conflict escalates across the Middle East as I expect it to. Saudi, particularly, in choosing to invade Yemen with what will end up being a mostly conscripted force - will go down as one of the largest military blunders in modern war history if it occurs. US military leaders know what that would look like and chose to take the ‘back-out’ route, rather quickly today, for very obvious reasons. A Saudi-Yemen war has the exact setup for something that could last years & years, or until the Saudi economy buckles and they stop the fighting, but I do believe that escalation is once again just around the corner. In the last few days, there’s been a very quiet (ironic) yet loud shift in talks about peace, the war, deals, etc - and it’s because the globe is realizing that the clock is ticking and things aren’t really changing. Subsidizing global oil and refined product demand with strategic petroleum reserves, emergency buffers, and shrinking inventories - as refineries are bombed daily, Iran retains partial control over the Strait, and Houthi forces can target Saudi energy infrastructure at will - is totally unsustainable - and markets under the hood know this already.
The Brent reaction today should tell you much of what you already need to know…
Quickly on the labor front today - the report should be taken with a massive grain of salt, but…
No - it’s not just retirements driving concerning figures like this….
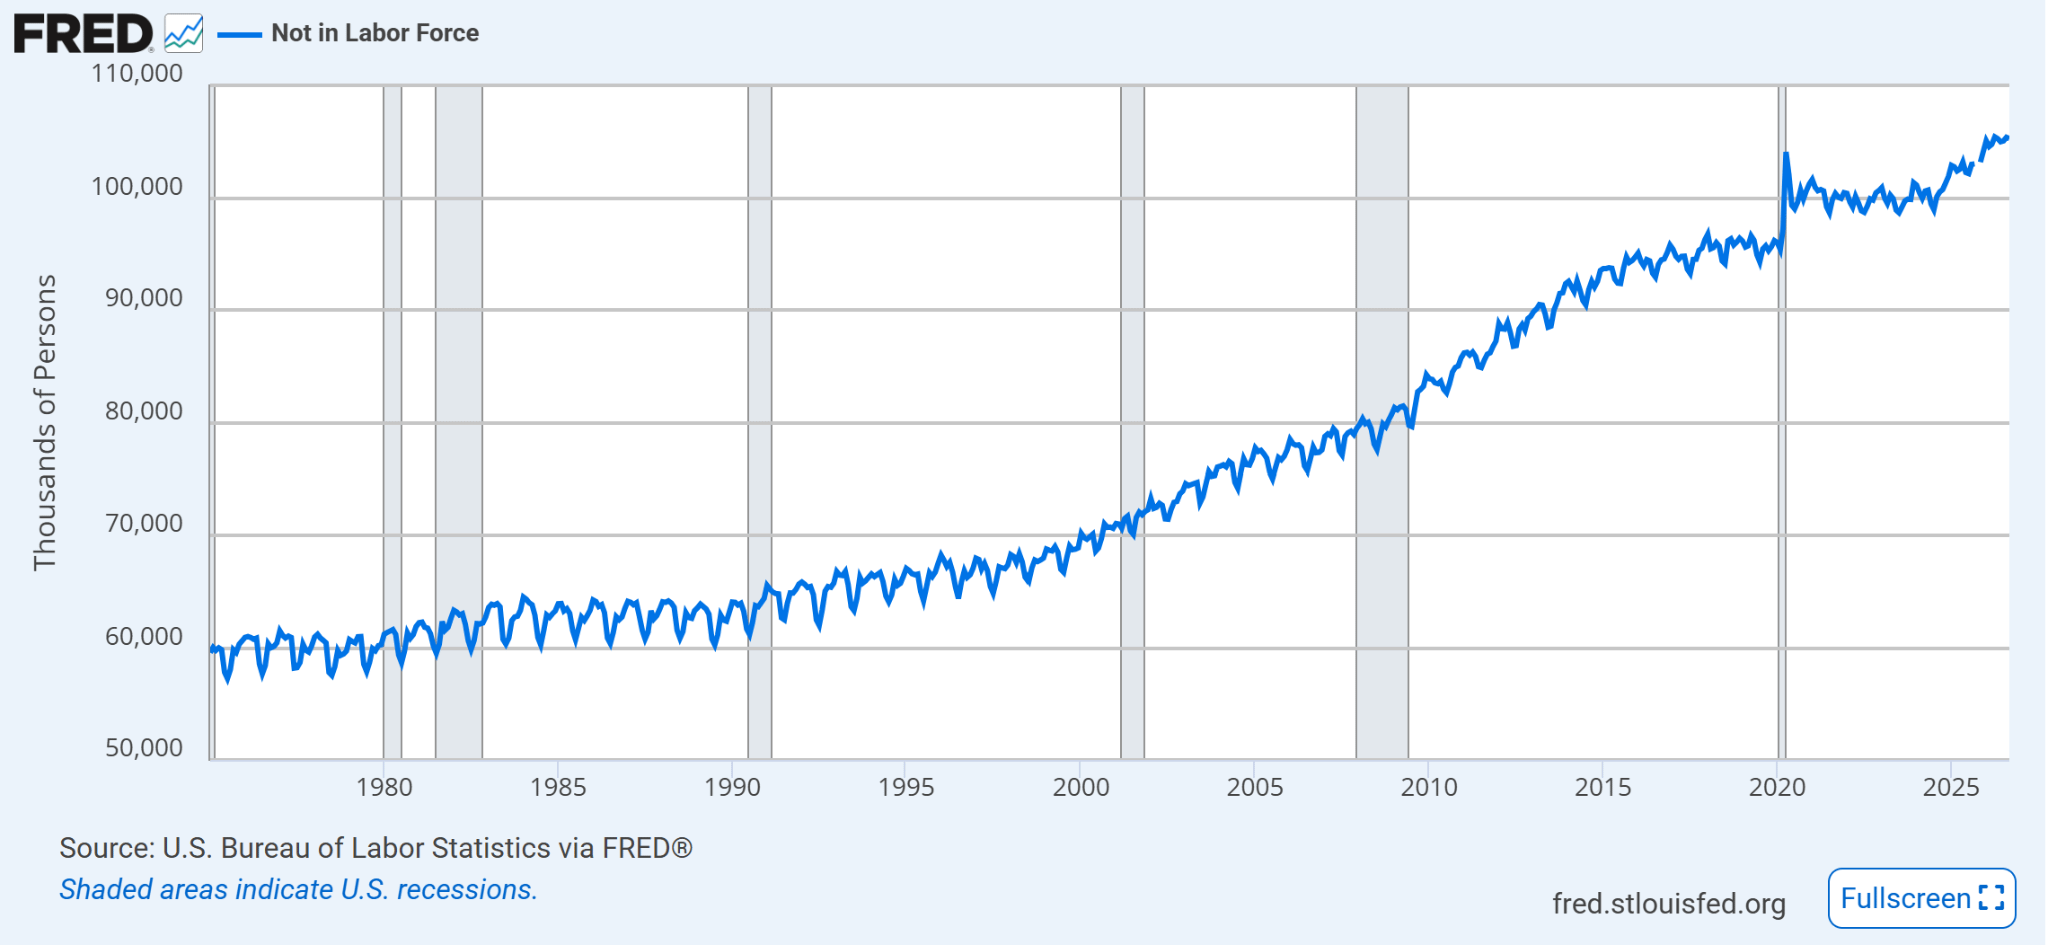
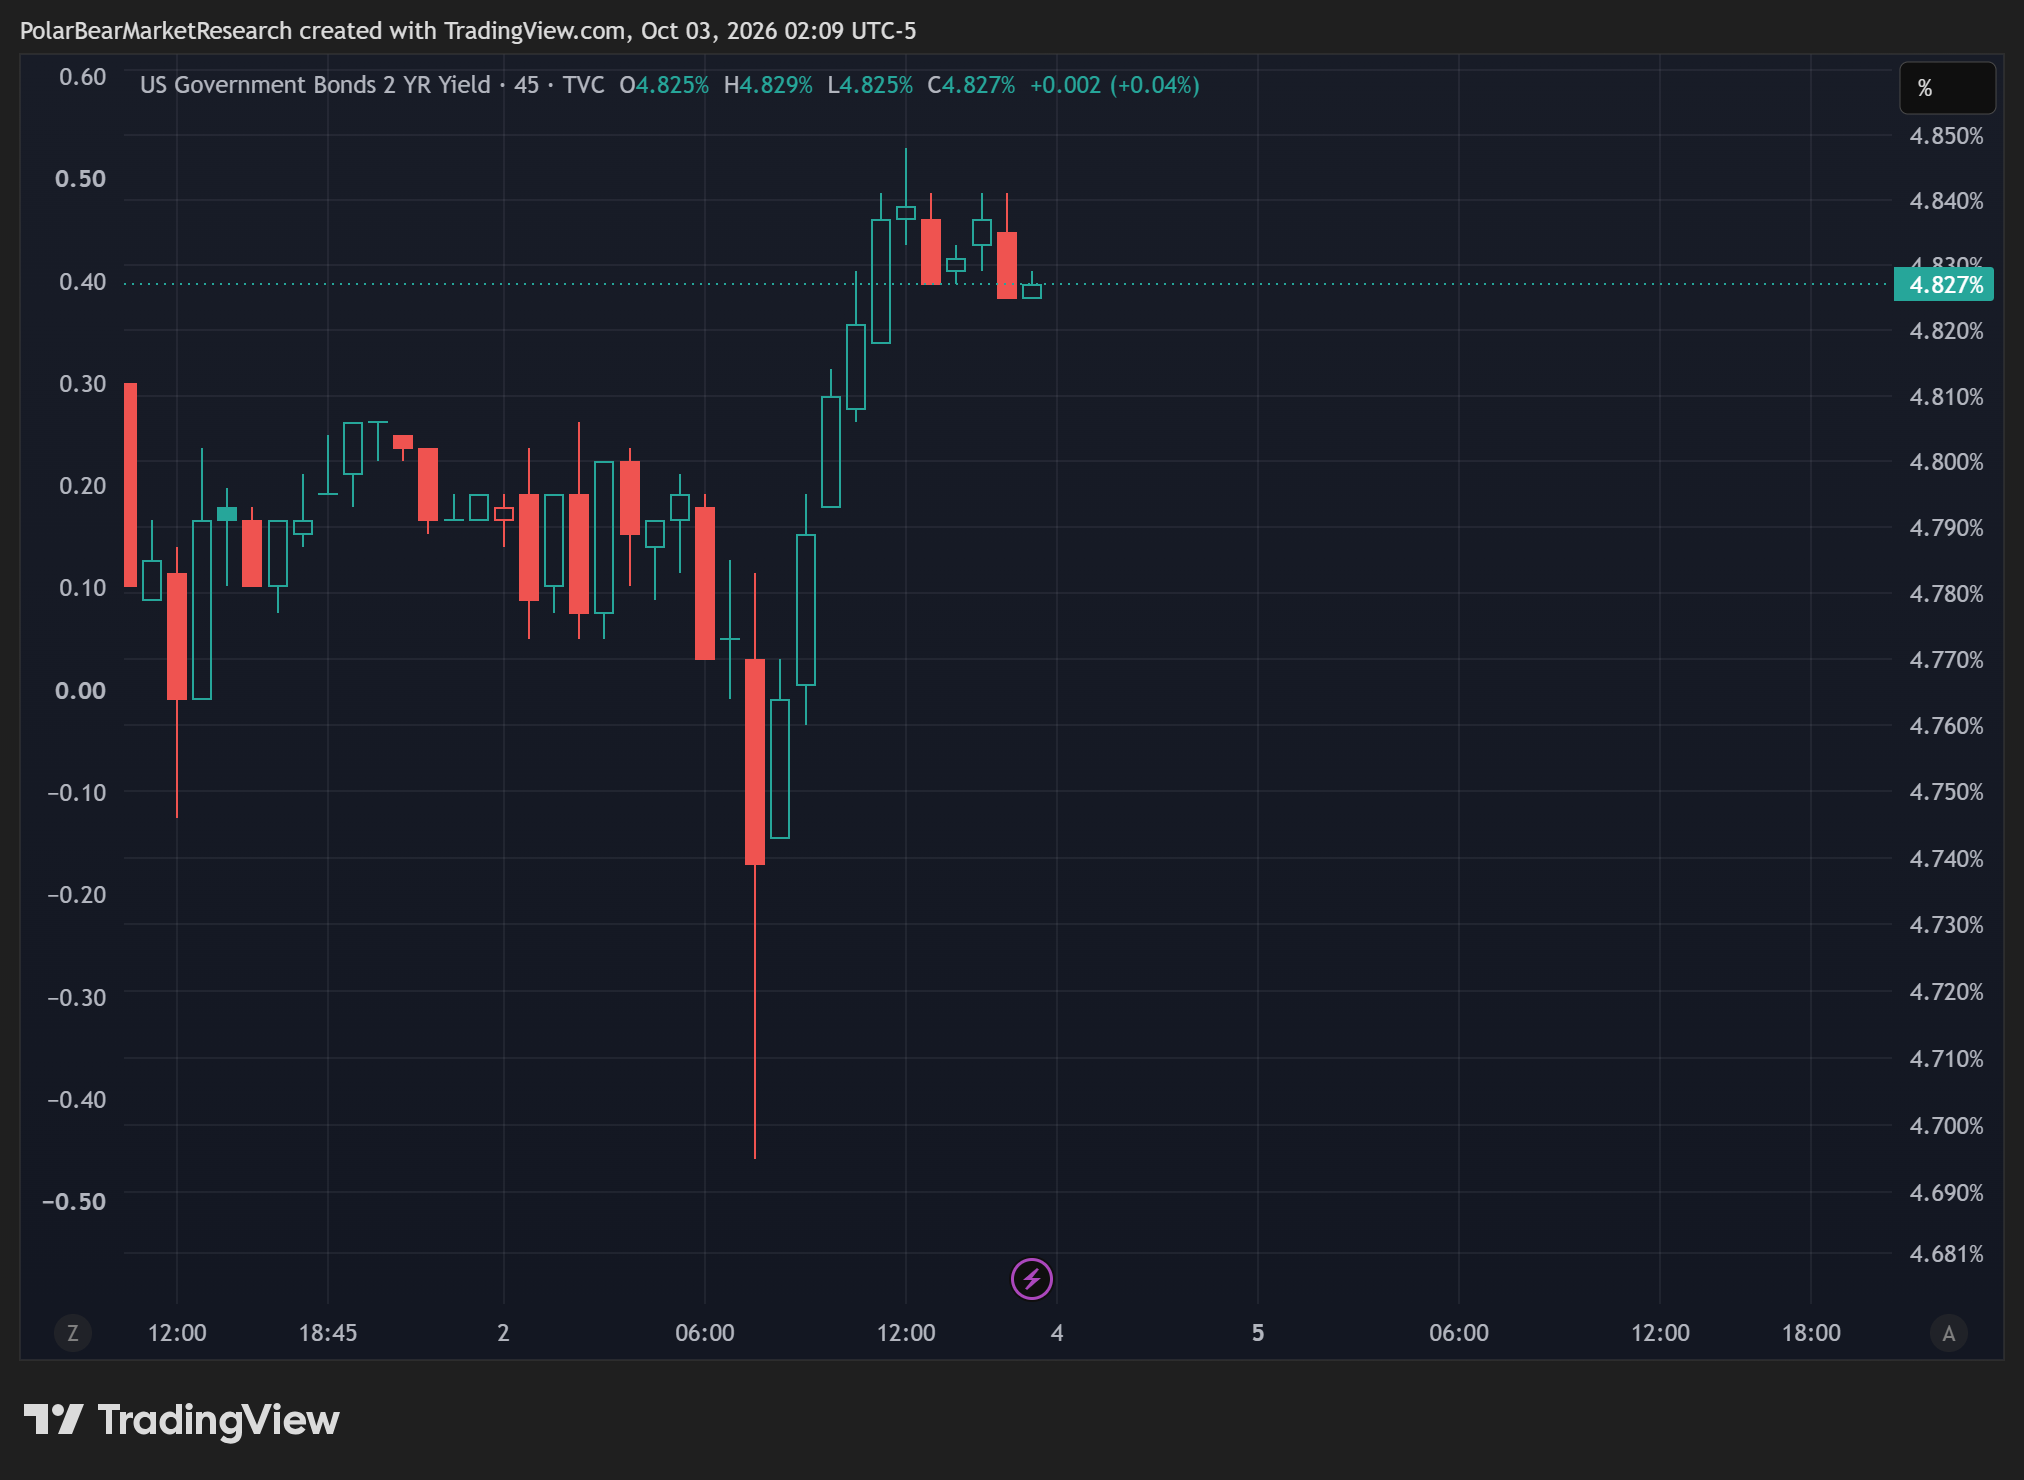
Demographically speaking, labor numbers will continue to provide more & more signal than noise in the coming years as our labor force age and composition continues to shift. We need to stop overplaying things like claims, antiquated methodologies, and U3 - especially when we have the full capacity to track more accurate data - but we absolutely do not want to as a society as the results would be akin to taking lipstick off of a pig… Of course, for this very brief period of bond market sanity - it seems that we in this community of ours aren’t the only ones that have taken note of said data quality or legitimacy:
Our Future
From an organizational standpoint - there has been and will continue to be some major change through the end of the year. The largest shift that will be covered this evening (or now morning) and explained at much greater length mid-month in our full Welcome to Q4 & What’s Ahead report. Our highly discombobulated structure of spreading out between Florida, North Texas, and everywhere in-between caused a lot of friction, unnecessary time on the road, and lost productive time that could’ve been better serving you. The new structure introduces sound bases for our different practices and businesses, unlocks that time to better serve you, and puts us closer to where our customer hubs are thriving - particularly in Arizona and Southeast Florida. While I had time to explore the Northwest Florida option, there simply wasn’t enough going on to make it make sense - and the below is what we’re going to build from through the end of the year, but particularly at the beginning of the new year.
The new hub & spoke model - designed to serve you better:
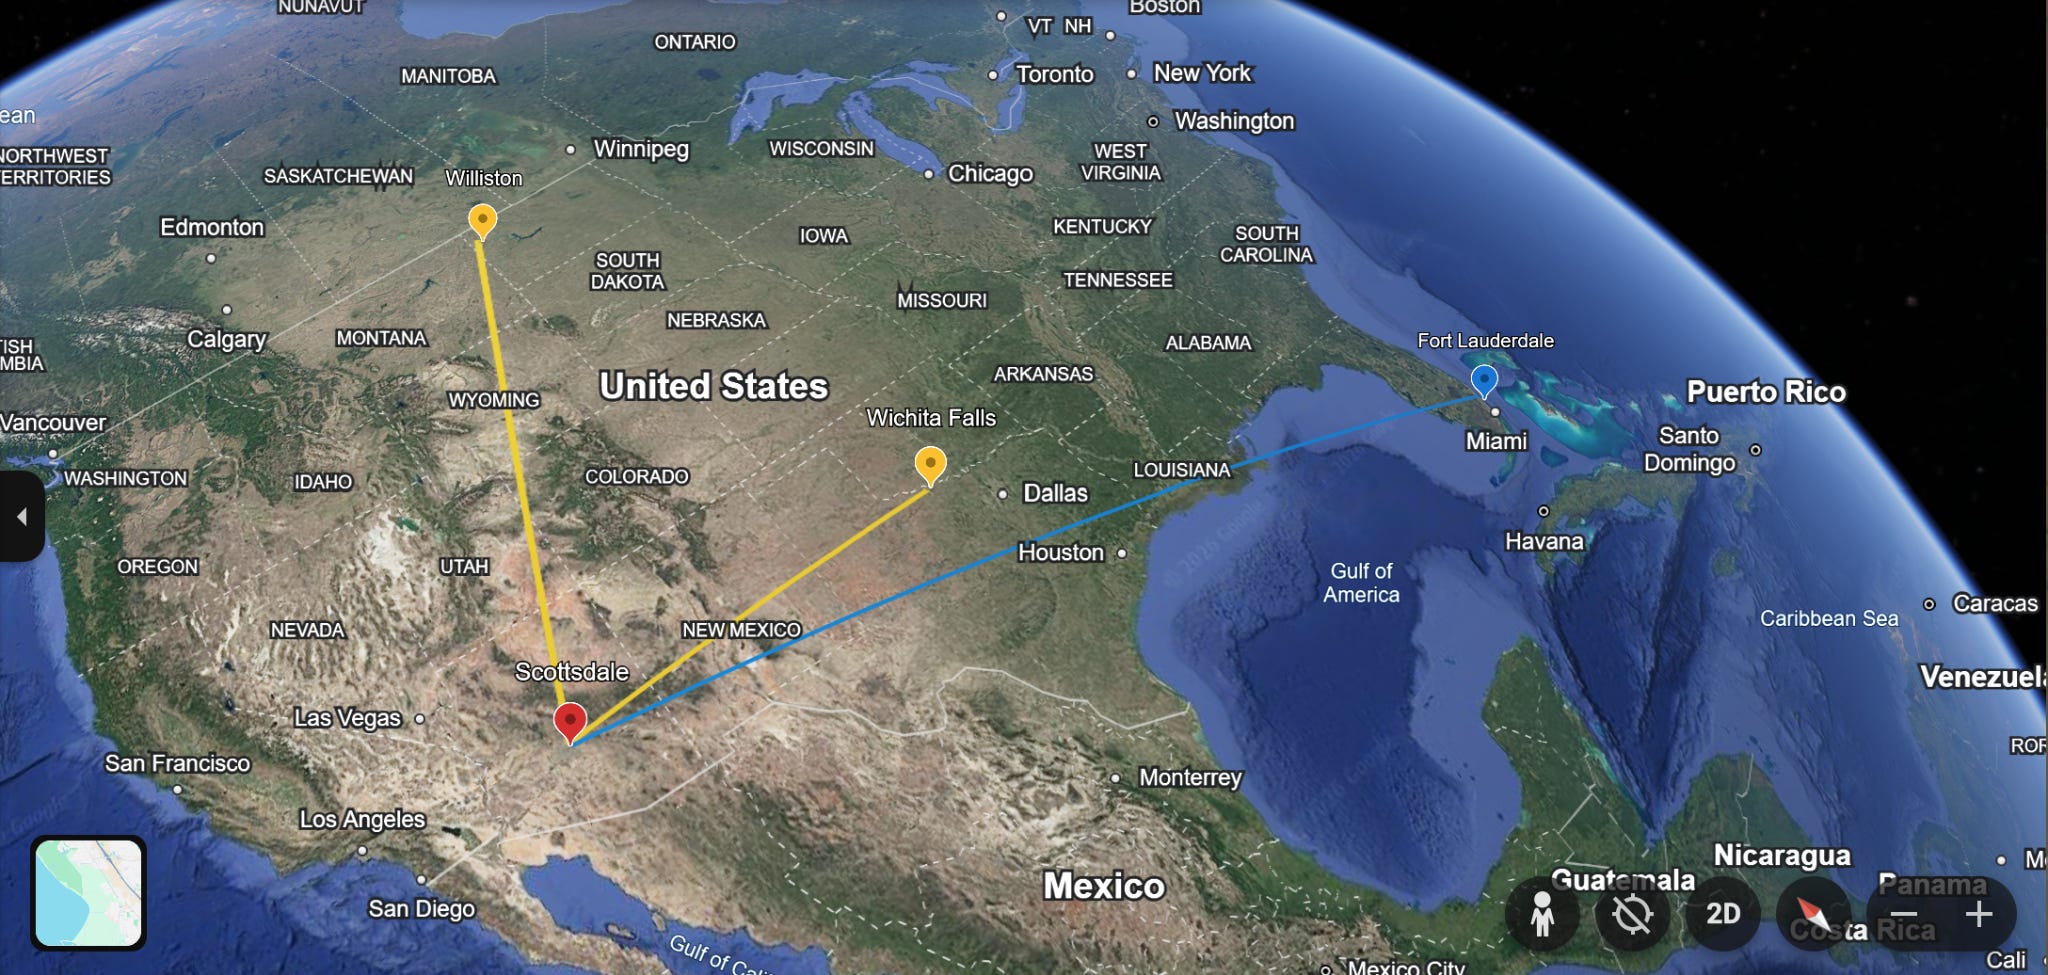
Scottsdale, Arizona [New Office Location - HQ and ‘brain’ for everything]
Wichita Falls, TX [Oil and Gas - Operating]
Williston, ND [Oil and Gas - Advisory and Economic Research]
Fort Lauderdale, FL [Macro & Advisory]
As mentioned above, more detail and color will be added to each of the above mid-month, there’s a lot I have to add on why these changes make sense, and how they will serve as the foundation for expansion from this fantastic foundation into a broader coverage across the Western Hemisphere.
We thrive through intelligent growth, and this is going to continue to enable that as we head through this quarter and beyond. I appreciate patience regarding these changes, and including with our team adjustments that are nearly concluded - and I am excited to share more mid-month.
Digesting the SPR Release - More of the Same Policy Failure, Good for O&G Sector
The IEA/G7 SPR release was something that we had been expecting for weeks - and remains part of the ‘patience through October’ narrative that I am sure has gotten exhausting for some of you to read.
