

Good evening MacroEdge Readers & Community,
It’s quite unbelievable that we’re already turning the page into the 4th quarter. With each passing note that I author and with every flight I board, there are days that feel long & slow, and others not so much, but broadly speaking - it seems like someone hit a fast forward button around that 2020 year. With all of the time each of us spend looking at markets, charts, and obsessing over the slightest headlines & adjustments - don’t forget to occasionally take a step back and take a breath, too, before taking the next steps forward. For those of us in this transition period on the team at MacroEdge, it feels a little like a compass that’s recalibrating for our next level of ‘scale’ both inside and outside of the macro-sphere that we’ve now occupied for 3+ years. With our oil and gas operations expanding in size and responsibilities, I am thrilled to see what the rest of the year has in store, especially as a search begins soon for a small operator in North Texas. One of the elements that has continued to make us extremely unique in this landscape has been our combination of real-world expertise coming from our 50+ strong contributor network, and our ability to forecast things correctly from expertise that lives outside of both Wall Street and the academic world. While this landscape continues to get more cloudy in my mind, especially from a traditional economic perspective, I also continue to think that our capacity to predict and forecast is improving with time.
This evening Six will provide the latest Portfolio Strategy update and commentary on both our portfolio strategy performance and on the broader macro picture. Internals have continued to deteriorate over the last several weeks and the bond market has been little help as it pertains to performance of the book. In catching up with Six today, important changes have been implemented for the strategy prior to the strategy going live next Tuesday. Following the launch and announcement - of which there will be more information over the weekend - the second investable portfolio strategy will be available within the next few months through our partner (to be announced in said announcement).
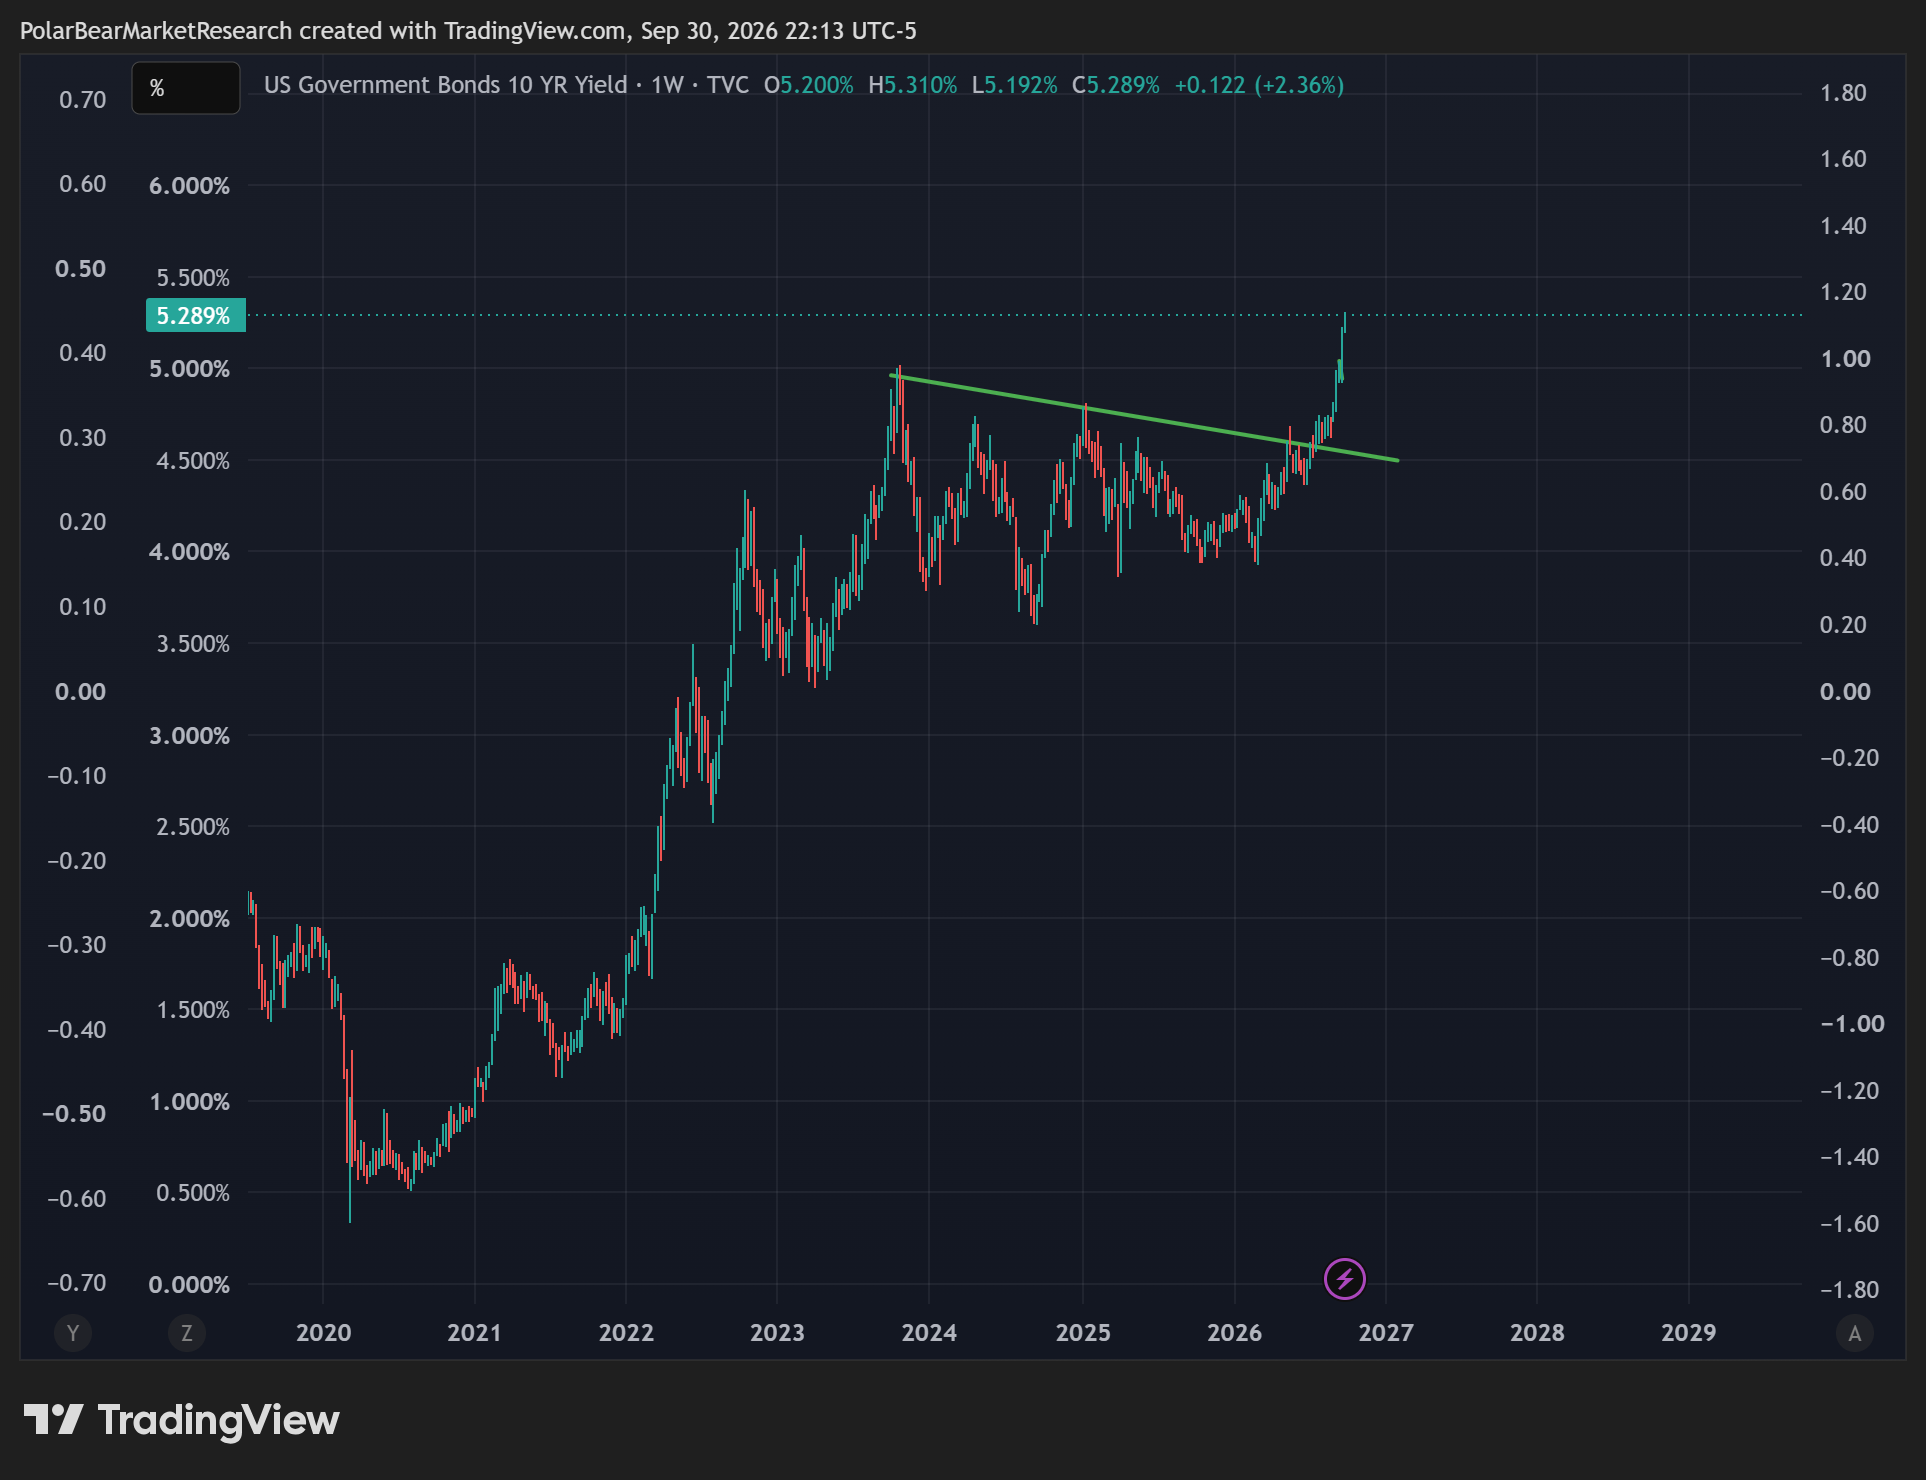
Today’s PCE release was brushed off as noise by the bond market - as it should be - and we have Friday’s job data as one of the last *relevant* data releases going into the October FOMC decision. I really think the absolute obsession over these Fed moves is a joke until fiscal gets its act together (which at this point will only happen when the bond market really breaks something). There isn’t a single politician talking about curbing spending, the runaway debt, etc - the list goes on for days - and for the time being it finally feels like the bond vigilantes have gotten comfortable with turning up the heat in the interim in this window of opportunity. While vigilantes may not be the right term months from now if the ‘trade to fade’ bonds becomes greater consensus, bond longs have continued to bleed out slowly since the start of the Iran war. The war is very inflationary, and the Fed cannot prevent that inflation. Given those two points - inflation is just going to continue to rip - both from the energy price component & non. To simply strip energy prices and point to that as any sort of useful signal in a world where petroleum products live up and down every single supply chain is rather embarrassing - and it appears that bond traders have finally taken note of many of these matters at the same time.
I won’t go on & on endlessly here since I will soon be penning the Oil & Gas Research Strategy Note for Wednesday - but the ship is once again teetering on the edge and in this centrally planned market environment (and increasingly so - the economy if you look at things like government stakes in startups) - risk has to materialize in an almost combustible fashion if it is going to take policymakers off guard… Either outcome won’t be particularly positive for the lower 80-90% in the economy - but our job is to simply acknowledge that fact and then position ourselves in the best way possible to capture upside from understanding the landscape.
These people in charge are addicted to inflation in all of the wrong ways, and the only way an addict like this will learn as less is to get a true shock to the system as a wake up call…
With that being said, I will let Six take the remainder of the note away, and I will see you in the Oil & Gas Strategy Note…
– Don
—----------------------------------------------------------------------------------------------------------------------------
—----------------------------------------------------------------------------------------------------------------------------
No Country for Long Bonds
The US10Y after flirting with 5% has now broken decidedly through and bond vol has exploded higher. The move thus far has been driven by real yields, and has not seen meaningful participation from inflation expectations. So what the heck is going on here?
The predominant factor(s) driving the move in rates really depends on who you ask and on what day, and how much rate sensitive exposure they have, but the move in global rates can primarily be attributed to procyclical fiscal policy across the globe at crisis-level deficits, amongst a confluence of other factors.
A perfect storm of other factors are all hitting together as well. Supply shocks from the Iran war.
Demand shocks from Infrastructure buildouts across the world attributable to AI and military-related deglobalization trends. Hawkish and hiking central banks. Hyperscaler competition for capital. The $40T psychological level on the US debt has been breached.
Despite all of this, bonds are starting to appear genuinely attractive for the first time in years. Allocators who for years who have allocated to private equity, private credit, hedge funds and liquid alternatives due to snoozingly-low yields on bonds now have a serious additional investment option with a return that is meaningful again. The marginal buyer finally has a place to park capital that is both convex and hedges the growth cycle that appears to be the only game in town(as it always does near the top of the cycle). Second quarter GDP was revised up to 2.2%, and Atlanta FedNow GDP is tracking at 5% for 3Q.
Today the Core PCE, the Fed’s preferred inflation metric, came in meaningfully under expectations, rates briefly rallied… and then sold off once again to new cyclical lows. What’s a sovereign debtholder to do?
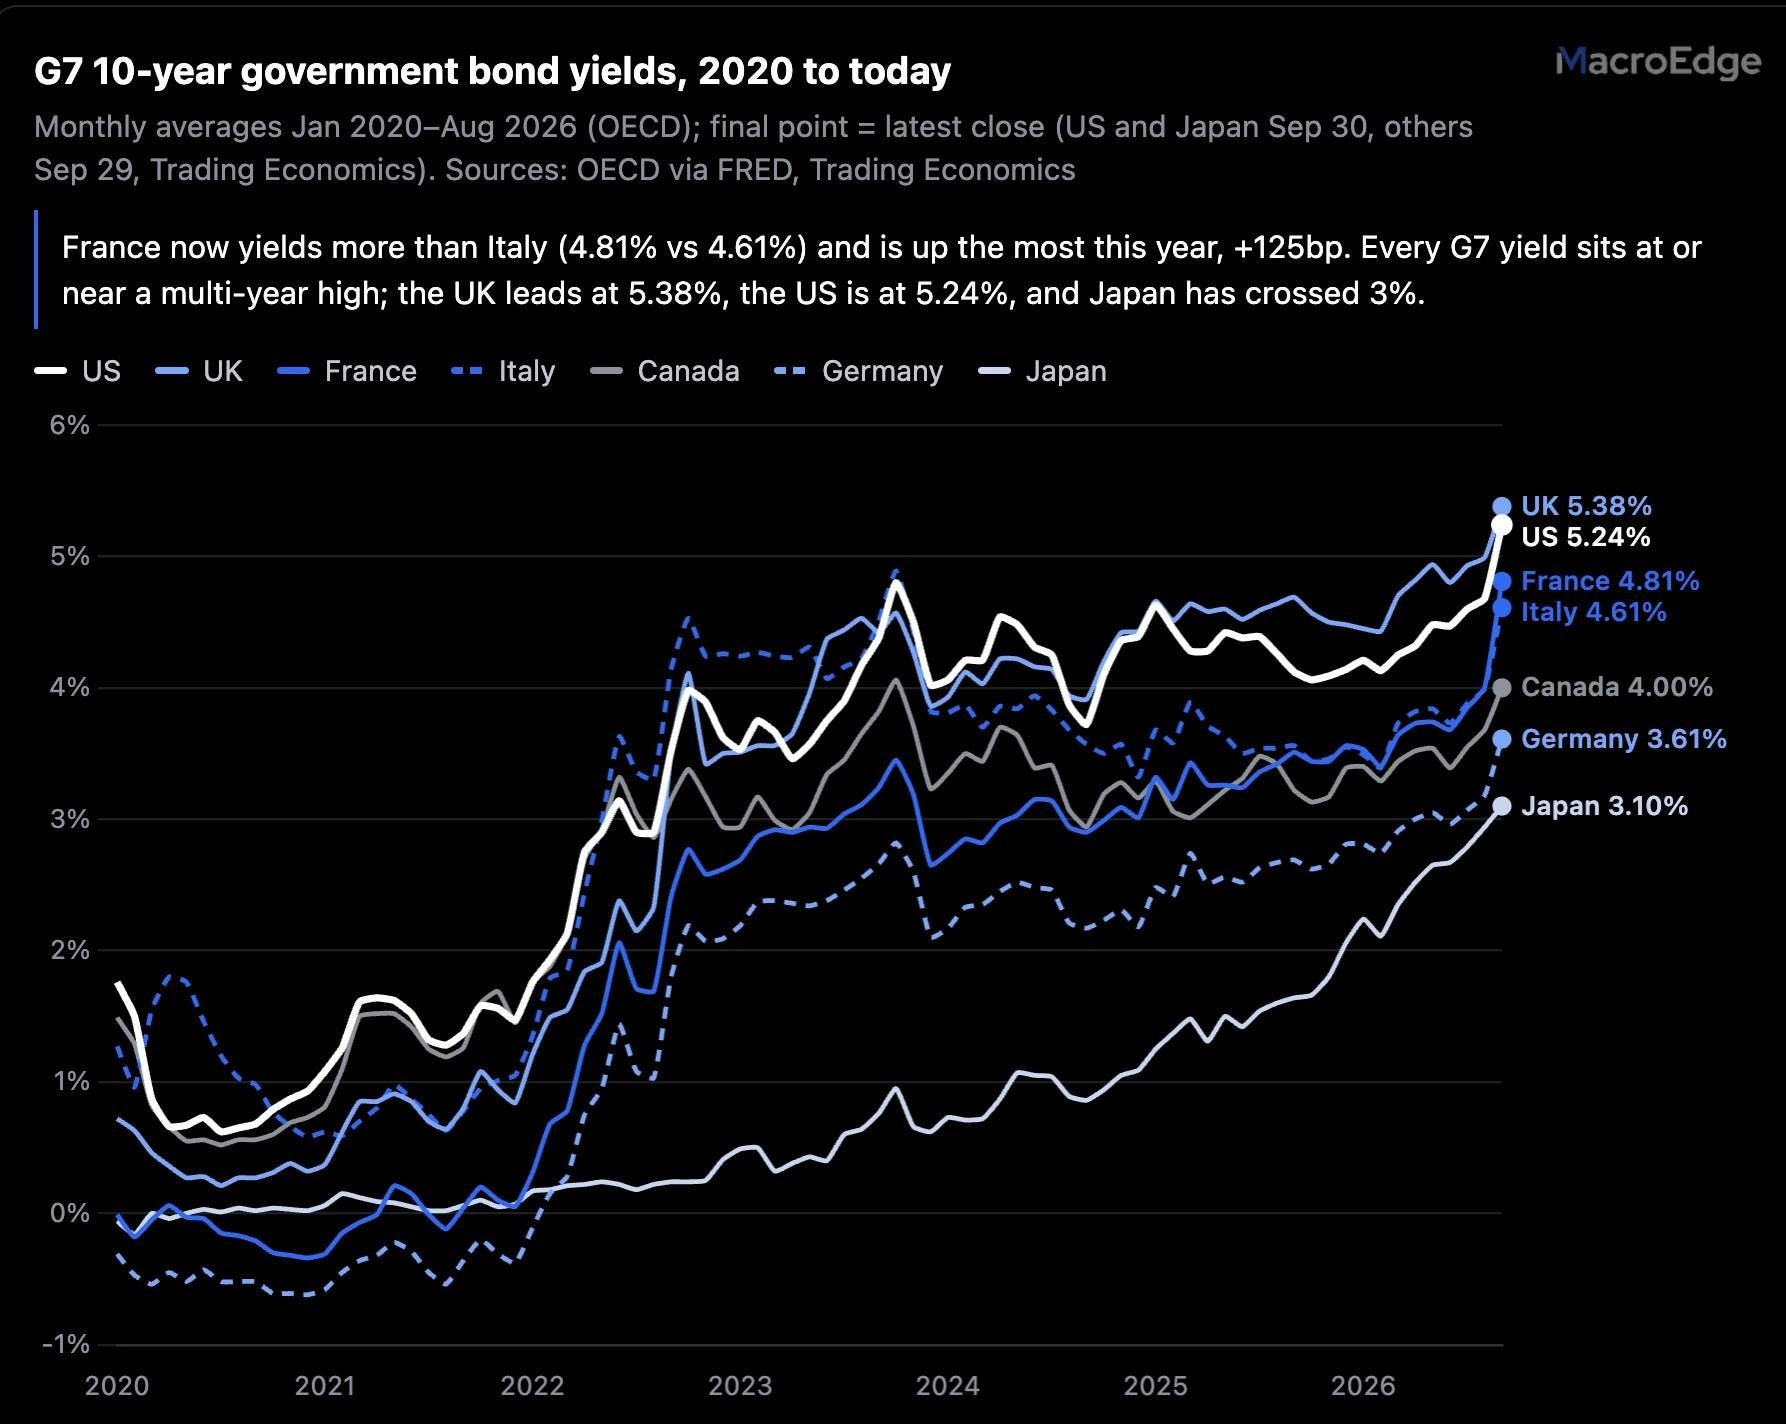
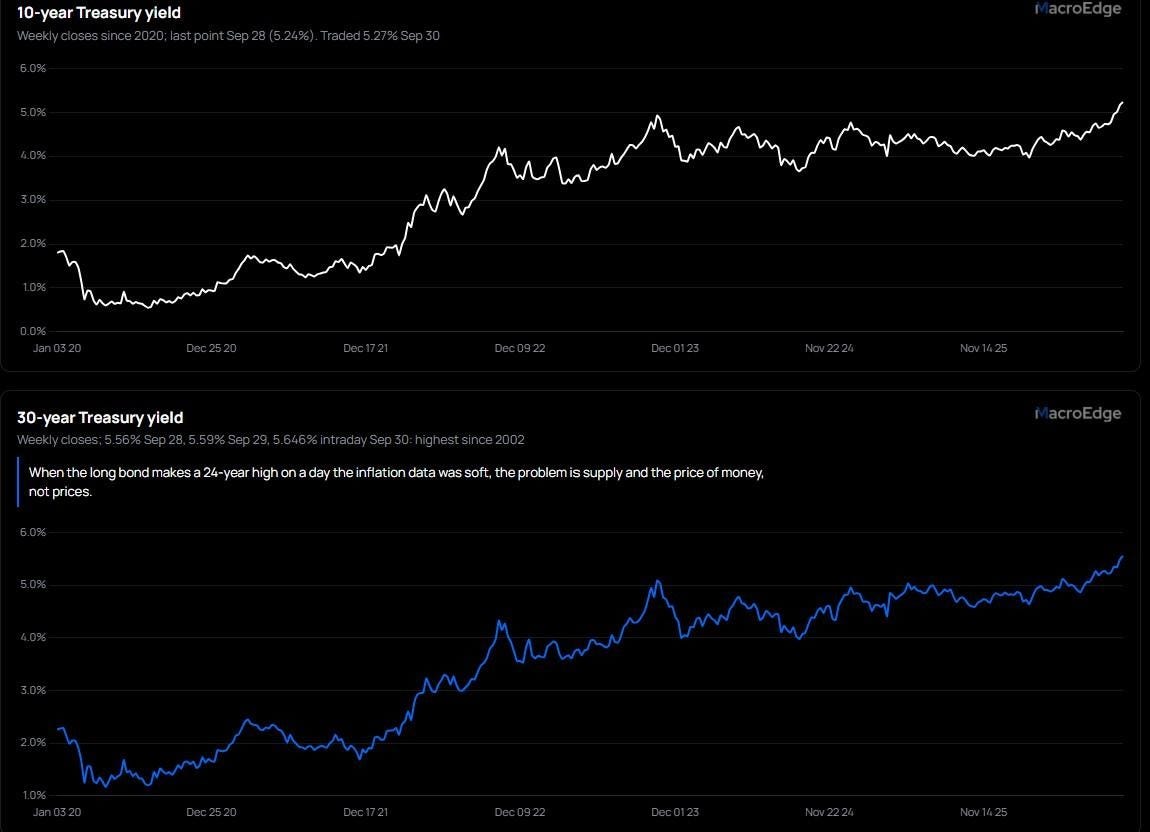
Real yields driving the move while inflation expectations have barely budged and financial conditions indices remain loose tells the story that things are just fine. This is true in upper tranches of credit and equity indices, but while the SPX is a hair off all time high, equal weight SPX is trending straight down, and CCC- bond spreads have widened substantially.
